


Arm Holdings PLC Stock (ARM) Opened Up by 3.20% on Sep 15: What Signal Does It Send?



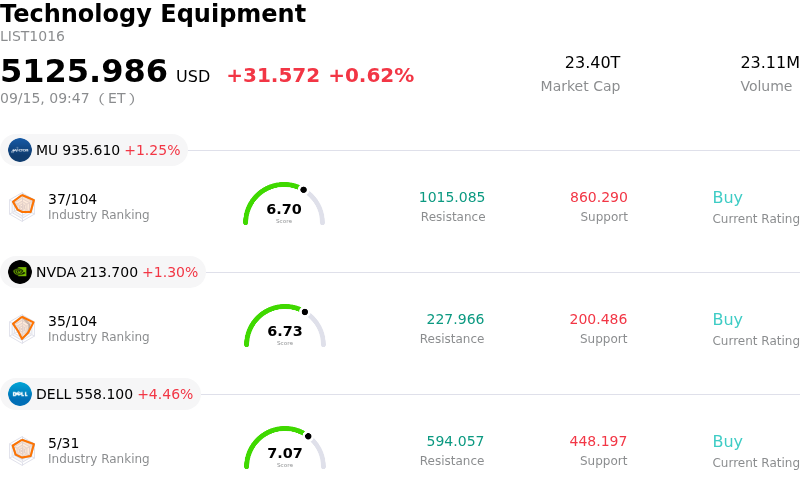
Arm Holdings PLC (ARM) opened up by 3.20%. The Technology Equipment sector is up by 0.62%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Micron Technology Inc (MU) up 1.15%; NVIDIA Corp (NVDA) up 1.27%; Dell Technologies Inc (DELL) up 4.67%.
What is driving Arm Holdings PLC (ARM)’s stock price up today?
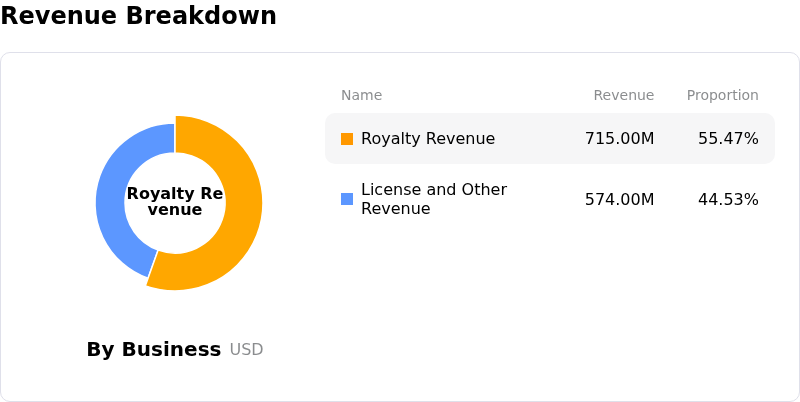
Arm Holdings experienced notable upward price momentum amidst elevated intraday volatility, driven by a broad stabilization in semiconductor market sentiment and targeted dip-buying following recent sector pullbacks. Investors stepped back into the stock as market participants re-evaluated the disconnect between short-term noise regarding artificial intelligence deployment timelines and Arm's resilient commercial model. Because Arm's top-line revenue relies primarily on fixed technology licensing agreements and volume-based chip shipment royalties, the business model remains insulated from transient fluctuations in software model release schedules, encouraging buyers to re-enter positions.
Underpinning the buying interest is Arm's continued structural transition toward higher-margin chip architectures and expanding server market share. The ongoing migration of global semiconductor partners to the Arm v9 architecture continues to elevate blended royalty rates across mobile, compute, and edge devices. Furthermore, rapid adoption of custom central processing units built on Arm designs across major hyperscalers and cloud service providers—particularly general-purpose server processors operating alongside AI accelerators—continues to generate multi-quarter royalty acceleration in data center compute.
Despite ongoing intraday swings fueled by elevated valuation multiples relative to the broader chip sector, institutional portfolio rebalancing reflects sustained appetite for primary compute layer providers. Market sentiment surrounding Arm remains anchored to its central positioning across custom silicon roadmaps and long-term licensing partnerships. While broader tech volatility and hardware demand cycles introduce short-term friction, the positive movement highlights strong investor conviction in Arm's expanding royalty take-rate and overall position within the global computing stack.
Technical Analysis of Arm Holdings PLC (ARM)
Technically, Arm Holdings PLC (ARM) shows a MACD (12,26,9) value of 3.604, indicating a neutral signal. The RSI at 47.041 suggests neutral condition and the Williams %R at 53.304 suggests neutral condition. Please monitor closely.
Fundamental Analysis of Arm Holdings PLC (ARM)
Arm Holdings PLC (ARM) is in the Technology Equipment industry. Its latest annual revenue is $4.92B, ranking 24 in the industry. The net profit is $904.00M, ranking 18 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $278.58, a high of $450.00, and a low of $125.00.
More details about Arm Holdings PLC (ARM)
Company Specific Risks:
- AI Infrastructure Capex Slowdown: Shares fell over 9% as industry debate among AI executives regarding safety and development pacing raised institutional concerns that cloud hyperscalers may decelerate capital expenditure on data center infrastructure, directly threatening growth expectations for Arm's server CPU and compute subsystem IP licensing.
- Extreme Valuation Multiple and Technical Fragility: Trading at an elevated forward P/E of 110x to 120x with a high beta (~3.89), the stock offers virtually no valuation safety margin, causing key short-term moving average breakdowns to trigger accelerated momentum-driven selling during market downturns.
- Smartphone End-Market Royalty Growth Deceleration: Mobile application processors generate approximately 43% of total royalty revenue, where management's reduced full-year royalty growth target to the high teens—driven by rising memory chip costs and sluggish mobile handset demand—continues to pressure earnings estimates.
- Regulatory Scrutiny and Patent Litigation Overhangs: Ongoing antitrust inquiries by the U.S. Federal Trade Commission into Arm's licensing practices, coupled with impending trial dates in its breach-of-contract dispute with major licensee Qualcomm, create lingering legal and contract-enforcement uncertainties.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.