


Ondo says US rules already allow stock perps



In a comment letter dated August 24, Ondo Finance has informed the SEC and CFTC that new regulations are not required to allow trade in perpetual contracts based on US stocks. The letter argues that the current framework of security futures accommodates the product. The document attempts to turn a matter of definition into a test of the readiness of the US regulators for incorporating the always-on derivatives market of crypto within their structure.
The stakes are already apparent abroad. Perpetual futures linked to stocks listed in the US have been traded out of reach of American investor protections and market surveillance. Analysis of equity-perpetual markets by Messari indicates that billions of dollars have already been transacted on newer platforms, and the inability of the US to regulate the market is the reason behind its development in overseas locations. One of the companies that is developing this market abroad is Ondo and it seeks the same solution to be made available in the US as well.
What is Ondo asking the agencies to do?
The comment, submitted jointly by Ondo Finance and broker-dealer affiliate Oasis Pro Markets, responds to the agencies’ June request for input under File No. S7-2026-21 on how “swap” and “security-based swap” should be defined.
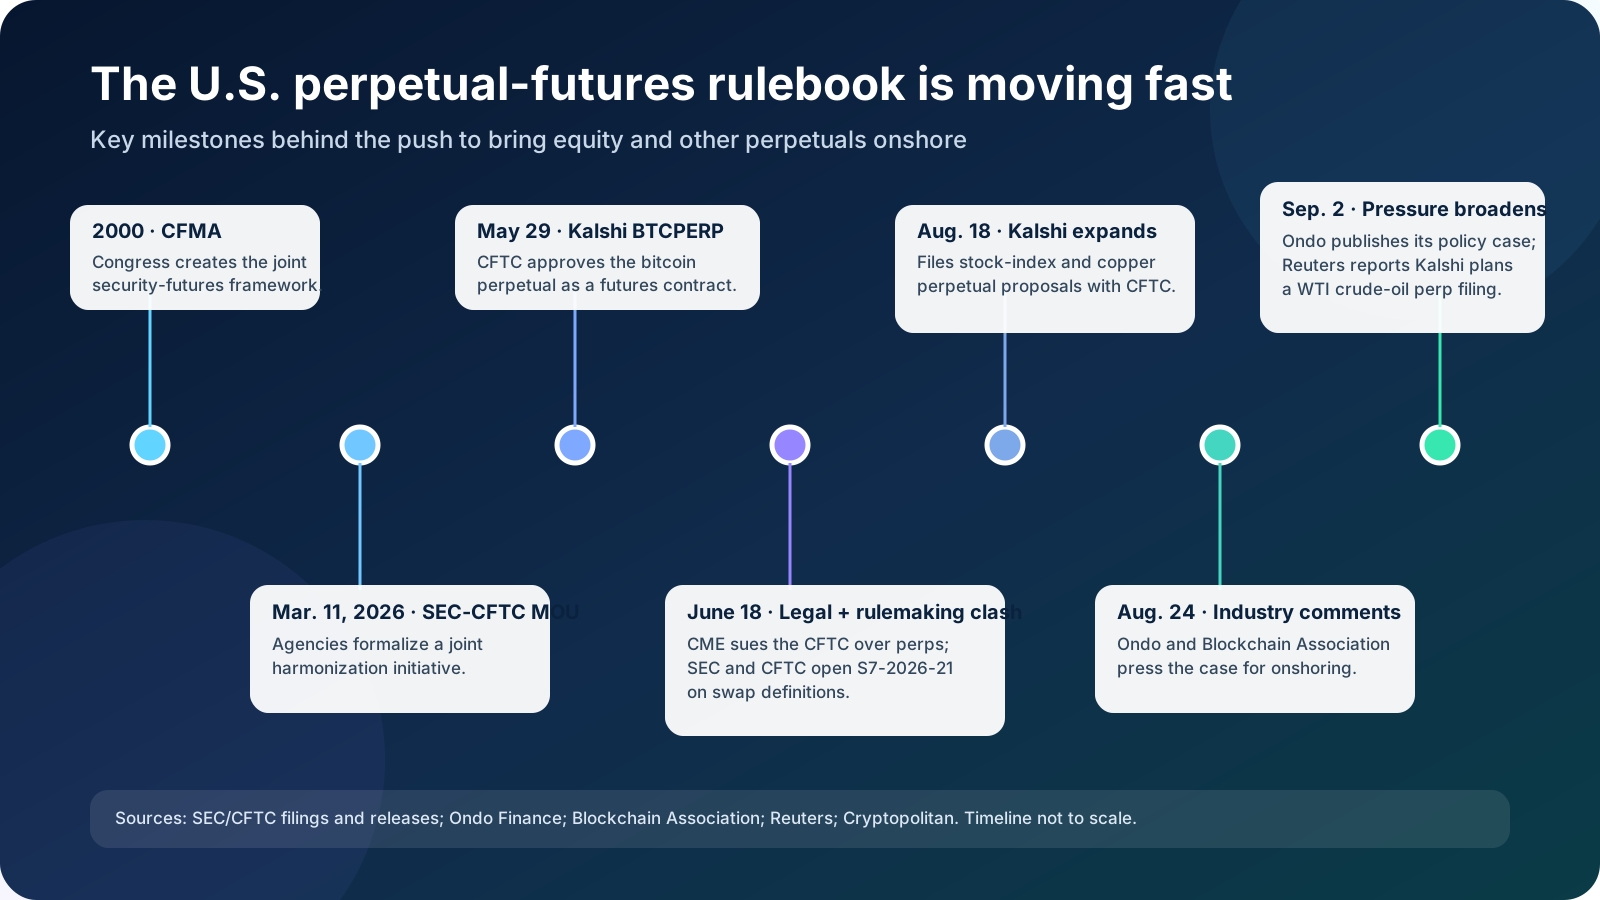
The argument presented by Ondo is limited yet significant. According to Ondo, a cash-settled perpetual contract that is linked to a single stock can already be classified as a security future in accordance with the Commodity Futures Modernization Act of 2000. It establishes a dual regulatory framework by creating the SEC-CFTC joint regime and a notice-registration path, allowing an entity registered with either agency to easily register with the other without creating a separate entity.
The legal matter being examined comes down to expiration. Ondo claims that the statute defines a security future by the underlying asset as well as how it settles, not by the presence of a set maturity date. Viewed through this lens, a perpetual works like a traditional futures contract, but without an expiration date; funding payments and mark-to-market settlements replace the calendar. The larger point Ondo makes is that regulatory authorities do not need to wait for a one-size-fits-all approach before taking action, as the current framework allows them to review individual filings.
A live offshore platform makes the case
Ondo is not making inflatable statements. Its subsidiary, Ondo Global Panama Inc., is providing a platform for non-US customers that offers trading of US-listed stocks using stablecoin-settled perpetual futures contracts. Ondo indicated that the amount of trading on its platform over six weeks since its launch had exceeded $8 billion by August 14. Additionally, Onno Finance states that it has about $4 billion worth of tokenized assets in its ledger and is also the leader in the market of tokenized equities.
In a blog post on September 2, Ondo connected three comment letters concerning product definitions, portfolio margining and data reporting to the same idea: technology has evolved, and so should regulators’ approach towards meeting their policy objectives. The company pointed out that there is “something backwards about perps on U.S.-listed stocks trading entirely offshore” and pushed both regulatory bodies to prioritize making transactions happen in the U.S.
Why the timing matters now
Ondo is not the only one taking action in this area. The Blockchain Association, which claims to represent over 100 members, has also released an August 24 letter calling on regulators to adopt the current security-futures framework to be applied in equity perpetuals. It cautioned that, as time passes, it may be harder to attract liquidity back as user habits and market depth harden around foreign venues. Both letters highlight the SEC-CFTC harmonization effort started in March 2026.
The opportunity has increased since that time. According to Cryptopolitan, the CFTC greenlit Kalshi’s BTCPERP on May 29 and characterized it as futures contracts while saying that additional perpetual derivatives would be considered on a case-by-case basis. Michael Selig, the head of the CFTC, also claimed that the decision opened a way for crypto perpetuals to function legally in the US.
Since then, Kalshi has filed for perpetual contracts associated with a US stock market index and copper. On September 2, it was reported that the company is making preparations to file for perpetuals connected to West Texas Intermediate (WTI) crude oil. Former SEC and CFTC officials, in a public letter sponsored by Kalshi. It mentioned that poor regulations keep pushing trading offshore, referring to Kalshi’s estimates of perpetuals traded overseas in 2025 at over $90 trillion.
The road continues to be unclear. CME Group filed a lawsuit against the CFTC in June, claiming that perpetual contracts ought to be classified as swaps instead of futures. The resolution of that argument could determine the future of onshoring. The next sign will be whether the SEC and CFTC staff show openness to product-specific filings and how they work out their contradictory views on whether the instruments are classified as swaps or futures.
Security futures have a specific regulatory architecture involving both the SEC and CFTC, plus exchange, clearing, margin, surveillance, position-limit and trading-halt requirements. The CFTC confirms that single-stock futures were authorized by the Commodity Futures Modernization Act of 2000 and are subject to joint SEC-CFTC oversight. So, the debate isn’t about whether “Are stock perps legal?” but increasingly about whether individual-stock perps qualify as security futures.
| Regulatory question | Position |
|---|---|
| Can a no-expiry contract be a future? | Ondo/Hyperliquid: Yes |
| Does funding substitute economically for expiration? | Ondo: Yes |
| Does that automatically make it a security feature? | Disputed |
| Could some stock perps instead be security-based swaps? | FalconX: Yes |
| Does classification solve exchange/clearing/margin issues? | No |
| Could existing U.S. rules accommodate them? | Potentially, but implementation is unresolved |
The smartest crypto minds already read our newsletter. Want in? Join them.
추천 기사







코멘트 (0)
$ 버튼을 클릭하고, 종목 코드를 입력한 후 주식, ETF 또는 기타 티커를 연결합니다.