


Berkshire Hathaway Stock Forecast: Saturday Earnings Put $563.71 Support in Focus



AI Podcast


Berkshire Hathaway’s upcoming earnings report will test whether its recent market rally is justified by underlying business performance rather than currency swings or portfolio gains. Key focus areas include insurance underwriting margins, cash deployment strategies, and the integration of the Taylor Morrison acquisition, alongside potential wildfire litigation risks for PacifiCorp. Technically, the stock maintains a mildly bullish outlook above the immediate support level of $563.71, though an overbought RSI momentum of 75.15 and resistance at $579.77 leave little room for earnings disappointment upon Monday’s market reopening.

TradingKey - Berkshire Hathaway’s (NYSE: BRK.B) Saturday earnings release puts capital allocation at the centre of the weekend outlook. The question for Monday’s reopening is whether stronger operating businesses can justify the recent rally, with $563.71 the immediate support test.
The pre-weekend market reference is $572.33, the latest completed close available at the research cutoff, before Friday’s session finished. This preview precedes the November 7 results, scheduled for approximately 7 a.m. Central, or 6 p.m. Pakistan time, according to Berkshire’s release notice.
Operating Profit Needs a Currency Adjustment
Berkshire’s second-quarter release reported operating earnings of $12.98 billion, against $11.16 billion a year earlier. GAAP net earnings were $25.67 billion, including $12.68 billion of investment gains. Those portfolio gains should not be mistaken for recurring business income.
Even operating earnings require scrutiny. The quarterly filing includes a $326 million currency gain on foreign-currency debt, compared with an $877 million loss a year earlier. That $1.20 billion favourable swing explains a substantial part of the $1.82 billion operating-profit increase. I would look for improvement beyond currency movements before treating the headline growth rate as sustainable.
Insurance Must Protect Both Earnings Streams
Insurance underwriting earnings, the profit left after claims and expenses, fell to $1.73 billion from $1.99 billion in the second quarter. Insurance investment income declined to $3.06 billion from $3.37 billion, according to the company’s earnings breakdown.
The weekend report therefore needs to show more than premium growth. Claims inflation and catastrophe losses affect underwriting, while investment returns influence what Berkshire earns before claims are paid. Pricing discipline matters more than expanding policies at unattractive margins.
Cash Deployment Must Improve Returns
Reuters reported that cash and Treasury holdings fell to $364.7 billion at June 30 from $380.2 billion three months earlier. Berkshire purchased $23.5 billion of equities and repurchased approximately $4.5 billion of its own shares during the second quarter.
These historical figures establish the comparison for the new report. A lower cash balance is encouraging only when investments offer attractive returns. Buybacks also need to be judged against the price paid: spending more after a rally does not automatically create more value for remaining shareholders.
Housing and Rail Broaden the Earnings Test
Berkshire completed the Taylor Morrison acquisition on July 24 for approximately $6.8 billion in equity value and $8.5 billion in enterprise value, including debt. The company’s acquisition announcement says Taylor Morrison will integrate with its existing site-built homebuilding operations.
The third quarter captures only the period after completion. Its contribution should be separated from growth at existing businesses, particularly when assessing housing demand and integration costs. Mortgage affordability and capital tied up in land remain relevant risks.
The second-quarter filing showed BNSF earnings of $1.56 billion, up from $1.47 billion, and manufacturing, service and retailing earnings of $4.47 billion, versus $3.60 billion. Continued improvement would reduce reliance on insurance and portfolio gains.
Wildfire Litigation Could Absorb Capital
A Reuters report said Oregon’s Supreme Court heard arguments on November 3 over restoring a wildfire verdict against PacifiCorp. An appeals decision had overturned $1.25 billion in awards; the hearing itself did not establish a final outcome.
This remains contingent exposure rather than a newly settled bill. Nevertheless, adverse litigation developments could require more utility funding, competing with acquisitions and other uses of Berkshire’s cash.
Saturday’s Report Sets Up Monday’s Reaction
The official schedule puts the earnings release outside regular stock-market hours. When markets reopen Monday, investors can judge cash deployment against insurance profitability and the contribution from newly acquired businesses.
A stronger result would combine resilient underwriting with earnings growth that survives the removal of currency effects. Weaker insurance economics or acquisition spending without corresponding profit would make the recent rally harder to justify. The release is the weekend catalyst; Monday’s price response will test whether expectations were already too high.
Berkshire Hathaway Technical Analysis: $563.71 Must Hold
The supplied daily chart shows a pullback from $586.30 to the $572.33 reference close after a steep advance. Buyers failed to hold $579.77, leaving that level as the first resistance barrier when regular trading resumes. The reference predates Friday’s completed session, so it is not a confirmed weekly closing price.
Support at $563.71 sits close to the 161.8% Fibonacci extension near $563.85, a projected level based on the earlier price move. A successful retest would preserve the continuation setup. I remain slightly bullish while that support holds, but would want a daily close back above $579.77 before favouring another advance towards $591.46.
RSI, a momentum gauge, is 75.15 on the supplied chart and explicitly overbought. Positive MACD still supports the upward trend, but overbought momentum leaves less room for an earnings disappointment. A daily close below $563.71 would invalidate the immediate bullish setup and expose $549.11. If earnings cause Monday to gap beyond these levels, the opening range and subsequent retest must take priority over this earlier framework.
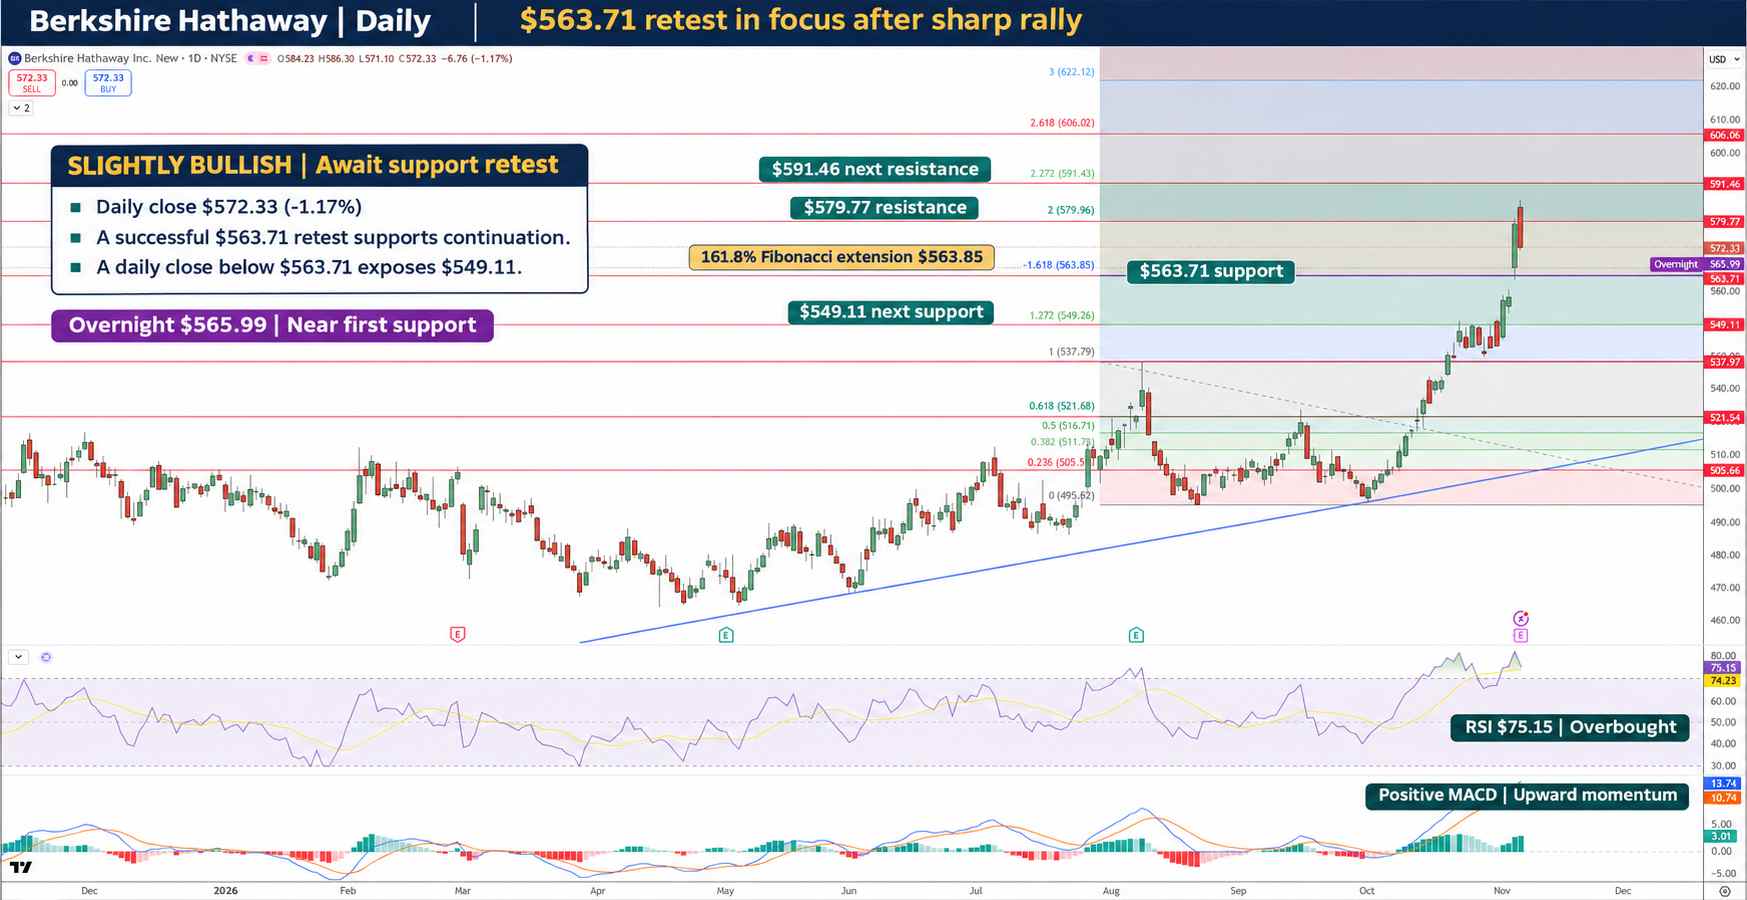
BRK.B Price Chart - Source: Tradingview
Key Levels
- Latest verified completed close at research cutoff: $572.33; Friday close pending
- Immediate resistance: $579.77
- Upside target: $591.46
- Immediate support: $563.71; Fibonacci reference: $563.85
- Downside target: $549.11
- RSI: 75.15, overbought on the supplied daily chart
FAQ
Why is Berkshire Hathaway in focus this weekend?
Its Saturday results will test whether cash deployment and underlying business profits support the rally before Monday’s reopening.
What would confirm further BRK.B upside?
Holding $563.71 and closing above $579.77 would strengthen the recovery case. A daily close below support invalidates the immediate bullish view.
Bottom Line
I favour a mildly bullish setup above $563.71, provided operating results support it. Insurance weakness and utility liabilities remain the main risks. A $579.77 reclaim strengthens the case; losing $563.71 shifts attention to $549.11.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.