


Shopify Tumbles 18% Pre-Market Post-Earnings to Near Two-Month Low as Q3 Revenue of $3.74 Billion Slightly Misses Estimates



AI Podcast


On November 3, Shopify’s stock dropped over 18% post-earnings despite Q3 revenue surging 32% year-over-year to $3.742 billion, narrowly missing expectations. Profitability metrics strengthened, with adjusted EPS reaching $0.49 and free cash flow jumping 61% to $816 million. However, investor sentiment soured due to a slowdown in gross merchandise volume growth to $119.15 billion, missing estimates. Q4 guidance failed to provide upside catalysts, and while strategic investments in AI-driven e-commerce offer long-term potential, near-term revenue contributions remain uncertain, intensifying valuation pressures amid high growth expectations.

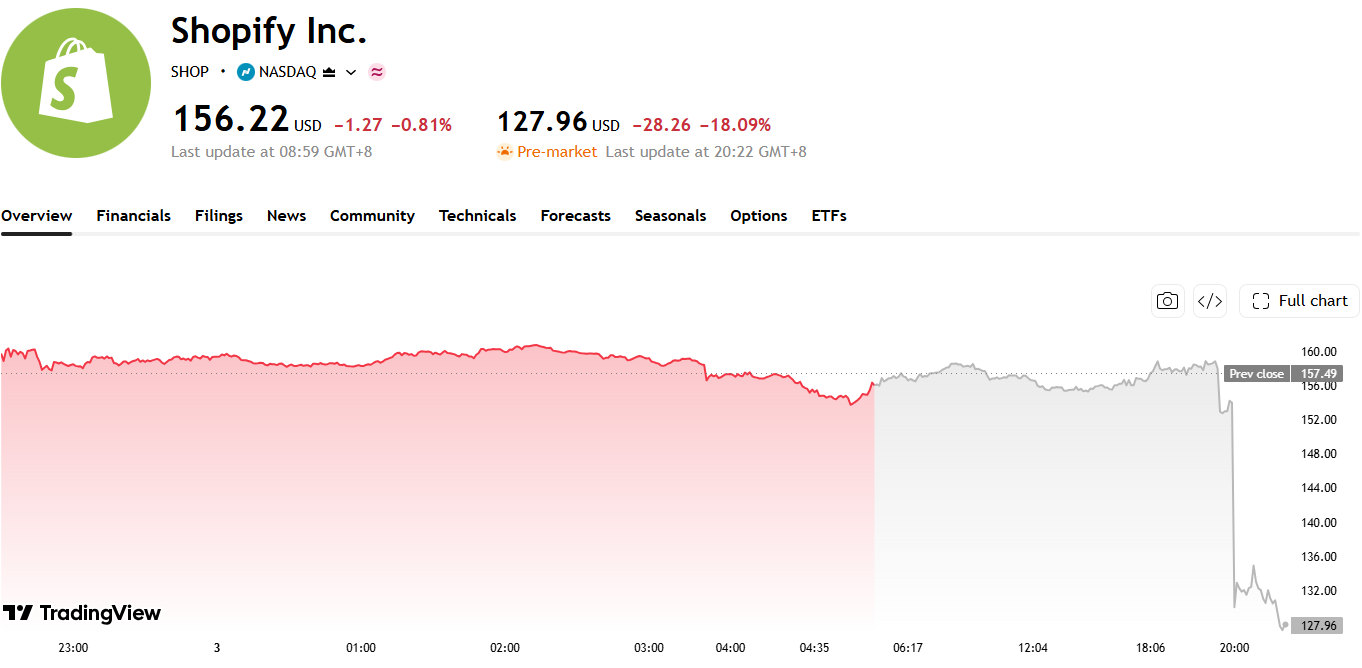
TradingKey - On November 3, after Shopify (SHOP) reported its third-quarter 2026 results, its stock fell by more than 18% in pre-market trading. The company recorded revenue of $3.742 billion for the quarter, up 32% year-over-year, slightly missing market expectations of $3.75 billion. Although the difference was only about $8 million, against the backdrop of a valuation already reflecting high growth expectations, even a slight miss triggered a noticeable sell-off.
Source: TradingView
The earnings report was not weak across the board. Shopify's third-quarter adjusted earnings per share came in at $0.49, topping analysts' expectations of $0.47. Operating income rose from $343 million in the prior-year period to $568 million, while net income climbed from $264 million to $462 million. Free cash flow reached $816 million, up 61% year-over-year, with the free cash flow margin increasing from 18% to 22%, demonstrating that the company continues to improve its profitability and cash generation while expanding revenue scale.
What truly unnerved investors was a slowdown in gross merchandise volume (GMV) growth. In the third quarter, GMV on Shopify's platform grew 29% year-over-year to $119.15 billion, missing analysts' estimates of roughly $120 billion, with the growth rate also cooling from 31% in the previous quarter. Because a substantial portion of Shopify's revenue comes from payment processing and other services tied to merchant transaction volume, the slowdown in GMV may impact the future growth rate of merchant solutions revenue.
Looking ahead to the fourth quarter, Shopify expects year-over-year revenue growth to remain in the low-30% range, with gross profit growth expected to be in the high-20% range. Operating expenses are projected to represent 29% to 30% of revenue, while the free cash flow margin is expected to be roughly flat compared with the same period last year. Overall guidance did not show significant deterioration, but it also failed to provide new catalysts strong enough to drive further upward revisions in market expectations.
Shopify is currently accelerating its expansion into AI-driven agentic e-commerce, aiming to enable consumers to search for products, compare options, and complete checkout directly through AI assistants. While the market is optimistic about this model creating new traffic channels for Shopify merchants over the long term, the actual revenue contribution of related businesses remains unclear at this stage.
This content was translated using AI and reviewed for clarity. It is for informational purposes only.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.