


Synopsys Stock Forecast: OpenAI and Amazon Deals Fuel Rally After Growth Reset



AI Podcast


Synopsys rallied significantly following an upbeat fiscal 2027 growth framework, a $1+ billion agreement with Amazon, and an AI partnership with OpenAI. Management projects fiscal 2027 revenue between $11.1 billion and $11.2 billion, with a non-GAAP operating margin of 44%. While fiscal Q3 results showed strong 42% revenue growth driven by EDA and the Ansys acquisition, integration risks and elevated GAAP-to-non-GAAP adjustments remain. Technically, the stock broke its descending trendline to close at $490.54, though an RSI of 81 signals overbought conditions, favoring a potential consolidation near the $465–$476 support zone before testing higher resistance.
Synopsys (SNPS) is up nearly 18.2% over the last two days and 12.78% on October 1 to close at $490.54. Investors have many reasons for reassessing Synopsys’ growth potential. Synopsys held its Investor Day in September and also announced a $1+ billion agreement with Amazon.com (AMZN) and a new partnership with OpenAI.
What is interesting for me, though, is the rally is not just based on sentiment regarding AI. Synopsys announced improved financial framework for fiscal 2027, which includes greater revenue growth and expanded margins. Also, while the opportunity is improved, the expectations for execution are greater, as the bar has been reset after the repricing.
Investor Day Resets the Fiscal 2027 Growth Framework
During its September Investor Day, Synopsys guided fiscal 2027 revenue to between $11.1 billion and $11.2 billion. The company also increased its non-GAAP operating margin target for fiscal 2027 to approximately 44%, with non-GAAP diluted EPS expected to be between $19.04 and $19.12. Synopsys also expects approximately $3.6 billion in operating cash flow for fiscal 2027 and approximately $3.1 billion in free cash flow.
Revenue growth and margin expansion are the most important parts of the new framework. Revenue growth alone would be less compelling if incremental costs and AI investments absorbed most of the incremental profit. For me, the question is whether Synopsys can move toward the target margin while continuing to invest aggressively in engineering software, AI, and Ansys, Inc. (ANSYS) integration.
Amazon Deal Adds a Commercial Foundation
On September 30, Synopsys announced a multi-year, over $1 billion agreement with Amazon to expand Amazon's adoption of Synopsys's silicon IP and AI-based software. The companies also plan to collaborate across Trainium, Graviton, AWS infrastructure and AI-powered engineering workflows.
This deal has strategic importance as Synopsys evolves its silicon IP business model toward license and royalty. Synopsys believes it can derive value during product development and participate in long-term volumes through royalties. I would be conservative in considering the overall contract value of over $1 billion as immediate revenues, as timing of recognition and volumes sold will determine the actual revenues.
OpenAI Partnership Expands the AI Software Opportunity
On September 30, Synopsys and OpenAI announced a multi-year partnership to create GPT-Synopsys. OpenAI will license Synopsys's electronic design automation (EDA) software and the companies will conduct research, and build and commercialize the product together. Early engagements with customers in the semiconductor industry have begun.
This partnership has a more practical focus. GPT-Synopsys has the potential to drastically reduce the time it takes engineers to explore and interpret designs. It can also have an automate and accelerate complex workflows. In the practical, near-term view, it could enhance Synopsys's software offering. The productization and commercialization of GPT-Synopsys could increase the overall revenue run rate and margins, potentially justifying higher cost of compute and development.
Q3 Fundamentals Support the Growth Story
Synopsys’ fiscal Q3 2026 revenue increased by approximately 42.4% to $2.477 billion, from $1.740 billion in the same period in the previous year. GAAP diluted EPS was reported at $2.84, and non-GAAP EPS was $3.91. Management said results reflected broad-based strength, led by EDA, a strong quarter from Ansys, and Design IP returning to year-over-year growth.
Synopsys acquired Ansys in July 2025, and as a result, the 42% revenue growth should not reflect organic growth. The expectation for fiscal year 2026 suggests revenue of approximately $2.98 billion from Ansys. Pro-forma growth from the combined company and margin expansion become more relevant and useful than simple year-over-year revenue comparisons.
Ansys Integration Remains a Major Execution Test
With the Ansys acquisition, Synopsys broadened its silicon-to-systems engineering platform, connecting chip design with simulation and system-level analysis. With the growing requirements to optimize AI systems, the combination logically adds strategic value, assuming integration costs are eliminated through more synergistic selling of related products.
Integration also carries significant execution risk. The combined company is meaningfully larger from a cost perspective, and the fiscal 2027 forecast shows large adjustments for acquired-intangible amortization, stock-based compensation and restructuring. For shareholders, the best evidence of successful integration will be sustained cash flow growth, improved operating margins and operating leverage as opposed to focus on headline revenue growth.
Capital Allocation Adds Another Support
Synopsys announced its intentions to purchase approximately $1 billion dollars of shares over the next few months. The company also announced it's longer-term capital allocation strategy is targeting a return to shareholders of up to 50% of free cash flow. From here, investors get a better idea of how cash flow is distributed to them.
This announcement was largely a positive for the company, however it shouldn't outweight what's going on with the business. Synopsys needs to continue funding various growth projects such as AI, Ansys integration and engineering. The more bullish case for investors is one where free cash flow continues to rise giving management the ability to continue to invest and grow the business while still supporting share repurchases.
Valuation Depends Heavily on the Earnings Measure
SNPS closed at $490.54 on October 1. Using the midpoint of management's guided non-GAAP EPS for fiscal 2027, the multiple is approximately 25.7. Using the GAAP EPS midpoint of approximately $8.39 yields a multiple of approximately 58.5. The adjusted items in the GAAP-to-non-GAAP reconciliation to determine the differences in the multiples are acquired intangible amortization, stock-based compensation, restructuring, and tax items.
This is an important distinction considering SNPS rallied approximately 12.78% on October 1. The non-GAAP multiple is justified considering the growth and cash flow the company is expecting to generate. The multiple using GAAP EPS shows management has a lot of work to do to bring down the company's expenses and costs. This is a constructive view for the company, but the valuation is requiring more cleaner execution.
Synopsys Technical Analysis: SNPS Breaks Downtrend as Bulls Target $508.51
Synopsys (SNPS) broke its long-term descending trendline and the $475.95 resistance zone to the upside on Thursday, closing at $490.54. I like this setup given how large the breakout candle was, how clean the breaks were above both barriers, and the change in the short-term trend from bearish to bullish. In addition, price closed near the session high of $496.95, which adds to the bullish case.
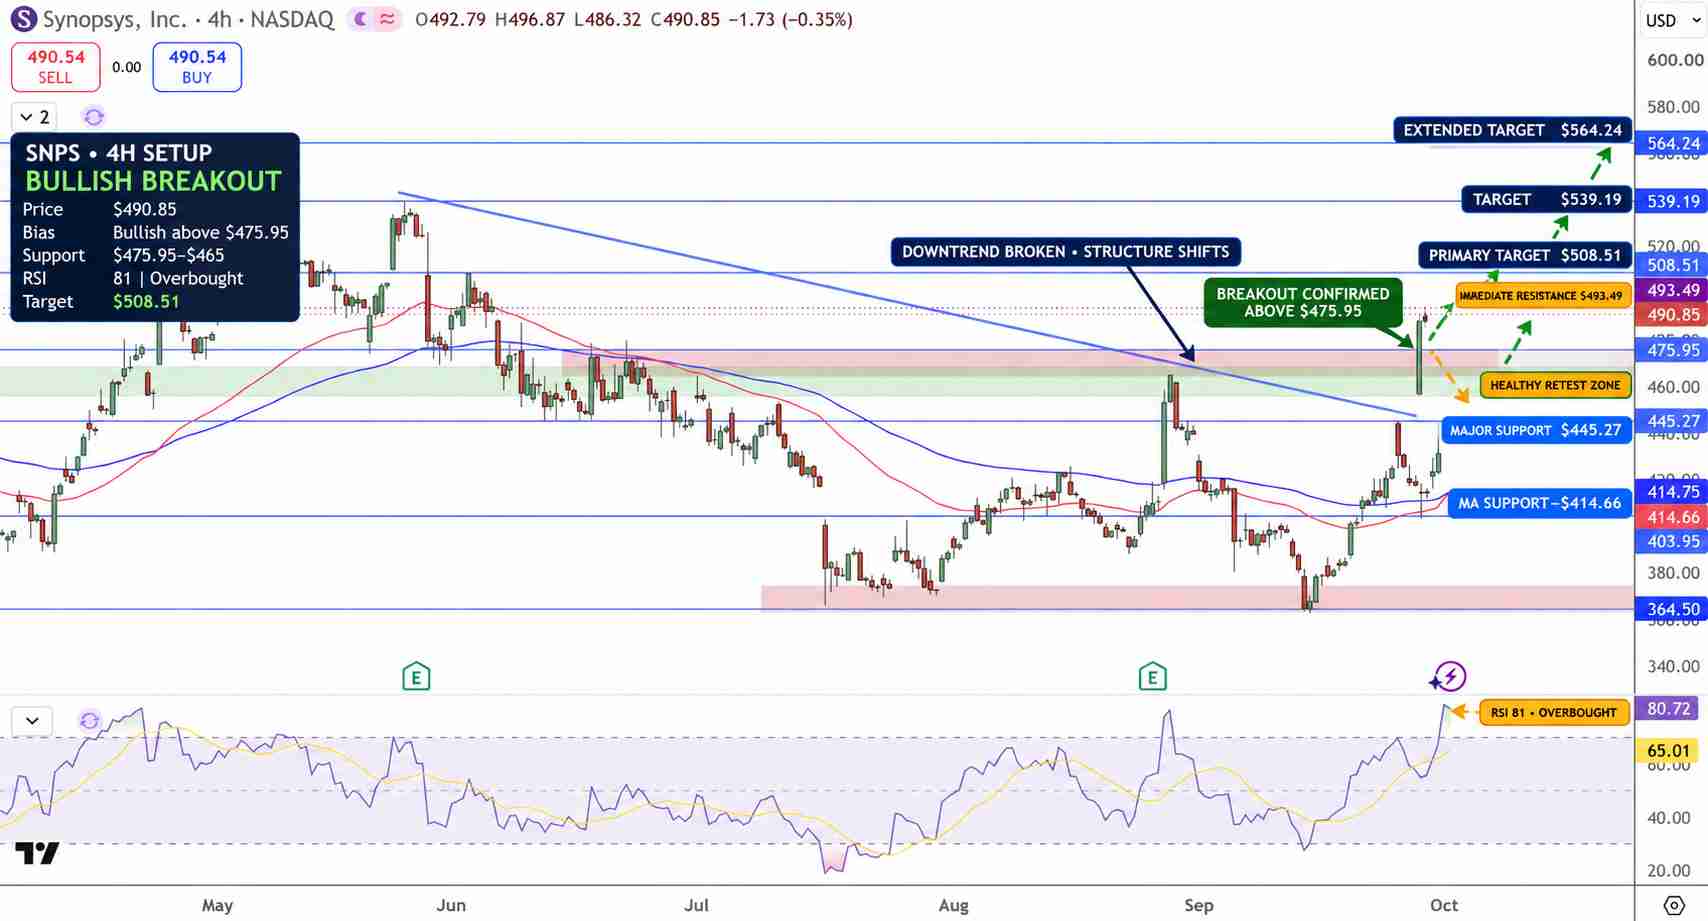
Synopsys Stock Price Chart - Source: Tradingview
RSI is pushing up to 81, well above its signal line (which is at 65) and in extremely overbought territory. Because of the extremely overbought status of RSI, I expect a pullback or consolidation to happen before the next leg up. Because of the former resistance turned support holding, I’d look to take profits on long positions above it rather than looking to buy dips.
Resistance stands at around $493.49, then a more significant level of $508.51. A close above $508.51 in the 4 hour time frame would confirm the bullish reversal. This would open the next target at $539.19, and then $564.24. The support levels remain the same, and are at $475.95 to $465, then $445.27.
The bullish case remains as long as SNPS holds above $475.95. Volatility is to be expected due to the overbought conditions, but a test of $476 to $465 to rebuild the breakout level is favorable.
Key Levels
- Latest Close: $490.54
- Major Support: $475.95 to $465, $445.27, then $414.75 to $414.66
- Major Resistance: $493.49, $508.51, then $539.19
- RSI: Approximately 81, strongly overbought
- Breakout Target: $539.19 above a confirmed $508.51 break
Why is Synopsys stock in focus now?
Investor Day revealed more bullish fiscal 2027 targets for Synopsys, while the company made public a larger than expected $1 billion+ custom-silicon agreement with Amazon and new partnership with OpenAI to utilize GPT technology. All of these catalysts should give Wall Street the bullish call options they are looking for.
What level confirms a stronger SNPS breakout?
A close above $508.51 on the 4-hour time frame would confirm the bullish move, target $539.19, and extend the target to $564.24. A move below $475.95 would indicate the post-Investor-Day breakout was a fake out.
Bottom Line
The case for Synopsys' investment opportunity improved dramatically at Investor Day. Synopsys now has a more defined financial framework for fiscal 2027, a big Amazon custom silicon deal, a partnership with OpenAI, and an improved capital return plan. The Q3 results and the positive contribution of Ansys support the magnitude of the opportunity even with the combined company having potential complexities of a large integration and remaining GAAP costs.
The bullish trend for SNPS is still intact above $475.95, but the stock is extremely overbought after the rally on Oct 1. A break above $508.51 would extend the upside to $539.19, while a more appropriate pullback to $465-476 would test the breakout support.
Recommended Articles






Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.