


Nike Q1 Earnings Preview: Can Transformation Reach an Inflection Point? Highest Wall Street Target at $75



AI Podcast


Nike is scheduled to report its first-quarter fiscal 2027 financial results after the U.S. market close on October 1, with revenue expected to decline 3% year-over-year to $11.32 billion. CEO Elliott Hill’s turnaround strategy faces headwinds from sluggish demand, weak performance in China, and rising competition from brands like On. Core profitability remains under pressure as new products struggle to offset declining classic lines and retail orders face cuts. Wall Street sentiment is increasingly divided, with Bank of America downgrading the stock to Underperform on prolonged sales risks, while Jefferies maintains a Buy rating anticipating stabilization in wholesale channels.

TradingKey - Nike (NKE) will report its first-quarter fiscal 2027 financial results after the U.S. market close on October 1. The market expects company revenue of approximately $11.32 billion, down 3% year-over-year; earnings per share are projected at $0.44, lower than $0.49 in the prior-year period.
This earnings report will once again test Nike's turnaround progress. Since returning in 2024, Chief Executive Officer Elliott Hill has been driving the company to refocus on performance sports products, restore wholesale channel relationships, and reduce reliance on promotions. However, sluggish consumer demand, pressure in the Chinese market, and the rapid expansion of competitors such as On continue to drag on the pace of recovery.
Nike's stock has fallen by more than 40% year-to-date, currently trading around $36, near its lowest level since 2013. Market focus is no longer just on whether the company can meet expectations this quarter, but on whether management will cut its revenue outlook for the next few quarters once again.
Revenue May Continue to Decline; Earnings Quality Still Needs Observation
Nike previously projected that first-quarter fiscal 2027 revenue would decline in the low-to-mid single digits, with pressure potentially intensifying further in the second quarter. The market consensus currently expects that company revenue may bottom out in the first half of fiscal 2027 and gradually recover to flat year-over-year in the second half.
However, Evercore ISI analyst Michael Binetti believes this path may be overly optimistic. Some retailers have already cut or canceled orders for Nike's spring 2027 products, suggesting that the second half of the fiscal year, originally seen as the starting point for a recovery, could also continue to face sales pressure.
Nike may wait until its November investor day to provide complete fiscal 2027 guidance again, but with new Chief Financial Officer David Denton in place, this earnings call could signal an adjustment in expectations ahead of time. If management wants investors to focus more on long-term turnaround plans in November, lowering short-term forecasts this quarter would not be surprising.
In June, Nike reported fourth-quarter fiscal 2026 revenue of approximately $11 billion, down 1% year-over-year; diluted earnings per share reached $0.72, though $0.52 of that came from a one-time gain related to anticipated IEEPA tariff refunds. Excluding this item, actual earnings per share were approximately $0.20, indicating that core profitability remains weak.
New Products, China Market and Retail Orders Determine Pace of Recovery
Nike's primary challenge at present is that new products have yet to fully offset the gap left by declining demand for its classic footwear lines. Stifel noted that consumer response to new products remains limited, while classic basketball product lines continue to contract. The company plans to introduce more innovative products in spring 2027, but there are already signs that retailers are cutting related orders.
The Chinese market is also a weak link in its transformation. In the previous quarter, Nike's Greater China revenue fell approximately 17% on a currency-neutral basis. The company previously acknowledged underinvesting in local stores, product mix, and consumer engagement, while also becoming caught in intense discount competition.
Meanwhile, On, Hoka, and other specialized athletic brands are competing for market share in running and lifestyle products. Soccer star Kylian Mbappé's recent end to his long-standing partnership with Nike to switch to On has further amplified market concerns over the brand's waning appeal.
Nike is restoring partnerships with major retailers, hoping to re-expand its product reach through wholesale channels. However, Dick's Sporting Goods previously warned that Nike's increased discounting to clear slow-moving inventory could continue to exert pressure on brand pricing and retail margins.
How Does Wall Street View Nike?
As Nike's stock price falls to multi-year lows, Wall Street's views on the company's turnaround prospects have diverged significantly. According to TipRanks, among 31 analysts covering Nike over the past 12 months, 8 rate it a "Buy," 17 recommend "Hold," and 6 advise "Sell," with an average price target of $43.25, a high of $75, and a low of $30.
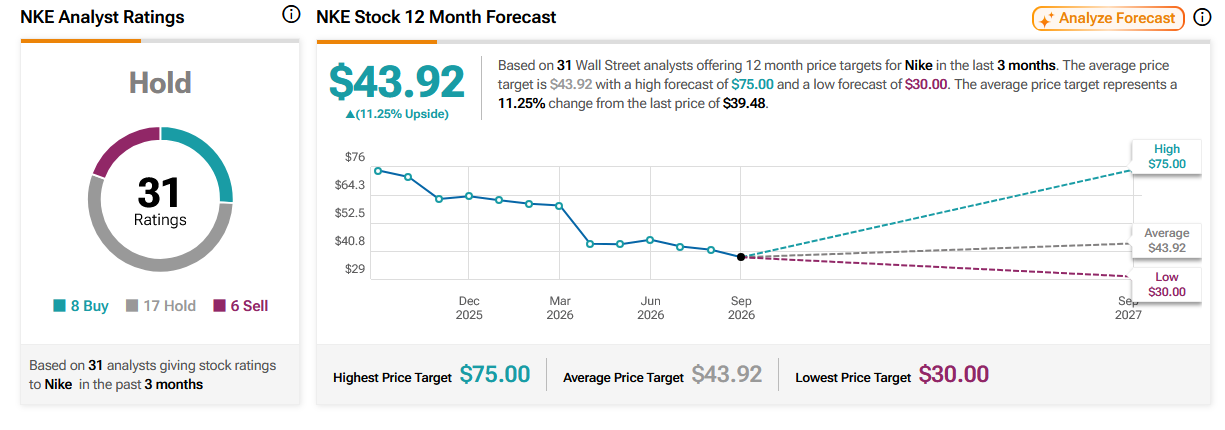
Source: TipRanks
Bank of America (BAC) recently downgraded Nike from "Neutral" to "Underperform" and lowered its price target from $47 to $30. Analysts believe that cautious consumer spending, weak demand for classic lifestyle shoes, and intensifying competition in the Chinese market may extend Nike's sales pressure through fiscal year 2027.
Jefferies (JEF), on the other hand, maintains a relatively optimistic view. The firm expects Nike's first-quarter revenue could reach $11.5 billion, with earnings per share of $0.48, both slightly above consensus expectations. Analysts believe that North America and wholesale channels may show signs of stabilization, thus maintaining a "Buy" rating and a $75 price target.
This content was translated using AI and reviewed for clarity. It is for informational purposes only.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.