


Darden Stock Forecast: Olive Garden Growth Faces September 24 Earnings Test



AI Podcast


Darden Restaurants prepares to report fiscal first-quarter 2027 results on September 24, with investor focus centering on same-store sales at Olive Garden and LongHorn Steakhouse, alongside operating margins. Consensus estimates project $3.2 billion in revenue and $2.05 in EPS. While LongHorn maintains strong growth momentum, Olive Garden faces challenging year-over-year comparables. Management’s fiscal 2027 guidance targets revenues of $13.60 to $13.75 billion and adjusted EPS of $11.10 to $11.35. Technically, the stock exhibits a neutral-to-bullish bias, holding key support near $211.84, with a decisive breakout above $217.28 required to target $221.64, while a drop below $206.49 invalidates the bullish structure.
TradingKey - Darden Restaurants (DRI) will release earnings on 9/24. The company has recently benefited from a stong operating performance. However, some remain uncertain about LongHorn's and Olive Garden's near term outlook. The stock is trading at $213.54, up 1.06% from its previous close. On Thursday, DRI will report its first quarter results of fiscal year 2027. Investors will closely monitor the earnings report and determine its impact on the company’s stock.
Olive Garden Is the Most Important Q1 Test
In fiscal year 2026, Olive Garden generated 5.59 billion in revenue, making it DRI’s largest revenue generating segment. Same store sales for the year increased by 4% and 2.4% for the fourth quarter. The fourth quarter sales growth was better than what the market expected. For Q1, Olive Garden will face a tougher year over year comparable. In Q1 of fiscal year 2026, same store sales for Olive Garden increased by 5.9%. Generating similar or better results for Q1 of fiscal year 2027 than last year will be difficult. In my opinion, if Olive Garden is generating same store sales for Q1 of fiscal year 2027 in the low single digits, the market should be satisfied, given no significant promotional offers were made to drive the sales.
I expect Olive Garden’s same store sales to be between 2.5% and 3%. I believe that if same store sales are stronger and EPS misses are smaller, driven by operational excellence rather than promotional offers, Olive Garden’s management will be satisfied with the result.
LongHorn Remains Darden's Strongest Growth Brand
LongHorn Steakhouse continues to provide positive revenue growth for Darden. In Fiscal Quarter 4 and the full fiscal year, LongHorn Steakhouse reported same restaurant sales growth of 9.5% and 7.2%, respectively. For the full fiscal year, LongHorn Steakhouse reported system-wide sales of $3.42 billion.
From a positive same restaurant sales growth of LongHorn Steakhouse, the company was able to achieve a 4.6% same restaurant sales growth for the quarter.
Strong same restaurant sales growth at LongHorn Steakhouse would indicate that Darden has the potential to continue positive same restaurant sales growth despite Olive Garden's more limited potential for growth.
Although Olive Garden accounts for a larger portion of the company's revenues, the same restaurant sales growth for both Olive Garden and LongHorn Steakhouse would indicate positive same restaurant sales growth for the company as a whole.
Consensus Sets a Modest Earnings Bar
The consensus estimates for the first fiscal quarter are $3.2 billion in revenue and $2.05 in earnings per share.
The company has not officially released Q1-specific guidance, however, the consensus estimates are generally conservative, and the company had adjusted earnings per share of $1.97 in the year-earlier quarter.
A beat by Darden this quarter would likely depend on the sales and margins for Olive Garden and LongHorn Steakhouse. If comparable sales and restaurant-level margins were positive for both restaurants, management could justify further growth initiatives for both brands.
Fiscal 2026 Provides a Strong Base
Darden reported fiscal 2026 results on June 25, 2026. Revenues increased to $13.21 billion from $12.08 billion in fiscal 2025, and blended same-restaurant sales increased by 4.5%. Adjusted earnings per share increased by 11.4% to $10.64.
An Extra Week in Fiscal 2026
One exception to the results for the year ending May 31, 2026 is that it contained 53 weeks, as compared to 52 weeks in fiscal 2025. Darden noted that the additional week accounted for approximately 2.1 percentage points of annual sales growth and $0.25 in earnings per share for the year. Blended same-restaurant sales reflect true trends in customer demand more so than revenues for the year.
FY2027 Guidance Is the Other Major Earnings Catalyst
Darden projects blended same-restaurant sales growth between 2.5% and 3.5% for fiscal 2027, revenues between $13.60 and $13.75 billion and adjusted earnings between $11.10 and $11.35 for the year.
The Company expects about 3% inflation. 75 to 80 new restaurants are anticipated to open next year.
A focus on same-store sales next quarter.
Margins are likely to be watched more closely next quarter as management guidance for same-store sales suggests no easing of promotional levels for customer traffic. It is unlikely that same-store sales guidance would be cut in the near-term. More so, changes in consumer demand would need to accelerate. A decrease in earnings guidance would likely be viewed more negatively.
Capital Returns Add Support, but Traffic Still Matters More
Darden reported earnings in June and announced an increase to its dividend as well as authorization of a new $1.5 billion share repurchase program.
Other news, including the announcement of quarterly dividends and share repurchase programs, are positive and supported the stock, but will not alleviate the need for same-restaurant sales growth and operating margins.
I continue to believe a more measured approach to investing Darden is warranted. Darden’s businesses, particularly Olive Garden and LongHorn Steakhouse, can be volatile and both need to be performing well for the stock to rally post-earnings.
Darden Restaurants Technical Analysis: DRI Reclaims $211.84 as Triangle Breakout Nears
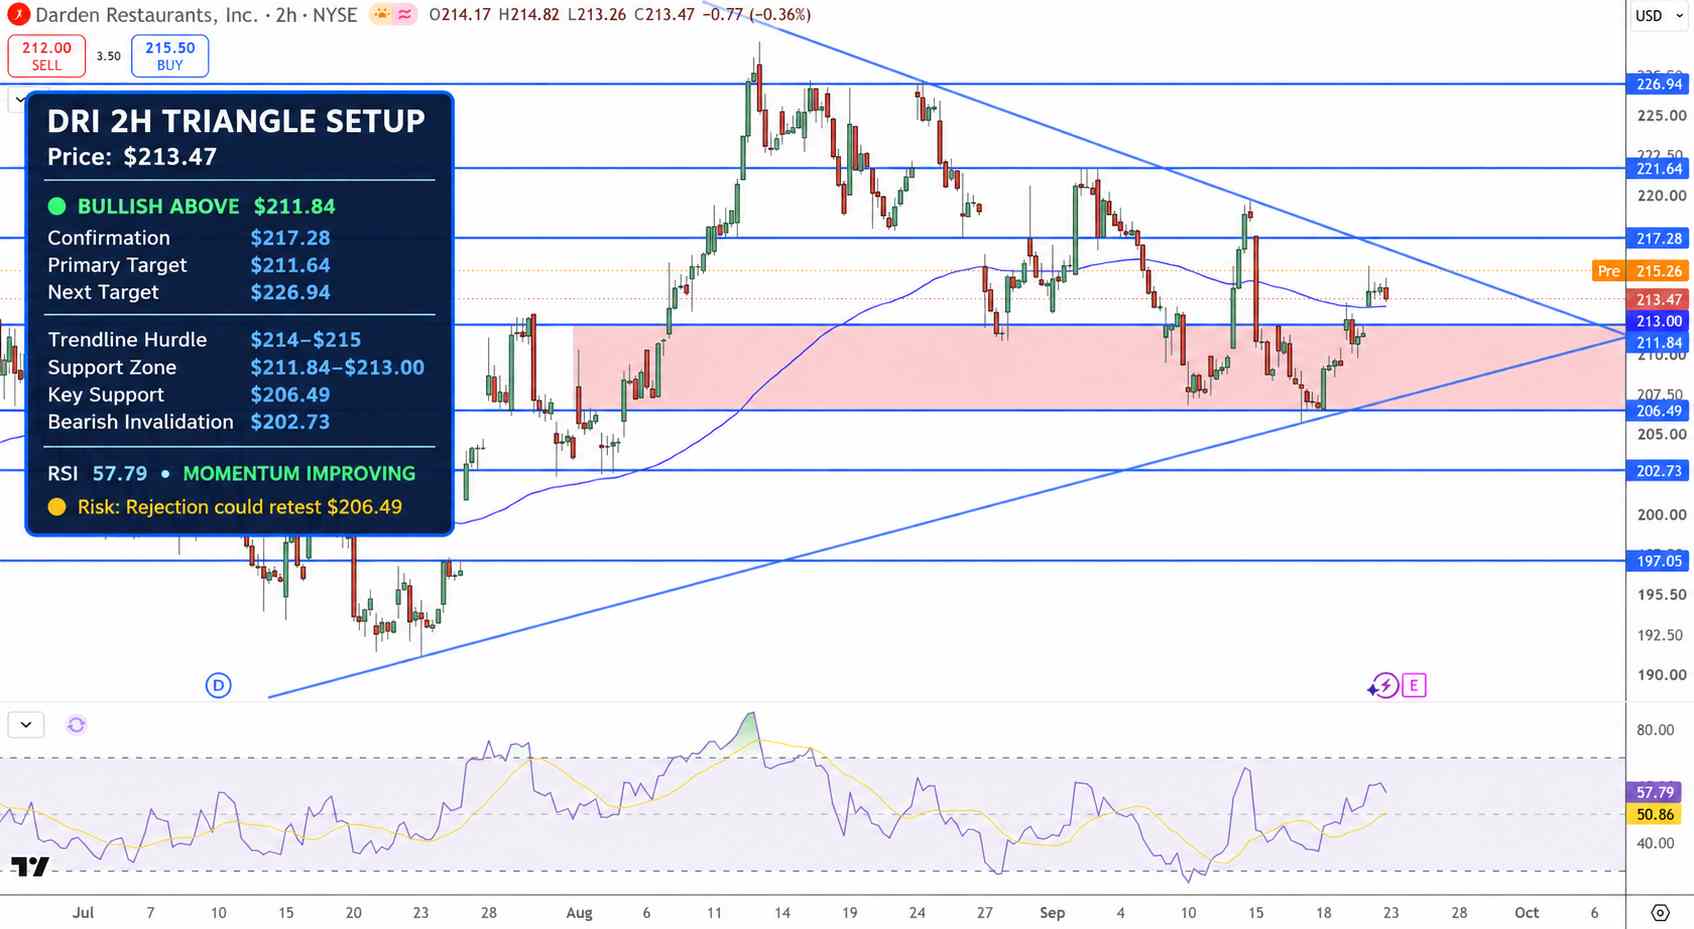
Darden’s shares have been trading sideways in the $200-215 range for the past couple of months. The $211.84 level had acted as resistance but has now been reclaimed and forms part of the near-term support zone.
Darden Stock Price Chart - Source: Tradingview
Earnings are expected to be released on Thursday, September 24. I expect shares to trade sideways until after the print.
Currently RSI is at about 58 with the signal line at 51. With the slight pullback today, we could see an additional leg up with some marginal new resistance formed by the breakdown from 218 to 214.
Current near term resistance is formed by the falling trend line starting at 214.50 and 217.28 with potential support at 211.84 to 213.00. Further support is seen at 206.49.
A break below 206.49 would invalidate the bullish bias and expose 202.73.
I am primarily bullish on this stock given its current levels and support, but break even levels formed by earnings could cause a large move lower.
Key Levels
• Current levels: $213.54
• Support: 211.84 to 213.00, 206.49, 202.73
• Resistance: 214 to 215, 217.28, 221.64
• RSI: 58, neutral to bullish
• Bullish break out target: 221.64
Why is Darden stock in focus now?
Darden is scheduled to release its Q1 fiscal 2027 results on September 24. As is the case with every earnings release, management’s outlook for the year will be closely monitored. Investors will also be looking for updates on the same store sales at Olive Garden and LongHorn as well as the restaurant’s operating profit.
What level confirms a stronger DRI breakout?
We think DRI remains in an improving trend as long as it trades above $211.84. In this case, we view a close above $217.28 as the breakout confirmation, with $221.64 as the first upside target and $226.94 as the next target. Should Darden break below $206.49, the improvement trend would be invalidated.
Bottom Line
Going into the earnings release, Darden has a number of things working in its favor, including improving LongHorn Steakhouse, and the opportunity to achieve mild growth in the fiscal year 2027. The company has to walk a thin line to ensure it does not give away its margins by undertaking promotional offers to boost sales.
From a technical perspective, the stock is already looking bullish and a move above $217.28 would confirm a move higher to $221.64. Conversely, a move below $206.49 would turn the current bullish setup bearish. The earnings release will likely determine the direction of the move.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.