


Seagate Stock Forecast: STX Breaks Trendline as AI Storage Demand Targets $935



AI Podcast


Seagate Technology reported robust fiscal 2026 results, driven by surging data center demand, which now accounts for 80% of revenue. Gross margins expanded significantly, bolstered by higher-capacity drives and the production ramp-up of the Mozaic 4+ architecture using HAMR technology. Despite strong AI-driven storage demand and an improving balance sheet, key risks include potential margin normalization and high execution bars for future guidance. Technically, the stock maintains a bullish outlook while trading above support at $898.86, though overbought RSI levels suggest near-term consolidation risks prior to testing higher resistance targets.
TradingKey - Seagate Technology (STX) ended up 4.85% at $919.84 on Tuesday, extending its September rebound. Its most recent quarter resulted in $3.63 billion in revenue. Margins improved. Seagate's Data Center business, which is its hyperscale storage business, accounts for the bulk of its revenue. Finally, Seagate's Mozaic 4+ architecture, which is its latest storage architecture and is targeted at hyperscale data storage, is also in production. The question is how long Seagate can command these strong margins.
Data Center Is Reshaping Seagate's Revenue Mix
According to Seagate’s recent financial filings, revenue from Data Center was 80% of total revenue for fiscal 2026 compared to 75% for fiscal 2025.
Nearline hard-drive exabytes shipped increased by roughly 40% to 695 exabytes from 497 exabytes, while total HDD exabytes shipped increased to 789 from 595.
For fiscal 2026, Seagate reported a 34% increase in revenue, primarily due to higher nearline exabytes shipped and favorable pricing actions. Seagate’s recent performance demonstrates that revenue and earnings are driven by a favorable combination of shipment volume and pricing. While this provides positive earnings upside, it means that to the extent the company ships a greater number of nearline hard drives, it is imperative that the company charge a greater revenue per nearline drive shipped.
Margins Are Expanding Much Faster Than Revenue
For the quarter, revenue of $3.63 billion exceeded the prior year quarter revenue of $2.44 billion. Gross margin per the GAAP method increased to 52.3% from 37.4% and the non-GAAP method increased to 52.7% from 37.9%. Earnings per share (EPS) increased non-GAAP to $5.71 from $2.59.
For the year, revenue increased to $12.20 billion. The GAAP operating margin improved to 33.6% from 20.8%. Free cash flow improved to $3.1 billion. The other metrics also reflect favorably. The non-GAAP gross margin improved to 46.1% from 35.8% for the year.
The improvement in gross margin has also been driven by selling higher capacity drives. Disciplined supply also played a role. The risk is that the gross margin structure will normalize to a lower level.
Mozaic 4+ Is Moving Into Production
Seagate’s most important product catalyst is the Mozaic platform. Seagate indicated that drives supporting capacities up to 44TB had been qualified and were in production with two leading hyperscale cloud providers. Mozaic drives employ HAMR technology to increase the areal density of a hard disk drive beyond 4TB per disk. As such, Seagate’s customer can increase storage capacity without expanding rack count, power use and cooling requirements at the same rate.
Seagate’s product roadmap increases areal density to 10TB per disk. For the Mozaic platform, the focus is on the initial product volume and customer acceptance. Should Seagate meet customer demand, the future of the platform appears robust.
AI Storage Demand Is Real, but Survey Data Is Not Orders
According to Seagate's September 14 report, 2,712 enterprise tech decision-makers said AI would cause storage demand to increase in the next 3 years. Only 38% said their companies are fully ready for the storage increase.
The survey makes a good case for increasing storage demand. But, contracts for Seagate sales were likely not increased because of the results of the survey.
I think the survey results show increasing storage demand because of AI. Retaining and retrieving data generated by AI in a cost effective manner will be important. Seagate shipped 695 nearline exabytes in fiscal 2026, and HAMR-based products represented approximately 40% of its nearline exabyte shipment run rate exiting the year. Mozaic 4+ is ramping with two of the largest global cloud service providers.
Q1 Guidance Sets a High Execution Bar
For FQ1 2027, Seagate provided revenue guidance of 4.1B(3.9B - $4.3B) and non-GAAP EPS guidance of 7.30(7.10 - $7.50). At the midpoint of their guidance, revenue would increase approximately 13% from the prior quarter.
Given their recent results, this level of revenue growth would be difficult to achieve. I would focus on nearline exabyte shipments, gross margin, volume of Mozaic 4+ shipments and whether favorable pricing remains intact. Seagate has not released an formal schedule for their next earnings release.
Balance Sheet Is Improving, but Share Dilution Matters
Seagate improved its balance sheet by retiring $1.4 billion of debt in FY 2026 and ending the year with total debt of $3.6 billion and cash of $1.7 billion.
On September 8, Seagate completed the settlement of the remaining $150.7 million principal of its 3.50% exchangeable notes due 2028.
Seagate cash paid of $150.97 million and delivered 1,647,862 ordinary shares to settle the notes.
The shares issued in the settlement increase the share count and can dilute EPS, all else equal.
Seagate Technical Analysis: STX Breaks Descending Trendline as $935.64 Comes Into Focus
Seagate Technology (STX) ended Tuesday's session at $919.84, essentially hitting its chart price of $919.75. The one hour chart shows STX ending its downward trend and breaking above the descending line that had been in place for several sessions and clearing the $898.86 level.
The upside target is now $935.64. A break above this level would give the upside target of $973.07. Beyond this level, the next major upside target is $1,012.72.
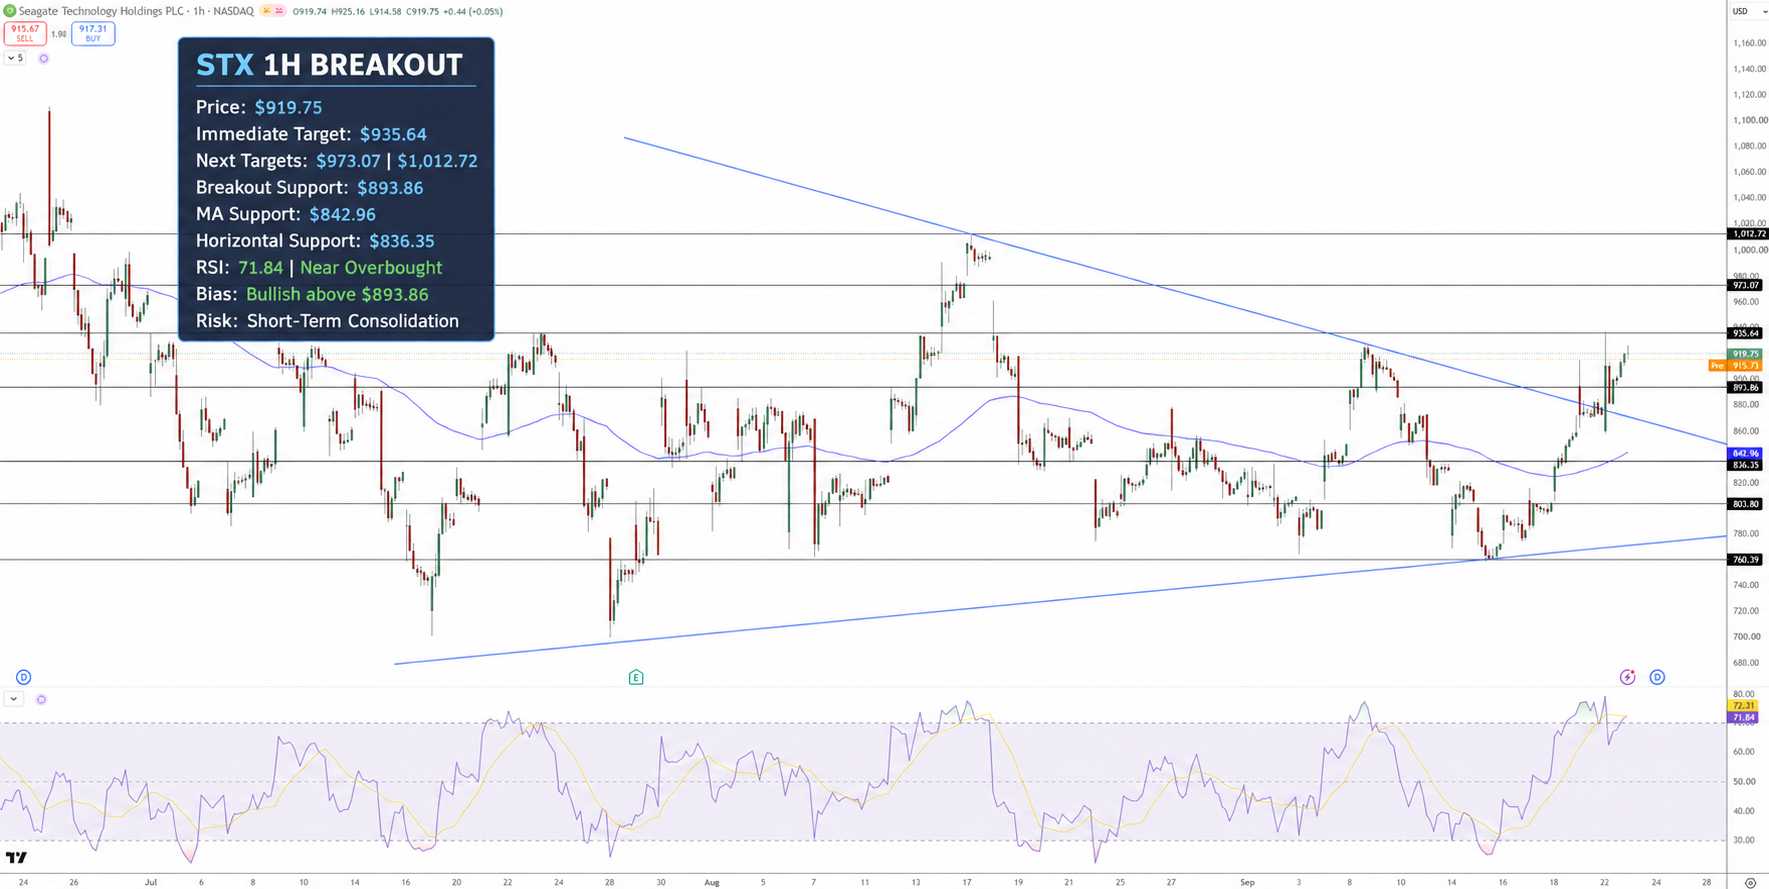
Seagate Price Chart - Source: Tradingview
The Relative Strength Index (RSI) is at 72, which is in overbought territory. A move higher may be limited and a retracement may be in order to setup another move higher.
Current support is at $898.86. A retracement test of this level would confirm it as support. If this level is broken to the downside, the next major support level would be the $842.96 level. This level is also in alignment with the moving average on the chart.
My outlook on the stock remains bullish as long as STX is above $898.86. The upside target is $973.07, with further upside potential at $1,012.72.
The major support and resistance levels for STX are listed on the chart. The RSI is listed on the chart and supports the upside potential of STX. The upside potential is limited, and a retracement or consolidation may be in order.
Why is Seagate stock in focus now?
Seagate's revenues are now 80% data center related. Nearline exabytes shipped were up roughly 40% in fiscal 2026. Also, Mozaic 4+ is in production with two leading hyperscale cloud providers. Add to this, a forecasted sequential revenue increase for the first quarter, and you have plenty of reasons for share price appreciation.
What level confirms a stronger STX breakout?
In the case of Seagate, a breakout is confirmed by a close above $935.64. Should the price move below $898.86, the breakout would no longer be in effect.
Bottom Line
Seagate's products are clearly in demand by data centers. Also, nearline storage and Mozaic 4+ are trending in the right direction. Seagate is currently generating record operating margins. So, the bull case is justified.
What's the worst case scenario? Probably a slump in the AI and data storage demand. Seagate's stock price would probably take a hit if margins started contracting. According to chart analysis, Seagate would have to break below $898.86 for the bear case to take effect.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.