


Intel Stock Holds $98.35 as SK Hynix Talks Put $106.10 Breakout in Focus



AI Podcast


Intel shares rose 4.03% to close at $101.05, driven by preliminary talks with SK Hynix regarding U.S. facility utilization in Ohio and strong Q2 revenue growth. While advanced nodes like 18A and 14A progress and NVIDIA partnerships validate the restructuring strategy, the foundry division still faces operational losses. Valuation has emerged as the primary financial risk, rendering the stock sensitive to negative earnings surprises. Technically, the 4-hour setup remains bullish above the $98.35 support zone, with a decisive breakout above the $106.10 double-top resistance required to target $112.03 and $116.62.
TradingKey - Intel closed September 16 at $101.05, a 4.03% gain from the previous close. According to the supplied chart reference, Intel reached an intraday high of $104.42 on September 16. Intel may test the $106.10 double-top resistance in the near-term given the positive reaction to reports of preliminary SK Hynix talks. SK Hynix is in talks to utilize a portion of Intel’s memory manufacturing facilities in Ohio. Intels’ future is tied to its ability to manufacture chips using advanced processes and to attract external manufacturing customers.
SK Hynix Talks Target Intel Foundry’s Biggest Weakness
The talks may be aimed at leasing a portion of Intel’s Ohio fabrications or forming a joint venture with Intel and large cloud providers.
Intel Foundry reported $5.765 billion in Q2 segment revenue, of which only $293 million came from external customers. With Intels Foundry business improving, manufacturing advanced chips may help fulfill the foundry gap.
Manufacturing a larger share of its own memory may help Intel utilize its manufacturing facilities and ease the financial pressure on its U.S. fabs. A manufacturing relationship with SK Hynix could help Intel improve U.S. fab utilization and reduce financial pressure on the Ohio footprint. For hyperscalers, a more secure domestic source of semiconductors is an added benefit.
Q2 Showed the Operating Turnaround Is Real
Intel posted its best revenue growth in over 15 years during Q2. The $16.13 billion in revenue was a 25% increase from the year prior and non-GAAP EPS of $0.42. Gross margin also improved year over year to 41.8% from 29.7%.
The largest division by revenue, Data Center and AI, grew 59% year over year to $6.26 billion. AI infrastructure is expected to grow substantially and Intel is positioned to take advantage through its CPUs. Increasing demand for AI infrastructure may lessen the reliance on the PC cycle and other areas of the market where Intel has historically experienced cannibalization.
18A Is Now a Real Production Platform
With the introduction of the Intel 18A architecture and the extension of the Xeon 6+ architecture to the server side, Intel has completed the first step to enable the production of high end servers. In addition, with the more than 1 million wafers processed using High-NA EUV across early tool certification/testing, R&D and selected high-volume production layers, including Panther Lake, Intel has gone beyond research and development and started high-volume use of High-NA EUV on selected production layers.
While the progress made by Intel is noteworthy, the foundry is still operating at a loss. Q2 2026 results showed a loss of $2.09 billion by Intel Foundry. Furthermore, next-generation chips based on the Intel 18A architecture will still be expensive to produce.
Therefore, the main objective of the Intel Restructuring plan is to transform Intel from a chip maker to a chip manufacturer for third parties at a profit.
14A Is the Bigger External-Customer Test
Of the two architecture, 14A is more relevant to foundry customers. The main reason is that during the development of 14A, Intel considered foundry customers.
Although other customers may adopt Intel 14A, the main focus has been on developing AI chips. Intel has already claimed that they expect to bring volume production of Intel 14A chips by 2028.
The main challenge for the success of Intel 14A is the number of chip orders placed by foundry customers.
The focus on SK Hynix is Positive
SK Hynix is one of the largest memory chip manufacturers. Intel's focus on SK Hynix is significant as it aligns with the strategy of the Intel Foundry Services division.
SK Hynix will become the first customer of Intel’s foundry services if the two companies enter a production agreement, or if Intel leases chip making equipment to SK Hynix. SK Hynix would become another important external manufacturing customer if the companies reach an agreement; Intel already has external foundry and manufacturing customers.
Nvidia Partnership Adds Strategic Validation
Nvidia’s September 2025 $5 billion investment in Intel and the joint development of data center and client integrated products further supports Intel’s Restructuring plan.
This positions Intel in an advantageous spot in the AI ecosystem by eliminating cutthroat competition with other companies in multiple tiers of the industry.
Valuation Is Now the Main Financial Risk
Prior risks focused on the capital structure and liquidity. Today, the main financial risk is valuation. Since the SP is now above $100, Intel is no longer a distressed security, and many positive assumptions are being made about the company's potential.
Of course, there is now a greater risk of losses if the company fails to meet the expectations that are now built into the valuation.
Valuation sensitivity means that an unpleasant surprise, such as a further decline in gross margins or a loss of 14A customer awards, would be quickly reflected in the stock price, unlike at the lower prices in the $20-30 range.
This is why the Q3 report, especially the level of DCAI and gross margins, as well as other negative surprises, is important for Intel. Further, any news regarding customer awards or Foundry losses should be constructive.
Intel Technical Analysis: $106.10 Remains the Decisive Breakout Level
Intel Corp. (NASDAQ:INTC) ended yesterday’s session at $101.05, after another session below the $106.10 double-top resistance area. The 4-hour setup remains bullish, as price is above the support zone at $98.35, which is confluent with a moving average at $98.56.
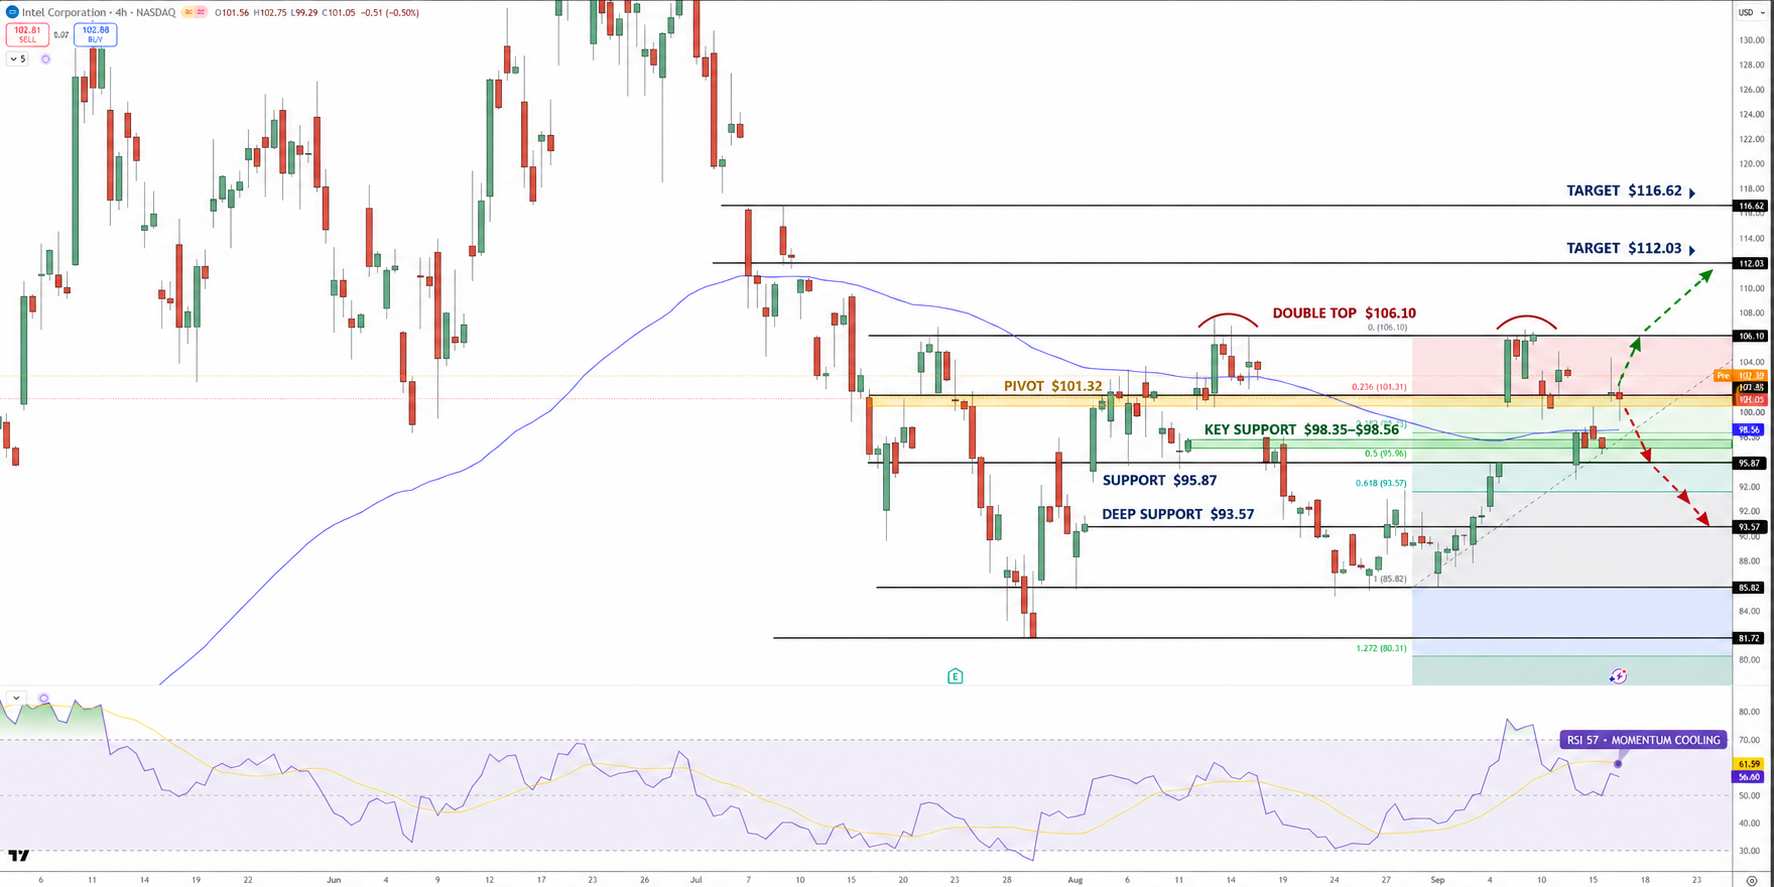
Intel Stock Price Chart - Source: Tradingview
The Relative Strength Index (RSI) at 57, hints the bullish momentum has decreased; however, it is still above the 50-neutral level.
If the bulls keep up the pressure, the price should target the double top resistance zone at $106.10. Clearing this barrier would suggest that the double top formation is invalid, and open the way to the next resistance levels at $112.03 and $116.62.
If the buyers are unable to break and hold above $106.10, price should find support between $98.35 and $98.56. Loss of the $98.56 support would allow the sellers to extend to the downside and target the next support zones at $95.96 and $95.87. From there, the support level aligns with the 61.8% Fibonacci retracement level at $93.57.
Key Levels
· Latest completed close: $101.05
· Immediate pivot: $101.32
· Key support: 98.35-98.56
· Secondary support: 95.96-95.87
· Deeper support: $93.57
· Breakout resistance: $106.10
· First upside target: $112.03
· Higher target: $116.62
· RSI: Around 57, constructive but cooling
Intel surged after SK Hynix was reported to be considering U.S. memory-chip fabrications with Intel, using the Ohio facility. At this point, Intel and SK Hynix have only preliminary talks. Still, these talks are relevant to the Intel Foundry theory because they show efforts to get more customers to use Intel’s U.S. fabrication units.
Why is Intel stock in focus now?
Intel rose 4.03% after reports that SK Hynix is exploring U.S. memory-chip manufacturing with Intel, potentially using the Ohio complex. The talks are preliminary, but they address one of the biggest issues in the Intel Foundry thesis: bringing more external utilization into expensive U.S. fabs.
What level confirms further INTC upside?
The double-top setup suggests that should Intel sustain a close above $106.10, additional upside would be target $112.03. A break below $98.35 would strengthen the bearish double-top risk and shift focus toward $95.87 and then $93.57.
Bottom Line
Compared to last year, Intel’s September 17th options setup has improved. Additionally, more catalysts point to the positive for Intel. Some of these includes the positive DCAI and NVIDA related catalysts, as well as progress on the 14A and 18A chips. Given all of this, and the recent SK Hynix news, Intel options remain somewhat bullish, but $98.35 should provide a good floor. While this is the case, a close above $106.10 would provide an even better target, around $112.03. A break above $106.10 would strengthen the bullish case, while a break below $98.35 would shift the setup bearish toward $95.87 and $93.57.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.