


NVIDIA Stock Loses Trendline as AI-Safety Debate Puts $216 Support in Focus



AI Podcast


NVIDIA’s fiscal Q2 2027 revenue surged 106% year-over-year to $96.22 billion, driven by robust Data Center demand and upcoming Vera Rubin production. Despite stellar growth and strong Q3 guidance, the risk profile is shifting. Rising advanced memory costs are expected to pressure gross margins down to 71%-72% in Q4, while supply commitments escalated to $279 billion. Geopolitical headwinds from China and emerging AI-safety debates present sentiment risks. Technically, the stock trades below its uptrend line, with the $214.50–$216.26 zone serving as critical support, while a decisive hourly close above $222.12 is required to confirm a short-term recovery.
TradingKey - NVIDIA closed September 11 at $218.29, almost exactly matching the $218.21 chart reference. The stock has slid below its uptrend line after failing to hold above $222.12. The $216.26-$214.50 support zone will be the focus of the next move. The fundamentals of the business remain very strong, but the risk profile is changing. Its Vera Rubin platform is already ramping into full production. AWS plans to deploy 2 million additional NVIDIA GPUs across 2027 and 2028. Additionally, Q3 guidance throws another major revenue step-up into the mix. All of these factors are positively influencing NVIDIA, but there are counter currents. Memory pricing is eroding margins, China is absent from the current Data Center demand, and the ongoing AI safety debate is evidently negative for the sector.
Q2 Growth Remains Extraordinary
For fiscal Q2 2027, NVIDIA hit approximately $96.22 billion in revenue with 106% year over year growth and 18% sequential growth. During this period, Data Center revenue was $89.0 billion and an increase of 117% compared to the prior year. GAAP operating income was $63.73 billion with GAAP net income of $59.69 billion. Gross margin was at an impressive 75.0% for the quarter. NVIDIA returned roughly $26 billion to shareholders and ended the quarter with about $99.3 billion of buyback authorization.
The true value is in scale. Triple digit growth from a $100 billion revenue run rate is simply unprecedented, even during this current AI period.
Q3 Guidance and FY2028 Outlook Keep the Demand Story Intact
NVIDIA is projecting $108 billion of revenue for the fiscal third quarter with plus or minus 2% variation. This would represent a 12% increase from the preceding quarter. For the forthcoming fiscal year, fiscal 2028, NVIDIA sees revenue growing by approximately 70% from the prior fiscal year.
NVIDIA still considers the business as supply constrained, so the current bull case argument for NVIDIA is strong demand exists with supply constraints rather than just strong demand.
NVIDIA’s fiscal third quarter guidance is setting expectations for zero Data Center compute revenue from China. While this represents a real geopolitical concern, it is indicating that NVIDIA is targets for revenue growth that do not rely on a recovery of China.
Vera Rubin Is Already Entering Production
Vera Rubin is already ramping into full production. NVIDIA is estimating Rubin will account for approximately 20% of Data Center revenue in fiscal Q3, with Rubin supply continuing to improve over time into Q4 and fiscal 2028.
This significantly reduces the risk of semiconductor customers holding sales while waiting for the next architecture. Hyperscalers continue to buy AI compute because demand is growing faster than the annual platform transitions.
Rubin will be a major focus of production while NVIDIA must manage the demand for Blackwell Ultra, networking and memory supply, and system level delivery.
AWS Adds Another 2 Million GPUs
AWS plans to deploy 2 million additional NVIDIA GPUs across its global infrastructure in 2027 and 2028. With an expanded partnership, AWS will also offer Vera CPUs, advanced networking, Nemotron models, secure government AI infrastructure, and robotics.
This partnership demonstrates NVIDIA’s stack is extending beyond GPUs and is now weighing as a complete AI-Factory stack. Customers are now buying integrated offerings of compute, CPUs, networking, interconnects, and models as a single integrated system.
This makes competitive disruption harder than designing a faster GPU.
Margins Are the Biggest New Financial Risk
Having said that, the greatest financial concern is no longer demand, it is gross margins.
NVIDIA’s management expects that Q3 gross margins will land at around 74%. Advanced memory costs are rising fast and NVIDIA’s management has warned that they will continue to pressure gross margins into next year. Management expects gross margin to bottom around 71%-72% in Q4 before settling around 72%-73% in fiscal 2028.
This means NVIDIA can sustain large double-digit revenue growth at the cost of a falling gross margin. For the upcoming earnings call, gross margins and the pace of Rubin adoption will be the two most important metrics.
Supply Commitments Are Rising Rapidly
NVIDIA has also substantially increased their supply and capacity commitments to $279 billion from $119 billion in the prior quarter, primarily to secure memory and manufacturing capacity for their projected demand.
This strategy relies on aggressive growth plans that likely increase capital intensity and increase risk. If there is a slowdown in AI spending, NVIDIA may be in a position of having more inventories and commitments than investors typically see for a fabless chip company.
The company’s strong profits mean they have a lot of capacity to take on the risk, but the exposure on the balance sheet to the broader AI buildout is definitely increasing.
Today’s AI-Safety Debate Is a Sentiment Risk
The newest market disruptor is the global AI-safety debate. On September 14 Asian stocks fell after Anthropic CEO Dario Amodei pushed for a cautious approach to frontier-AI development. While some of Amodei’s points resonated, OpenAI CEO Sam Altman and Elon Musk supported parts of Amodei’s framework.
While the swiftness of the development has more of an impact on valuation and sentiment than on current demand, the impact on NVIDIA is still negligible for the time being. There may be a decreased need for marginal training demand as the race toward larger frontier models slows down. However, there may be greater model deployment and increased inference and data center demand.
The AI-related safety debate may not be as negative as a bearish, demand shock-related impact. According to NVIDIA’s Q2 report and the AWS expansion, there has been no major slowdown in the demand for AI-related cloud infrastructure.
NVIDIA Technical Analysis: $214.50-$216.26 Is the Key Support Zone
NVDA closed at $218.29 on September 11, right on the chart’s support level of $218.21. The 1 hour structure was bearish after the price beam slipped below the rising trendline and was unable to recover above $222.12.
The focus for the next few hours will be the $216.26-$214.50 level. The RSI is around 37 which is above the 30 oversold level. This means that the market is in a weak state and has not confirmed a reversal.
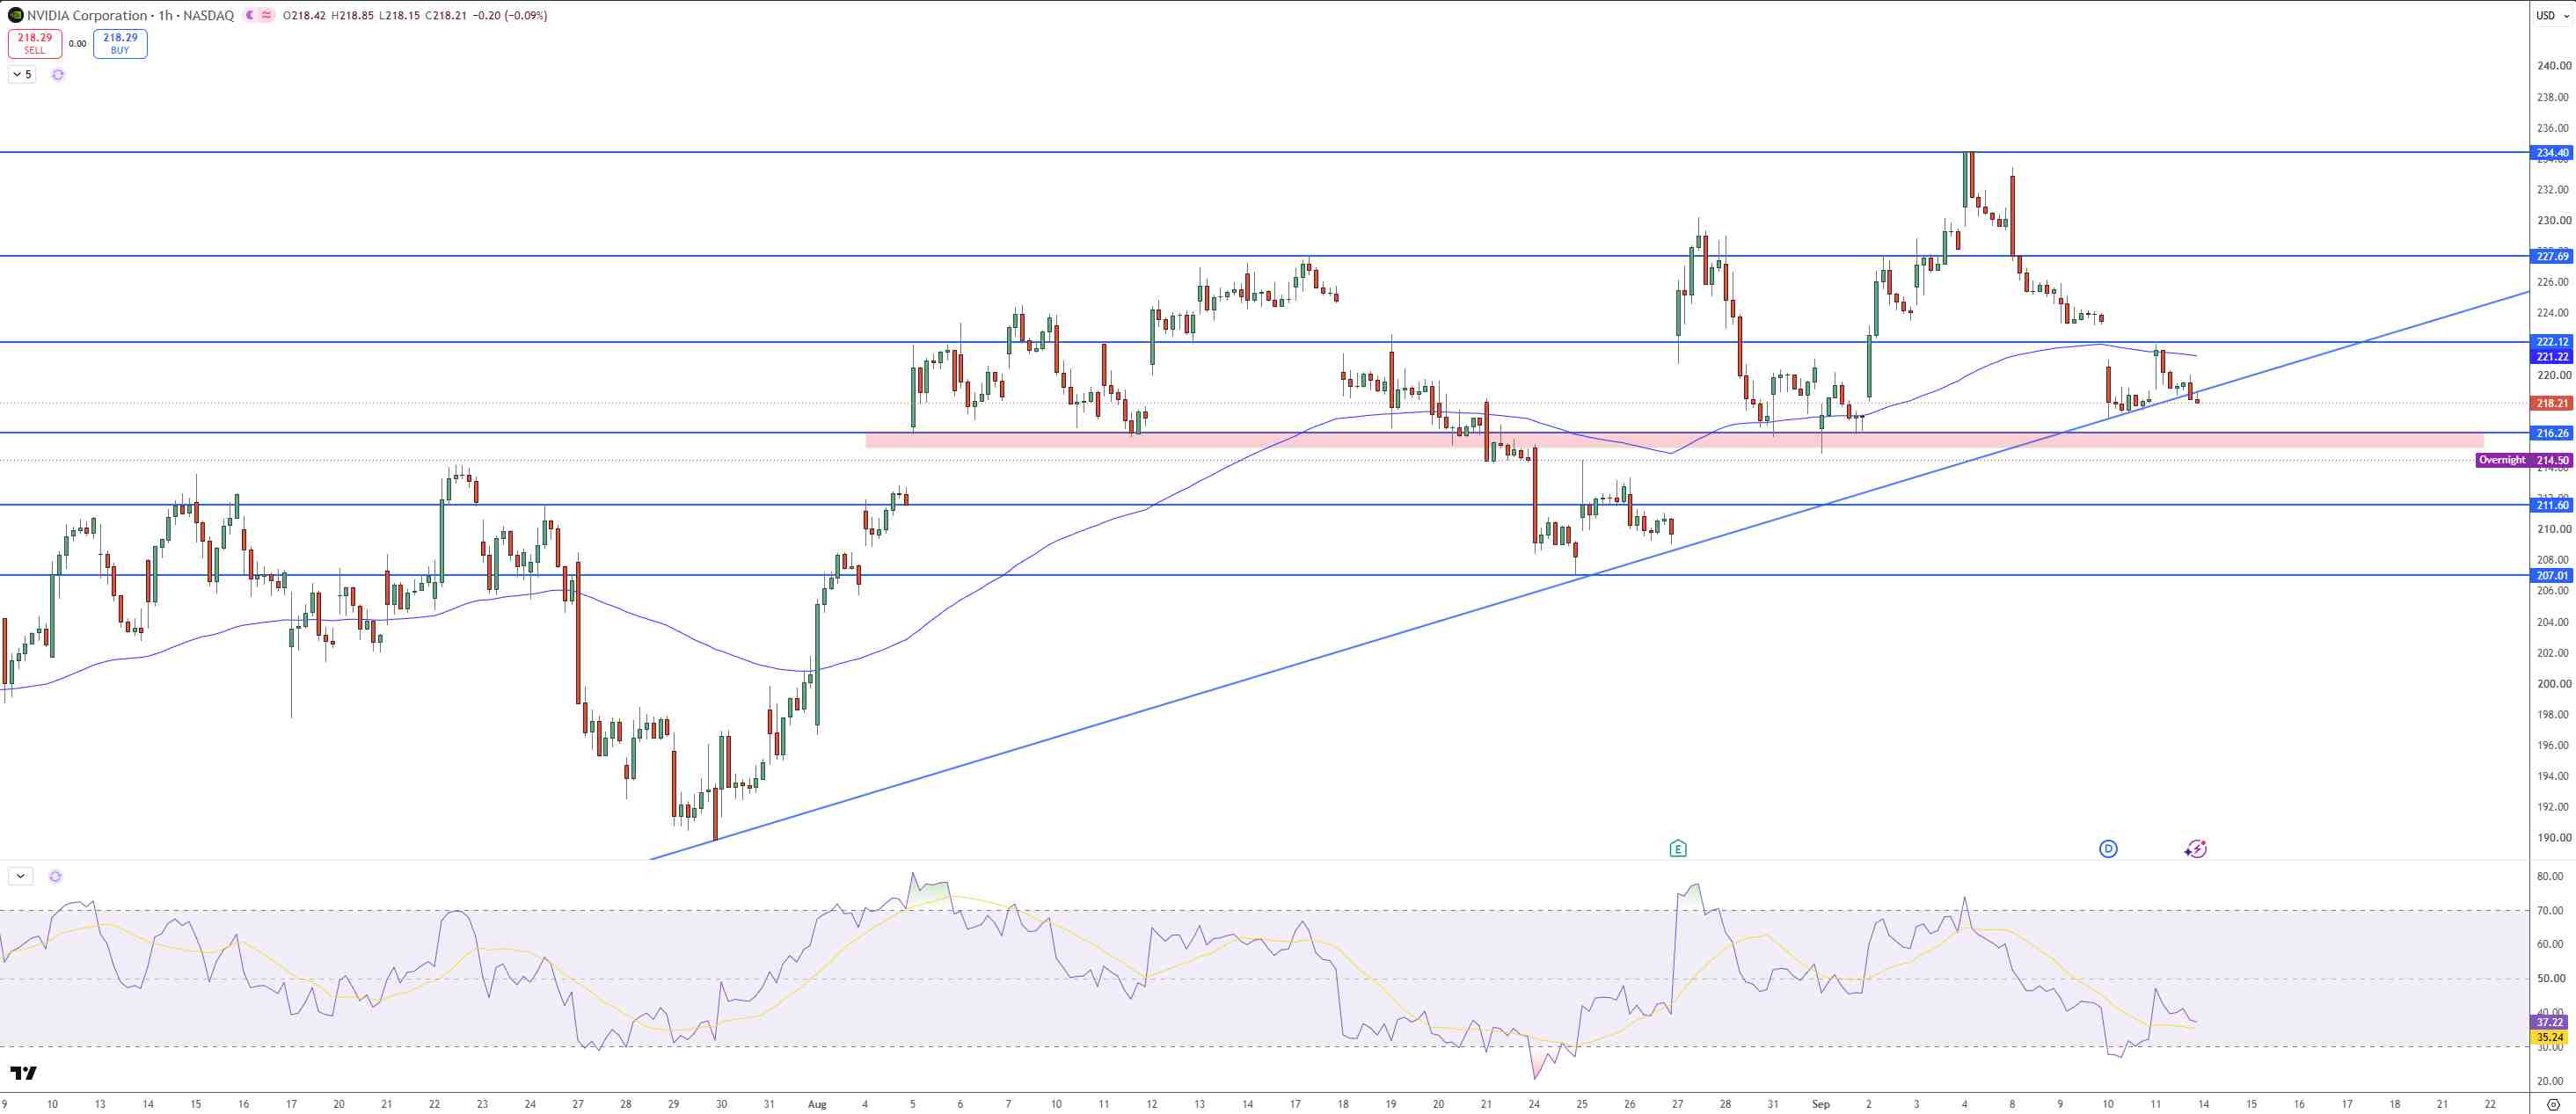
NVIDIA Stock Price Chart - Source: Tradingview
$216.26-$214.50 could provide a favorable trading level as NVDA would then trade in the zone $221.22-$222.12. A favorable trading range would be an hourly closing price above $222.12. This would then open the trading ranges of $227.69, $234.40 and $236.58 as an additional higher resistance from the supplied chart respectively.
If the support zone of $214.50-$216.26 breaks, it will expose the trading range of $211.60. If that breaks support, $207.01 will be the next trading range.
Key Levels
· Latest completed close: $218.29
· Key support zone: $216.26-$214.50
· Recovery resistance: $221.22-$222.12
· First upside target: $227.69
· Higher target: $234.40
· Breakdown level: $214.50
· First downside target: $211.60
· Deeper support: $207.01
· RSI: Around 37, weak but not yet oversold
Why is NVIDIA stock in focus now?
NVIDIA is one of the most compelling fundamental stock stories in international markets. However, recently, the market has become more concerned with margin pressure, supply assurances, export from China, the absence of the Chinese market, and AI-related regulations as opposed to the existence of demand. AI concerns and the AI safety debate imply a new sentiment risk.
What level confirms an NVDA recovery?
A recovery would be confirmed at $222.12 in the hourly time frame, as a break above this level improves short-term structure making the targets $227.69 and $234.40 possible. A sustained hourly close above $222.12 is the cleaner confirmation signal. If the level of support at $214.50 is broken, the level at $211.60 becomes the new target, along with $207.01.
Bottom Line
NVIDIA’s momentum in Q2 was a staggering 106% growth, Data Center was 117%, Vera Rubin is already ramping, and AWS plans to add 2 million additional GPUs, adding further evidence of demand. The risk is now more concentrated on margins and AI, China’s regulatory focus, and the size of NVIDIA’s commitments. I remain cautiously bearish while NVDA stays below $222.12, with $214.50-$216.26 acting as the key support zone. The zone offers rebound potential, but to improve momentum, bulls would need to reclaim $222.12 and aim for $227.69 and $234.40.
Recommended Articles






Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.