


Kospi Surges 2.6%, Nikkei 225 Gains 1.3%; Kioxia and SK Hynix Jump Over 5% While SoftBank Bucks Trend to Fall



AI Podcast


During the Asian trading session on November 11, Japanese and South Korean equity markets surged, with the KOSPI Index jumping 2.6% to 5,375.36 and the Nikkei 225 gaining 1.31% to 61,248.52. Semiconductor stocks rallied strongly, driven by South Korea's data showing a 331.2% year-on-year surge in November 1–10 semiconductor exports, confirming robust global AI and HBM demand. Meanwhile, easing US-Iran tensions and lower crude oil prices alleviated inflation fears and supported energy-reliant economies, easing bond yield pressures and boosting regional market sentiment.

TradingKey - KOSPI surges 2.6%, Nikkei breaches 61,000 mark, SK Hynix jumps 5.3%.
During the Asian trading session on November 11, Japanese and South Korean equity markets posted a strong close, trending higher amid volatility and extending their upward rebound. The KOSPI Index closed up 2.6% at 5,375.36 points, completely erasing early-session technical profit-taking pressure from a lower open; Samsung Electronics rose 3.44% to reclaim the 200,000-won mark, closing at 205,800 won; SK Hynix surged 5.36% to 1,277,000 won.
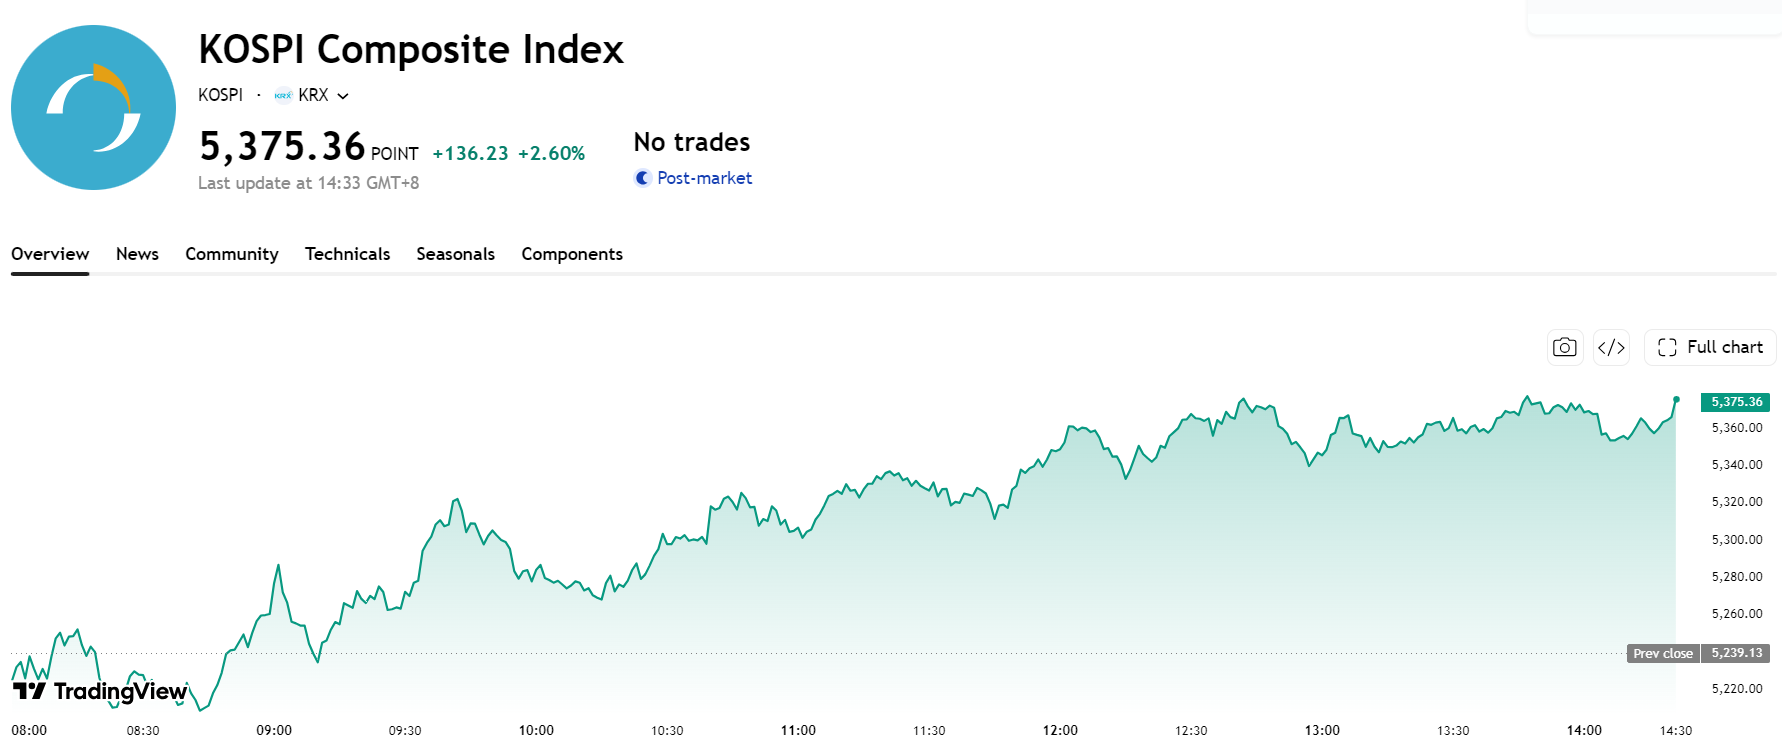 KOSPI Index chart, Source: TradingView
The Nikkei 225 Index gained 1.31% to close at 61,248.52 points; Kioxia fluctuated at elevated levels throughout the session, ending up 5.55% to reclaim the 9,000-yen level and close at 9,571 yen; SoftBank fell 0.44% to 3,855 yen.
South Korea's customs agency released export data for November 1–10, showing semiconductor export value surged 331.2% year-on-year. This directly confirmed to global capital markets that, even amid political and economic volatility, real demand for global AI computing power and high-bandwidth memory (HBM) remains exceptionally robust, dispelling market concerns that AI growth has peaked.
In addition, substantive signs of de-escalation emerged from US-Iran negotiations, and international crude oil prices softened, substantially easing global market alarms over a second wave of inflation. This not only contained concerns over bond market yields spiraling out of control, but also gave East Asian economies heavily reliant on energy imports, such as Japan and South Korea, significant room for margin recovery.
This content was translated using AI and reviewed for clarity. It is for informational purposes only.
Recommended Articles










Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.