


Dollar Index Hits Near 19-Month High Above 103 as Fed Rate Hike Bets Heat Up, USD/JPY Nears 160



AI Podcast


On November 12, the US Dollar Index reached a 19-month high of 103.08, driven by higher-than-expected October CPI data and hawkish Federal Reserve signals. Major non-US currencies, including the euro, British pound, and Japanese yen, faced broad downward pressure. The market-implied probability of a December rate hike rose to 90.8%, with institutions like Goldman Sachs adjusting their tightening outlooks. Sustained dollar strength depends on holding the 103 level, upcoming PPI data, and Fed commentary. Key risks include potential shifts in rate hike expectations and subsequent economic data releases.

TradingKey - On November 12, the US Dollar Index extended its recent upward trend during Asian trading hours, briefly breaking through the 103 mark intraday to reach a high of 103.08, hitting a near-19-month high since April 2025. With US October inflation data coming in higher than market expectations and Federal Reserve officials continuously delivering hawkish signals recently, the market further raised expectations for a December rate hike, lending support to the sustained strength of the US dollar.
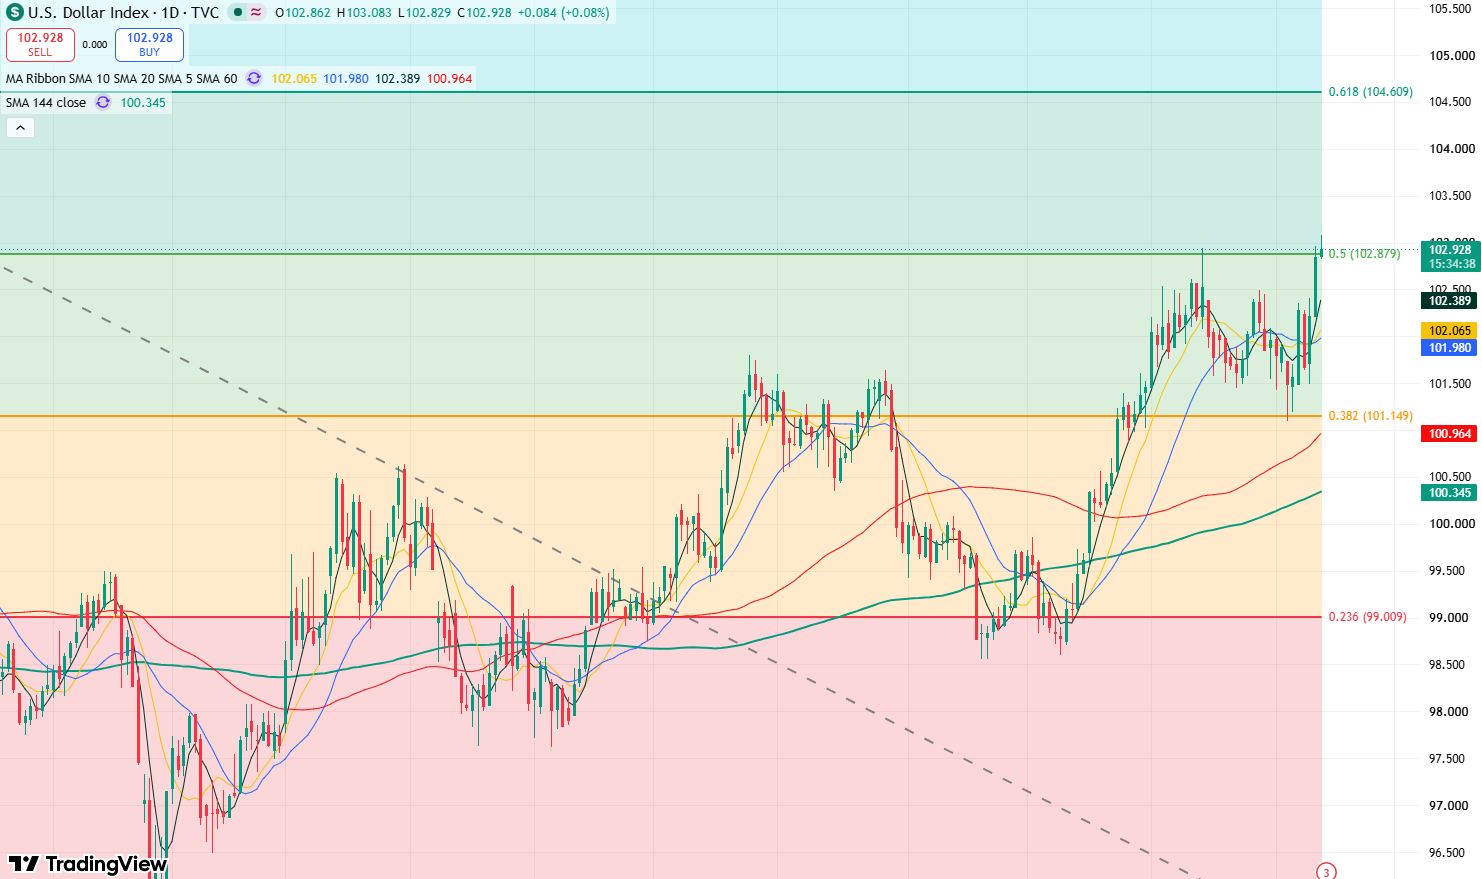
US Dollar Index daily chart, source: TradingView
As of press time, major non-US currencies were broadly under pressure. The euro fell about 0.08% against the US dollar to $1.1080, hitting a new low since May 2025; the British pound dropped about 0.16% against the US dollar to $1.3259. The US dollar against the Japanese yen (USDJPY) climbed to a more than two-month high intraday, reaching as high as 159.95 and approaching the key psychological level of 160.
Higher-than-expected US inflation has been an important driver behind this round of dollar gains. Data released by the US Bureau of Labor Statistics showed that the October Consumer Price Index (CPI) rose 0.4% month-over-month, higher than the market expectation of 0.3%; the core CPI, which excludes food and energy, rose 0.3% month-over-month, also exceeding the expected 0.2%. Persistent inflationary pressures have prompted investors to reassess the Federal Reserve's future interest rate path.
Meanwhile, Federal Reserve officials have recently sent clearer tightening signals. Fed Governor Waller stated that even if inflation eases somewhat, he still supports a 25-basis-point rate hike in December; if core inflation worsens further, a 50-basis-point rate hike should be considered in one go. According to the CME FedWatch Tool, the market-implied probability of a 25-basis-point rate hike by the Fed in December has risen to 90.8%, significantly higher than the 70% seen a month ago.
Some Wall Street institutions have also raised their expectations for future rate hikes. Among them, Goldman Sachs expects the Federal Reserve to raise rates in December this year and March next year, respectively, while Deutsche Bank anticipates that rate hikes could occur in December, January next year, and March.
In the short term, whether it can hold firmly above the 103 level will be a crucial condition for the US Dollar Index to sustain its upward momentum. Looking ahead, the market will closely monitor remarks by New York Fed President Williams, Friday's upcoming release of October PPI data, and the impact of subsequent US economic data on rate hike expectations. If the Federal Reserve continues to send hawkish signals, the US dollar may remain strong; conversely, if the market scales back rate hike expectations, the US Dollar Index may face pullback pressure.
This content was translated using AI and reviewed for clarity. It is for informational purposes only.
Recommended Articles











Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.