


Q1 Turnaround! Is APP's Core Gaming Biz. Still Solid?


$AppLovin(APP.US) delivered a 'clean comeback' in Q3, aided by cautious positioning ahead of the print and a meaningful beat. Growth re-accelerated modestly after a prior slowdown.
Key points are below. They highlight the drivers of the upside surprise.
1. Growth back to acceleration
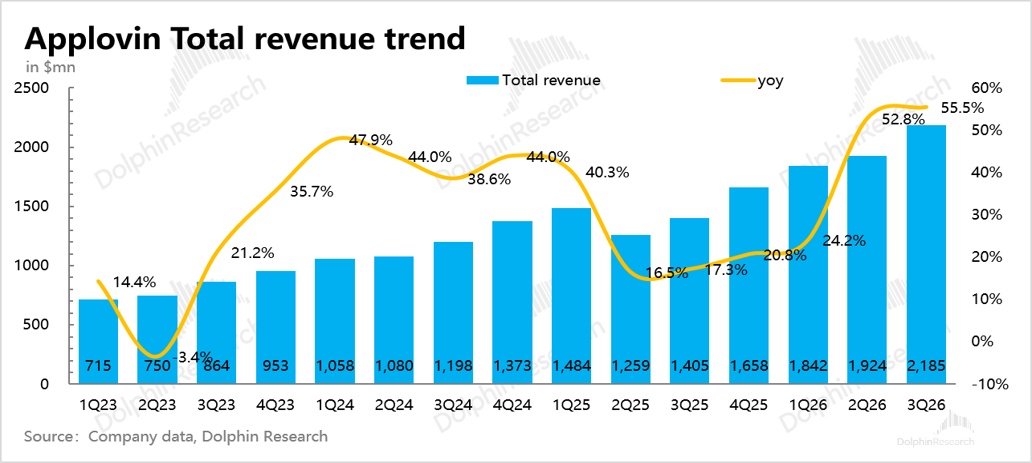
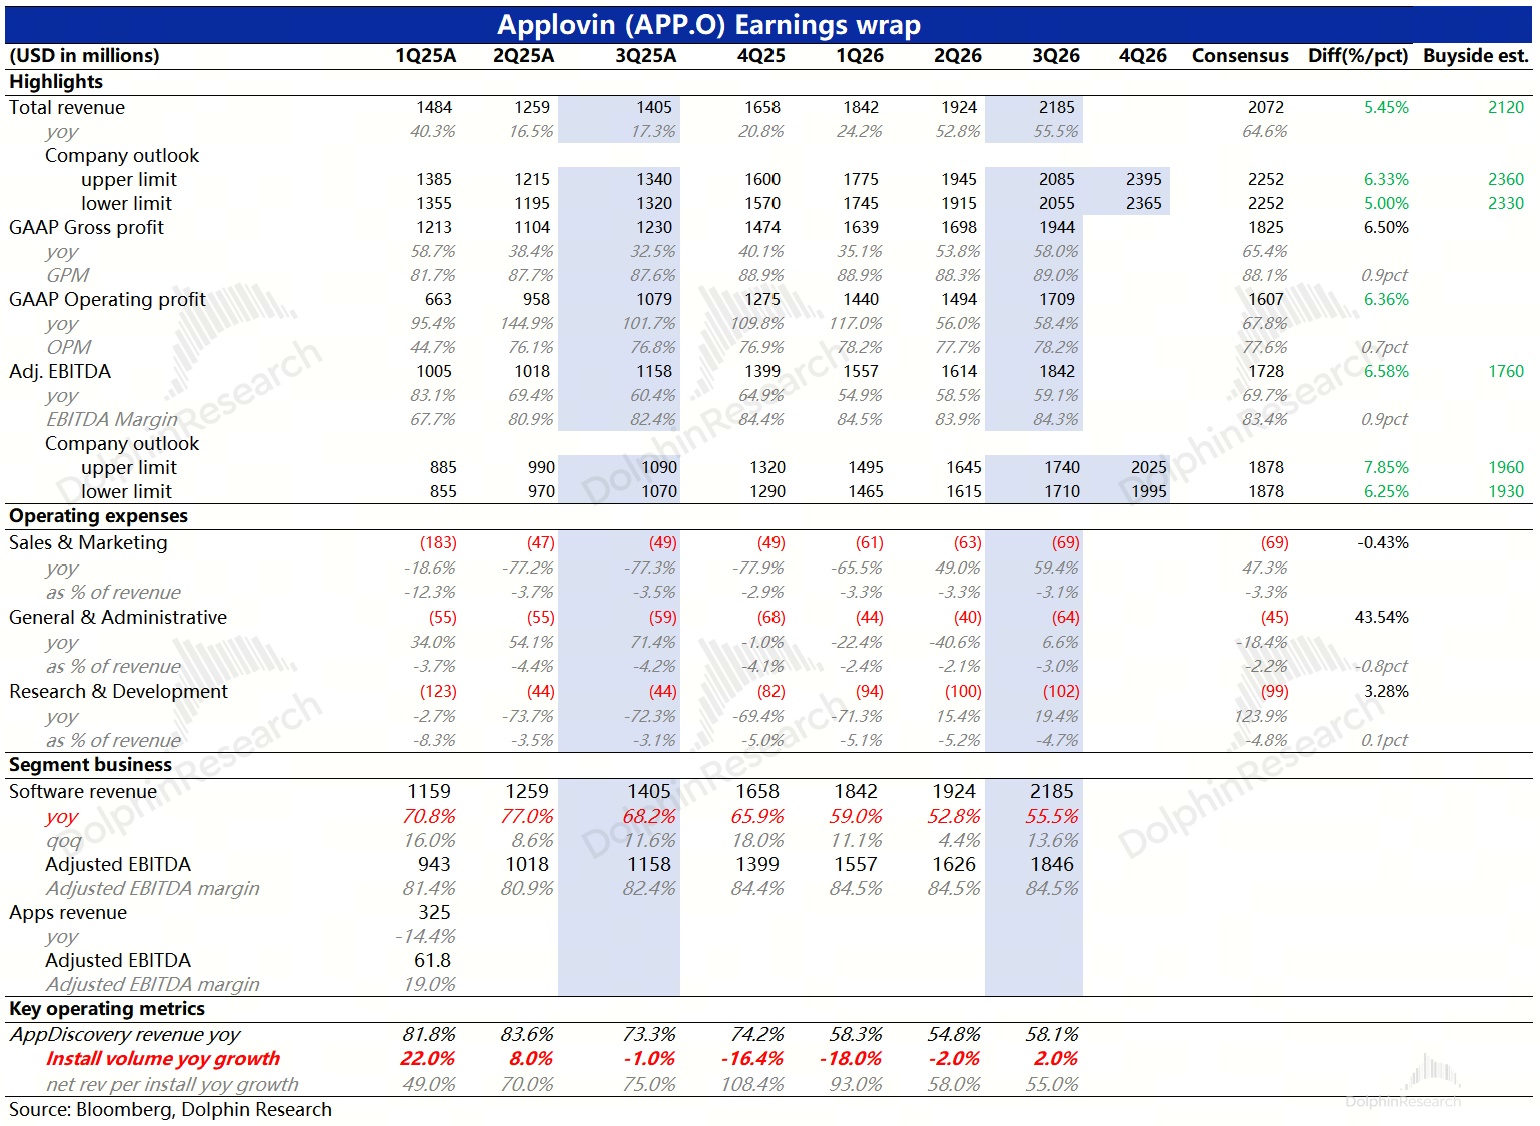
Q3 revenue was $2.2bn, up 13.6% QoQ, a sharp pickup vs. last quarter and back into APP's familiar growth band. The print topped both buy- and sell-side estimates.
Q4 guidance implies growth decelerating to 45% on a high base, yet still above the market’s prior ~36% view. This reset lifts near-term expectations.
2. Game ads are warming up
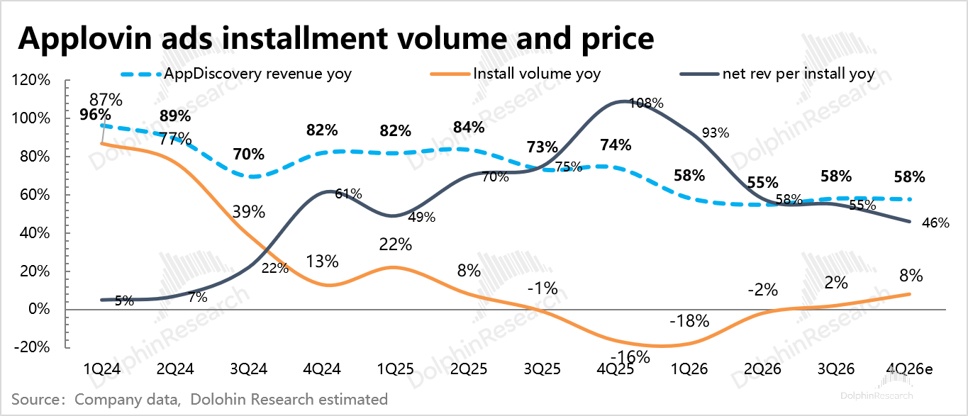
App installs returned to positive growth in Q3 at +2% YoY, while revenue per install rose 55%. Although pricing growth slowed QoQ, it remained elevated.
Combining volume and price implies app download ads (mostly game ads) grew 58%, a slight acceleration vs. Q2. This supports a sustained recovery in the core ad engine.
Based on Q4 guidance, Dolphin Research estimates the Q4 volume/price mix will mirror Q3, with installs rising but unit pricing growth easing. Forecasts are for reference only.
Pre-earnings channel checks pointed to share losses in game ads for APP due to higher quoted prices and competitors expanding penetration. Some clients tested budgets on rival platforms, while July model upgrades did not show a marked ROAS lift.
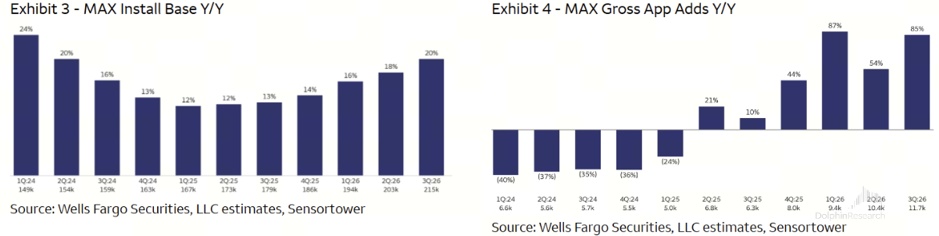
Given ongoing litigation overhang, funds stayed cautious and feared a repeat of the Q2 'bomb'. Even alternative data showing Max downloads accelerating through Q3 did not fully ease worries.
The reality: after APP rolled out the model, advertisers resumed spend. Sector growth in app ads, driven by higher AI Overview penetration that pushed budgets from web to app, offset APP’s share slippage.
As a result, headline revenue growth re-accelerated and beat the Street. This challenged concerns around U’s and META’s comeback.
3. E-comm ads still early
The company did not disclose e-comm ad revenue, suggesting the base remains small. Institutional checks indicate progress has lagged earlier expectations with middling conversion efficiency.
Dolphin assumes that if games grew ~48–50% YoY and e-comm net revenue roughly doubled, then Q3 e-comm revenue was about $310mn–$410mn. That would be 14–19% of total revenue.
With AI Agents eroding platform entry points, e-comm platforms may step up paid traffic. Whether APP can capitalize, especially by improving conversion efficiency, warrants monitoring.
4. Margin modestly repaired
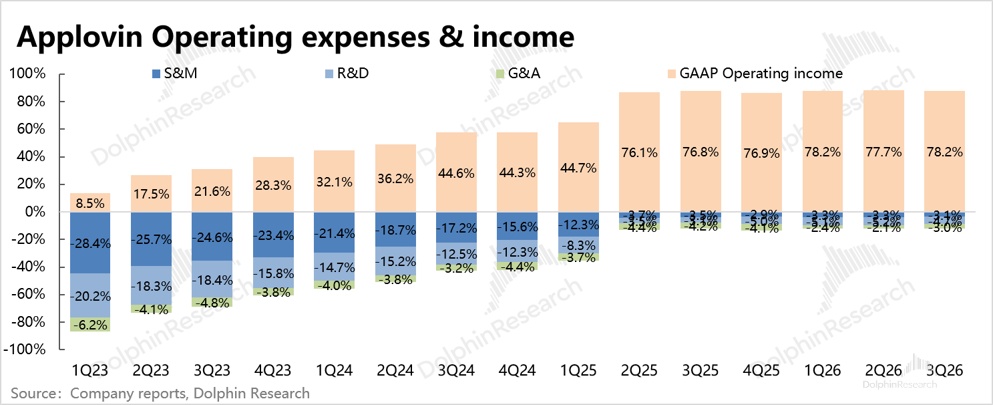
On opex, marketing and R&D were both up significantly YoY in Q3. Sales expense reflects opening the Axon self-serve platform to e-comm advertisers and customer acquisition initiatives.
Most of the R&D delta was from SBC vesting, including a PSU grant of 0.92mn shares to key non-exec IT engineers that vests upon market-cap triggers, amortized quarterly over an estimated two years. Ex-SBC, R&D grew 19% YoY.
QoQ, G&A rose by nearly $20mn, disclosed as professional services. Dolphin suspects links to the Sept. securities lawsuit and allegations that U collected APP’s ad-tracking data.
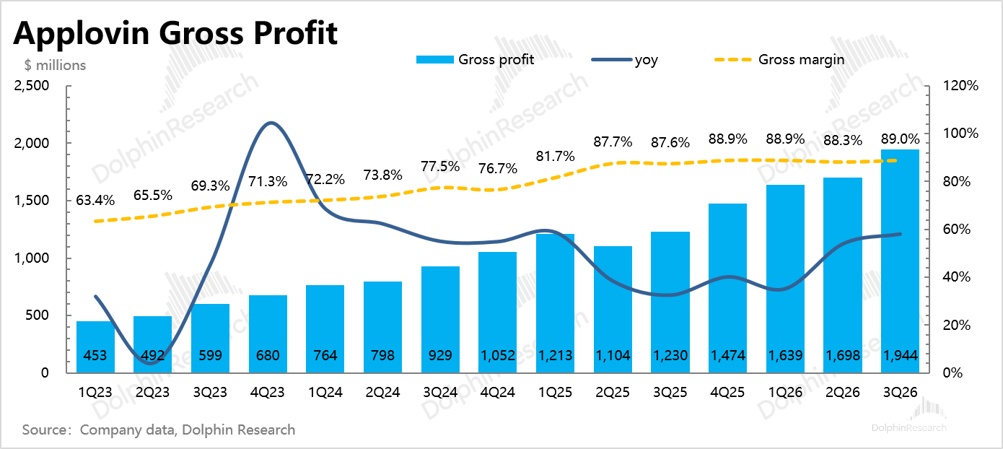
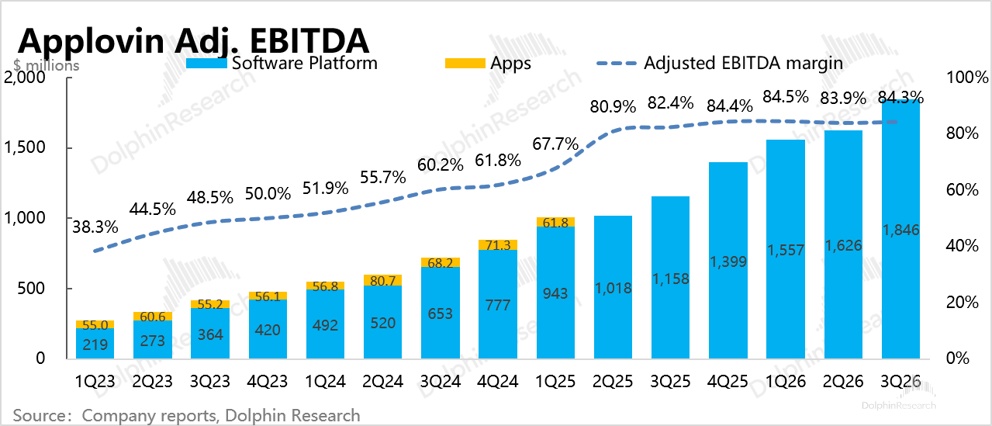
Strong revenue offset higher opex, lifting GAAP OPM by 50bps QoQ. Ex-SBC, Adj. EBITDA margin recovered to 84% in Q3.
Guidance implies Q4 margins holding flat QoQ. This suggests disciplined reinvestment alongside topline momentum.
5. Buybacks at full throttle
In Q3, APP repurchased $1.4bn at an Avg. price of $339/share, 2.5x last quarter. This essentially consumed Q3 FCF.
The BOD added another $3.2bn authorization, taking total to $3.6bn by end-Oct, about 3% of post-market cap. Liquidity remains ample for continued buybacks.
With $3.2bn cash on hand and roughly $1.5bn FCF per quarter, $1.0bn repurchases per quarter look manageable. The $3.6bn program could be used within 3–4 quarters.
If renewed thereafter and paced at $4.0bn over the next year, that would be 4.4% of yesterday’s $90.9bn market cap. Capital returns are set to stay a meaningful lever.
6. Key metrics at a glance
Dolphin Research view
Last quarter’s 'bomb' reflected model-iteration timing. Despite what we saw as an overcorrection, the market kept probing lower all quarter, pricing in a broken core and a trend peak.
The biggest Q3 surprise is that it eased fears around APP’s backbone — mobile game ads — effectively setting a valuation floor. This was critical for sentiment repair.
While share has indeed tightened, with U only a year into market re-entry and META returning with AI tailwinds, APP’s long-standing ROAS-driven leadership suggests the tech moat is not easy to crack. The competitive bar remains high.
That said, pricing gains appear near a peak, shifting the next leg to volume growth. This likely means more direct competition with strengthening rivals.
Perhaps in response to this pressure, APP has sued U, alleging unauthorized collection of its ad-tracking data. Legal outcomes bear watching.
Game ads are the base, but e-comm ads are key to whether APP can scale meaningfully. External checks show mixed progress: early growth came largely from test budgets.
As tests underperform on conversion, advertisers’ willingness to commit formal budgets is affected. Execution on conversion efficiency will be the swing factor.
On the call, management gave limited quantification for e-comm revenue. They cited double-digit QoQ and triple-digit YoY growth and hinted that e-comm contribution has become noticeable.
Combining pre-earnings institutional expectations, we rough out Q3 e-comm at $300–400mn, roughly doubling YoY. Assuming next year grows at a 5% QoQ annualized pace, revenue could reach $1.8bn.
With game ads growing 20–30% YoY, total revenue could be around $11.0bn. Using a 75% OPM (slightly lower YoY on higher e-comm mix), 15% effective tax, and 15x–20x GAAP P/E, fair value is $105–140bn.
Post-market rally to $110bn sits near the low end of that range. Much of the 'oversold' gap is now closed.
We see 10–20% theoretical upside from here, but chasing now offers limited risk-reward. Better to avoid the crowd and wait for sentiment to cool.
Dolphin Research on 'AppLovin' (history):
Aug 6, 2026 earnings take: 'AppLovin: A top student stumbles — can the e-comm dream live on?'
May 7, 2026 earnings take: 'AppLovin: Still a sweetheart, but has capital moved on?'
Feb 12, 2026 earnings take: 'AppLovin: Haunted by ghosts — even strong results can’t hold?'
Jan 20, 2026 short report take: 'AppLovin: Shorts kick off the year — how strong is the firepower this time?'
Jan 3, 2025 Init. Coverage (Part I): ''Feel-good' AppLovin Unmasked: A five-year, premeditated win'
Risk disclosure and disclaimer: Dolphin Research Disclaimer and General Disclosure
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.