


Circle: Inflated results, distributor pushback; scaling the ecosystem is the only way out


$Circle(CRCL.US) released Q3 results pre-mkt on Nov 4 ET. The 'beat' was driven mainly by Arc token sales, while underlying performance was middling once that is stripped out. This aligns with pre-earnings concerns in the tape.
Details follow. Key points are below.
1、储备利息收入预期内下降
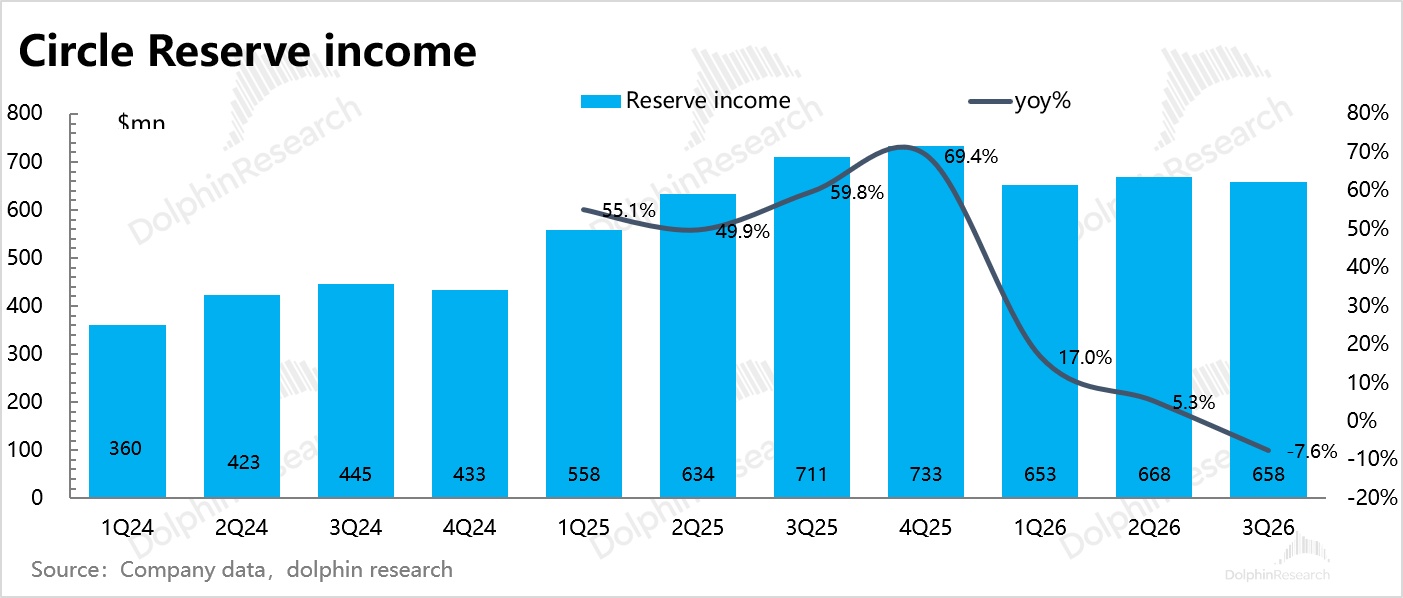
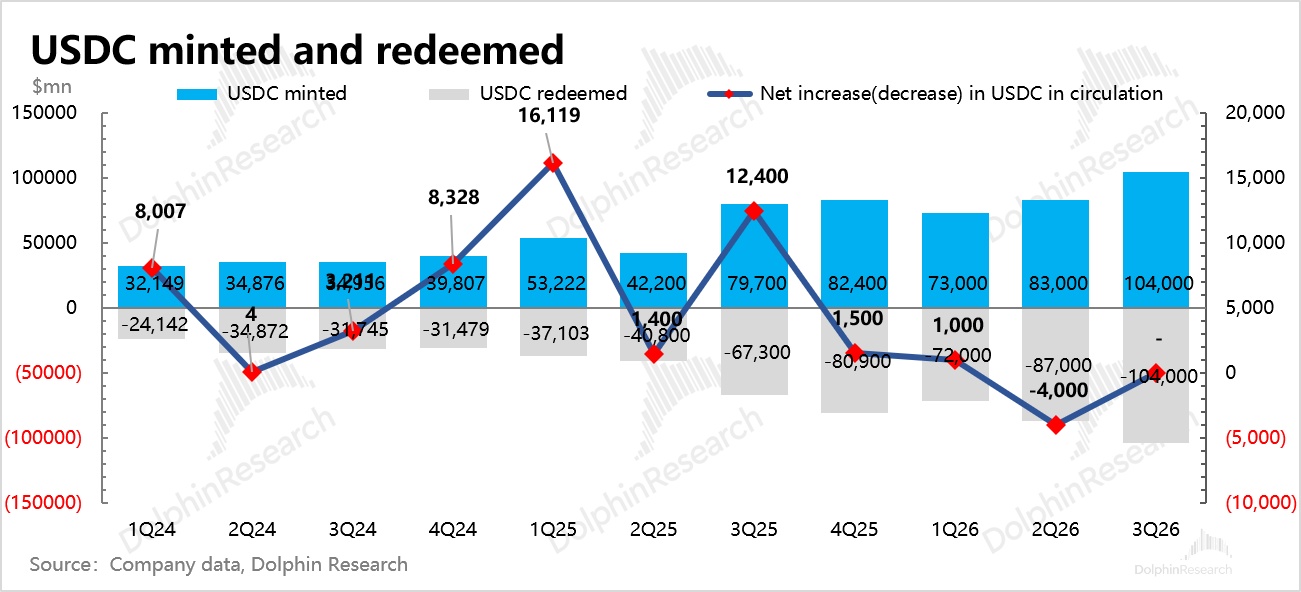
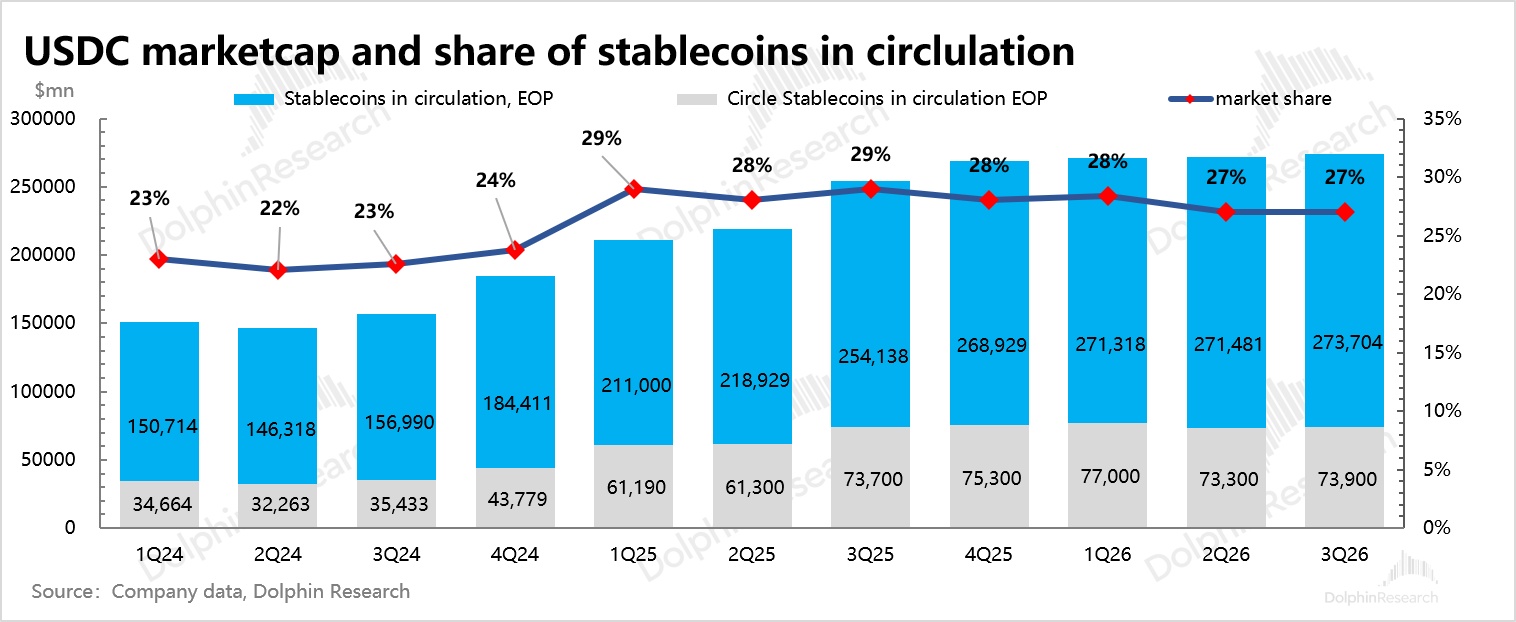
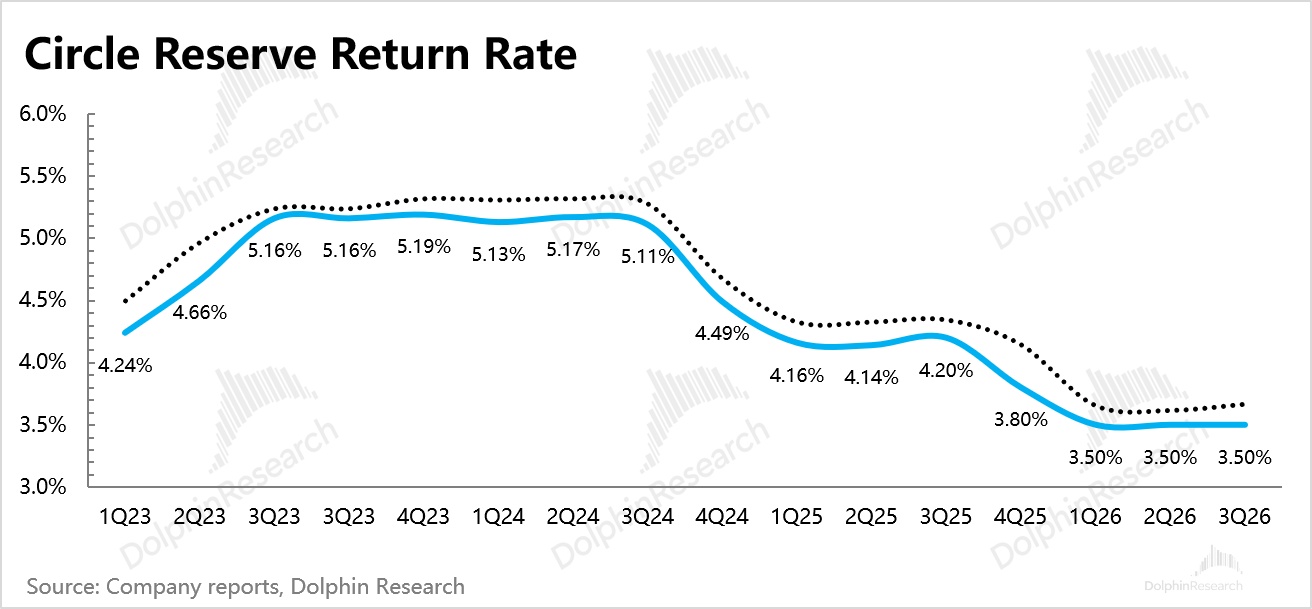
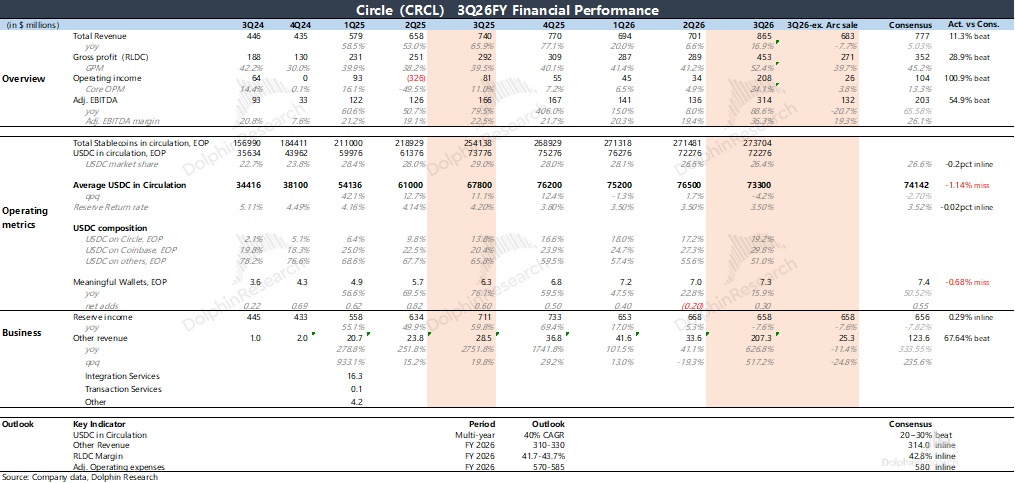
Q3 reserve interest income was $660 mn, in line with expectations. Despite USDC market cap rising 8% YoY, lower yields drove an ~8% YoY decline in interest income. On a QoQ basis, USDC averaged $73.3 bn in circulation in Q3, down 4% vs. Q2.
2、Arc 代币销售确认节奏比想象中快
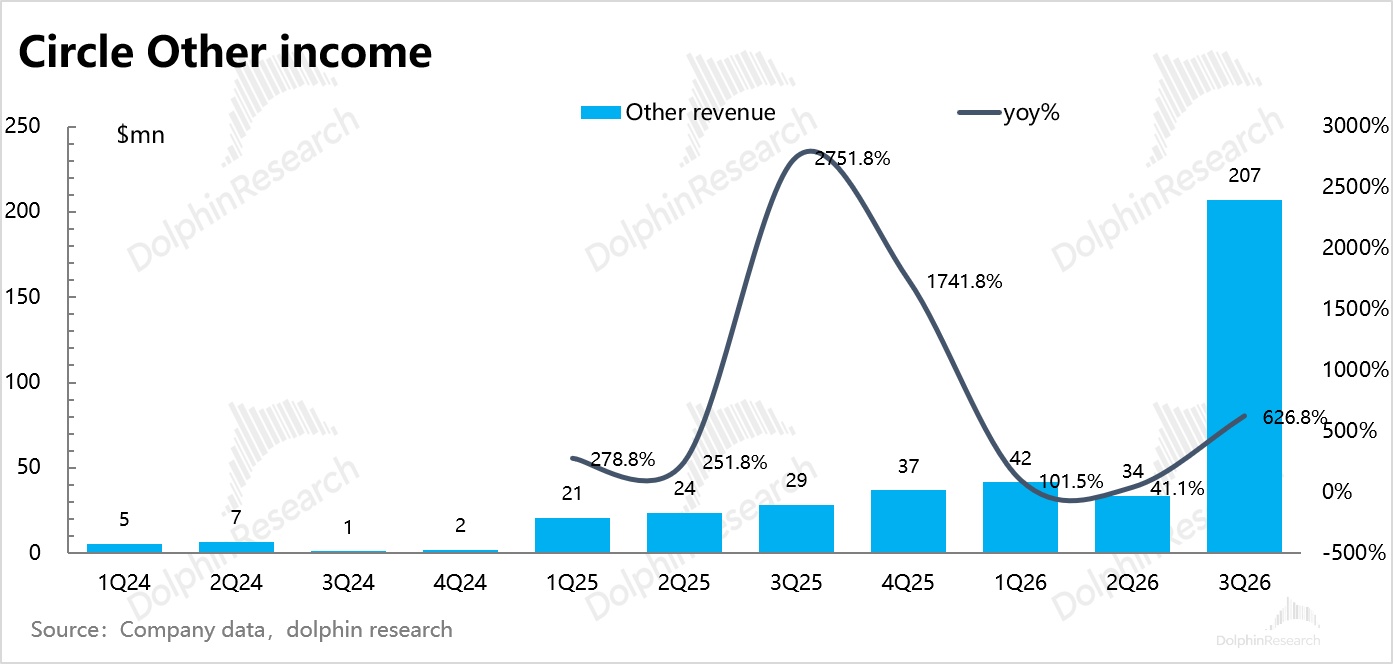
Other income topped $200 mn in Q3, of which Arc token sales contributed $180 mn. Recognition timing was faster than the market expected (~$90 mn) and ahead of the prior full-year guide of $180 mn.
That revenue is not stable or recurring and is more one-off in nature. Given the unchanged full-year guide for other income at $310–330 mn, Q4 likely has no such Arc revenue. Total presales were $224 mn this year; with $180 mn recognized in Q3, the remaining ~$40 mn will be recognized next year.
The Arc token presale drew sizable institutional demand. Economically it resembles an equity subscription to future returns of the Arc L1, yet Circle booked it as deferred revenue up front and recognizes it as the Arc chain progresses.
Treating equity-like subscriptions as revenue is awkward and undermines forward visibility. Unless token sales keep recurring as 'financing', this is essentially one-off and lacks a durable biz. characteristic.
Recurring revenue should start in 2027, driven by Arc transaction fees, staking income, and fees from the CPN payment network. The Arc presale merely pulled forward part of future value.
3、大渠道 “反咬”,后续利息分成压力加大
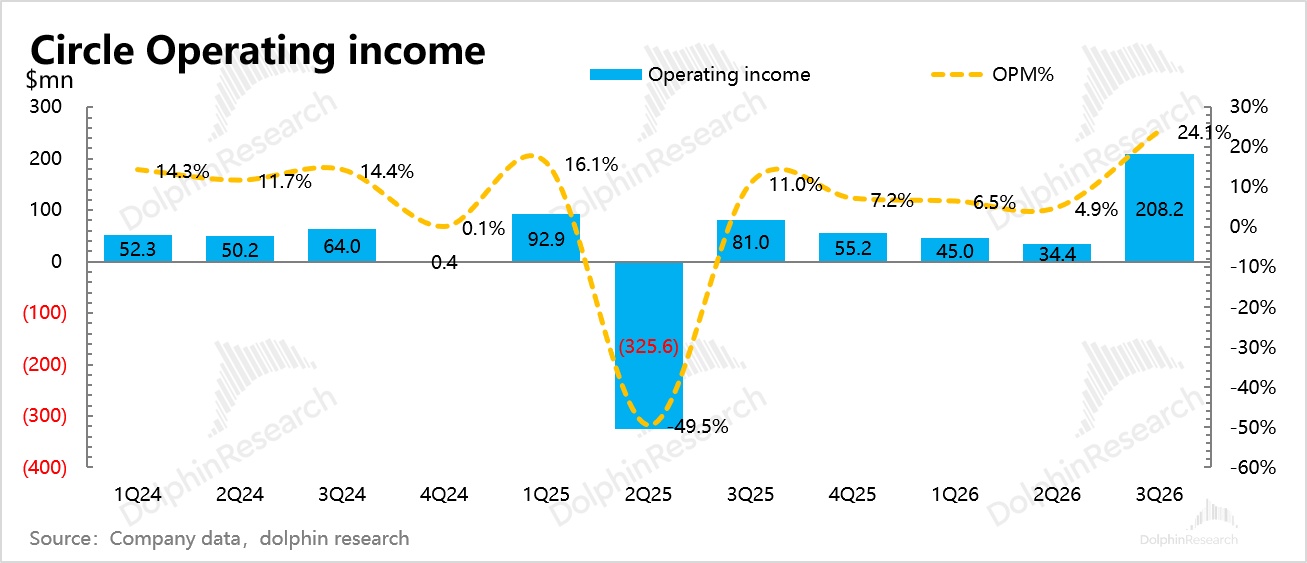
Since Arc token sales carry negligible costs, the $180 mn was largely pure profit, inflating Q3 earnings optics. After normalization, the underlying trend is weaker as revenue fell while costs are sticky; GAAP OPM was 3.9%, down 100 bps QoQ vs. Q2.
Even so, Q3 reflects cost optimization from layoffs. Personnel accounts for nearly half of Circle's costs, and Adj. opex (ex severance) fell 5% QoQ, consistent with a 5% headcount reduction during the quarter.
It is worth noting that Hyperliquid's revenue-sharing impact will increasingly show up from Q3 onward. Dolphin Research roughly estimates Circle will forgo close to $100 mn of GP per year, with the effect likely becoming evident as early as Q4.
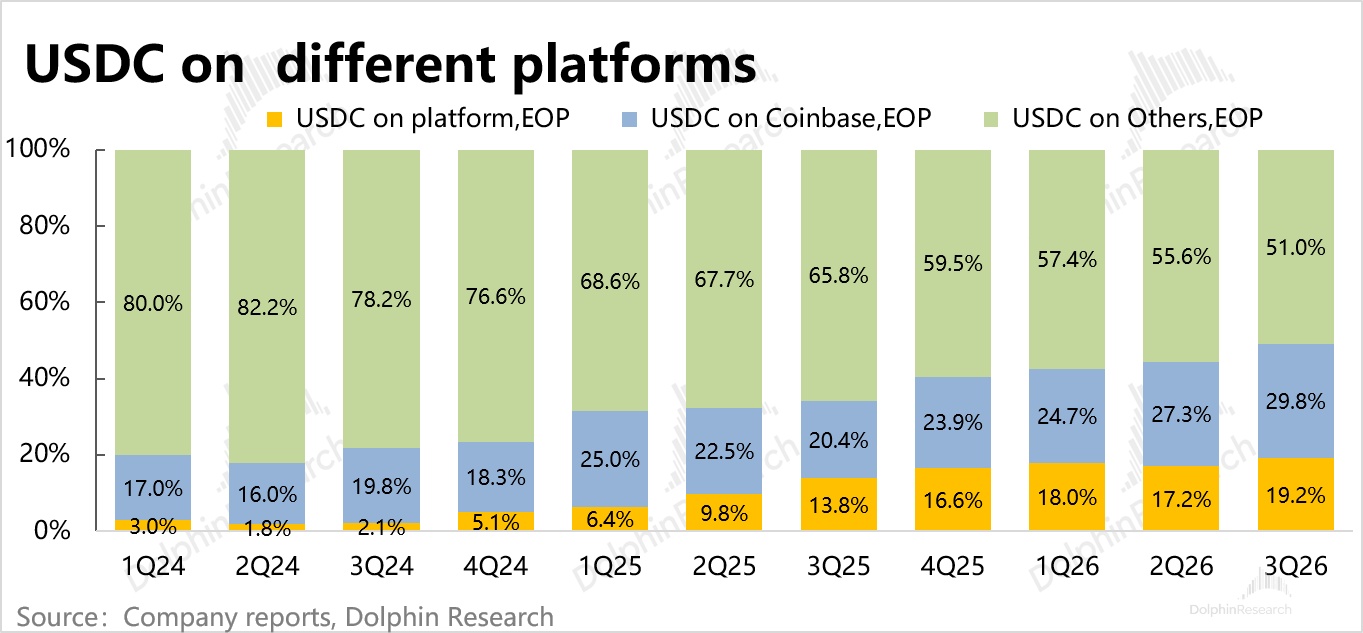
Hyperliquid is the largest on-chain perp DEX and operates its own L1. Users first deposit USDC as margin, leading to a sizable USDC pool on-platform, roughly $6.0 bn, which is one of the few large off-exchange USDC reservoirs for Circle.
Amid different interests around the CLARITY Act, Hyperliquid began requiring Circle to rebate reserve interest on USDC starting in Sep. However, Circle has a preset split with Coinbase: Coinbase keeps 100% of interest for USDC custodied on-platform, while for off-platform USDC interest, Coinbase takes 50%.
Therefore, to meet Hyperliquid's rebate demand, funds must route through Coinbase. The result is twofold:
(1) Hyperliquid recovers most of the interest (est. 90%).
(2) Coinbase and Circle each forgo 50% of their interest share while adding that 90% to on-platform AUC, and Circle retains 10%.
USDC within the Hyperliquid ecosystem totals $6.3 bn; at a 3.5% yield, reserve interest runs ~$228 mn per year, of which Hyperliquid takes ~90% or ~$200 mn. The remaining sub-$30 mn is split by Coinbase and Circle.
In other words, what could have been $228 mn of interest income and ~$100 mn of GP (after issuance costs and the pre-existing 50% split to Coinbase) ultimately dwindles to roughly $10 mn of GP.
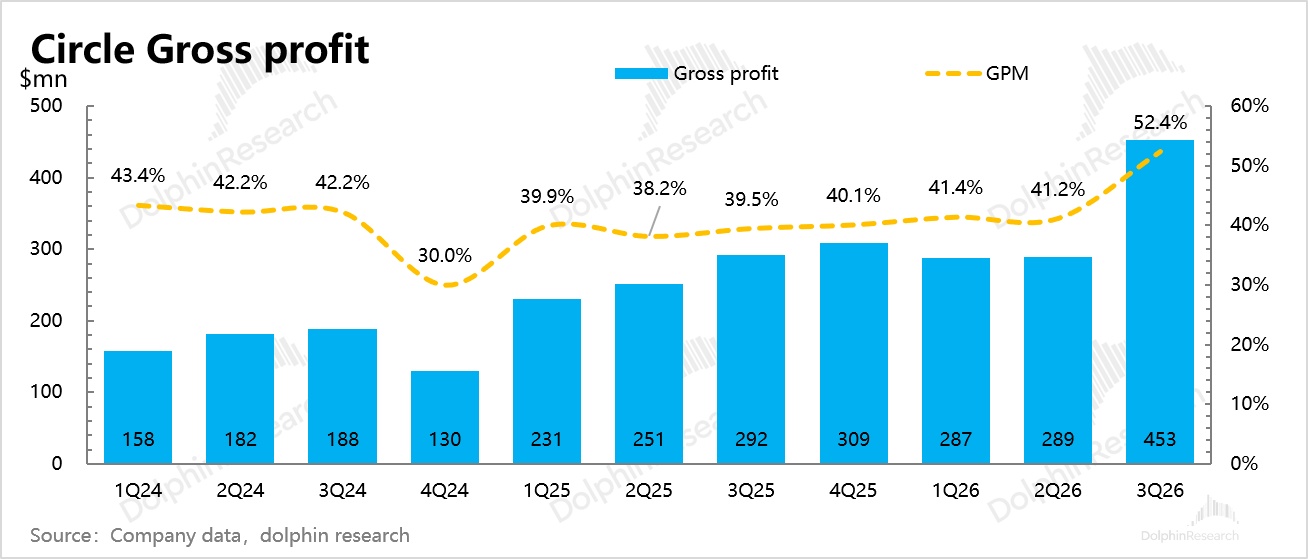
Q3 GPM was 52.4%. Excluding the $180 mn pure profit from Arc token sales, GPM was 39.5%, already showing some impact vs. Q2.
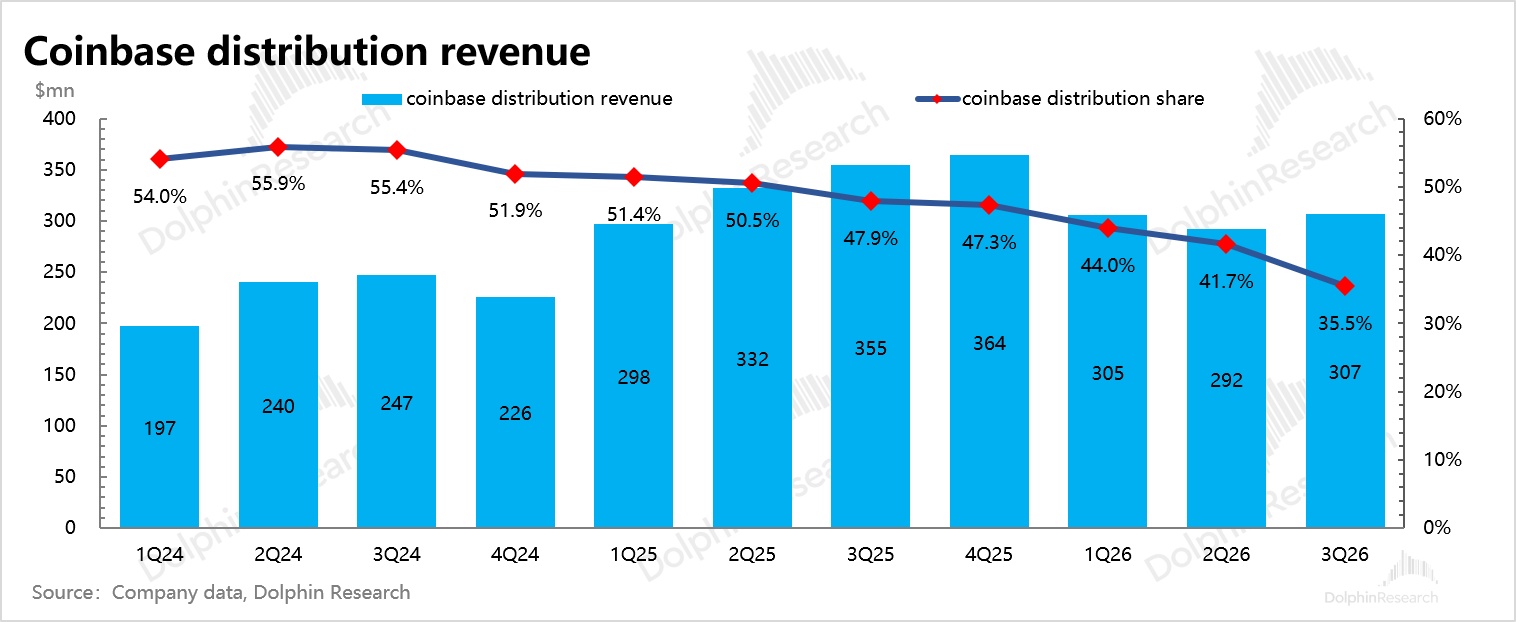
USDC's share on Coinbase rose quickly to 30%, yet the share of revenue-sharing income within Circle's rev-share costs fell rapidly to 35%. This corroborates the impact from Hyperliquid's 'pushback'.
4、Circle 业绩电话会纪要《Circle(纪要):USDC 存量持平,CPN 与 Arc 接力》
5、重要指标一览
海豚君观点
The Q3 print was a 'bloated' beat driven by recognition timing differences, not a true surprise. Guidance for revenue and earnings is unchanged.
RLDC margin (revenue less distribution costs, akin to GPM) is guided to ~42% for the year. That implies Q4 GPM will step down into the low-30s, reflecting a deepening Hyperliquid impact.
The Hyperliquid issue was disclosed in Sep and is quantifiable, so it should be largely priced in. The risk is whether a second 'Hyperliquid' emerges.
Meanwhile, stablecoin competition is intensifying. USDC's edge lies in UST-backed reserves and higher compliance, plus tight alignment with Coinbase, a major US centralized exchange with stronger regulatory ties.
But the competitive landscape among financial institutions is shifting. As USDC draws closer to Binance — which invested $100 mn in Circle equity and expanded/renewed their strategic partnership — dynamics with Coinbase could become delicate despite the Binance collaboration focusing on EMs.
Coinbase and a group of traditional payment-chain players also launched the Open USD alliance coin on Sep 30. Dolphin Research believes that apart from USDT, USDC still holds a clear edge over the alliance coin, which may struggle to form effective cohesion given the many stakeholders.
By contrast, constraints from other institutions are more likely to mirror Hyperliquid-like channel partners demanding interest rebates, with associated risks and impacts.
Thus, even with management's long-term bullish guide for USDC circulation (CAGR ~40%), the near-to-mid term still hinges on a healthier crypto cycle, USDC's core use cases, and its ability to break through competition. Execution against these factors will be key.
Valuation-wise, the current market cap is ~$18.9 bn. Under a cautious view that excludes one-off Arc token sales and reflects the muted USDC scale in Q2–Q3, 2027E reserve interest plus minting revenue could be ~$2.8 bn (7 x 4), with an additional ~$200 mn from Arc chain transaction fees (non-token sales), totaling ~$3.0 bn.
Assuming Adj. EBITDA margin of 15% (down 5 pct vs. a 20% 'normal' to reflect Hyperliquid's net drag), the current market cap implies ~40x on 2027E Adj. EBITDA P/E. That is not obviously cheap and leaves limited margin of safety.
本文的风险披露与声明:海豚研究免责声明及一般披露
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.