


LKNCY: Shedding delivery drag, the Little Blue Cup runs lean.


Luckin Coffee (LKNCY) released Q3 2026 results before the U.S. market open on Nov 3 Beijing time (quarter ended Sep 2026). Against a high base set by last year's peak delivery subsidies, softer SSSG pulled revenue growth below consensus. Profit beat on lower delivery expense; key takeaways as follows: $Luckin Coffee(LKNCY.US)
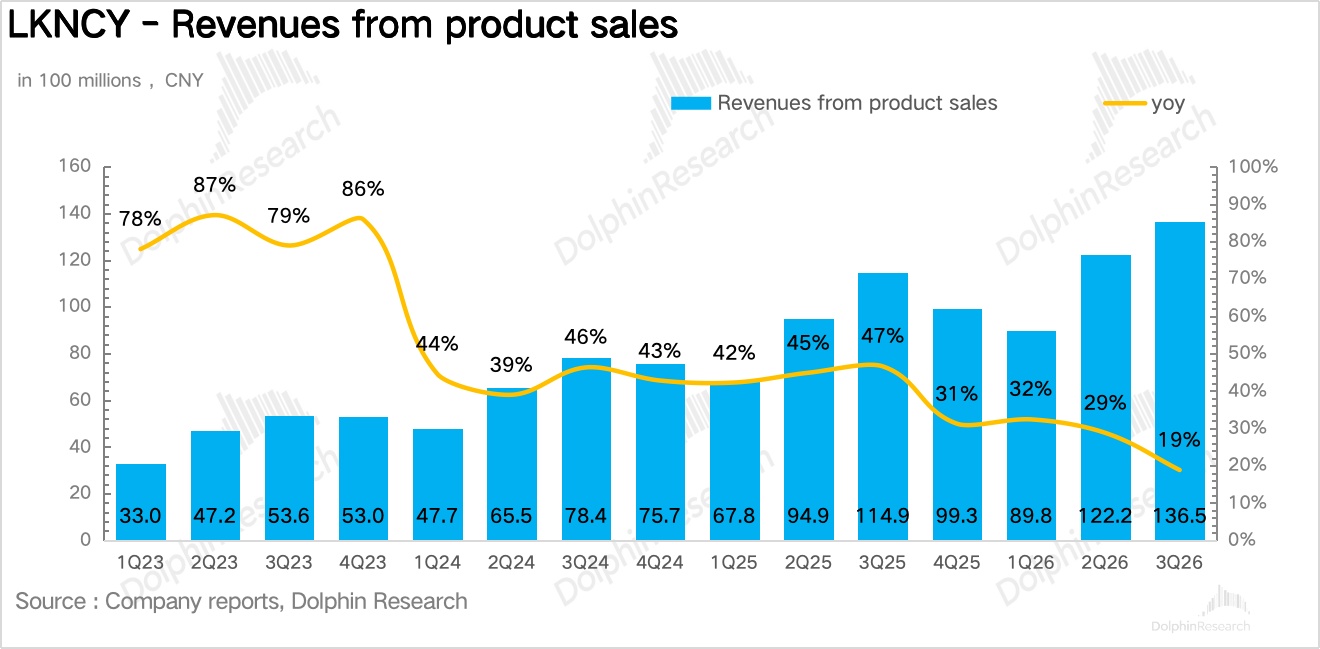
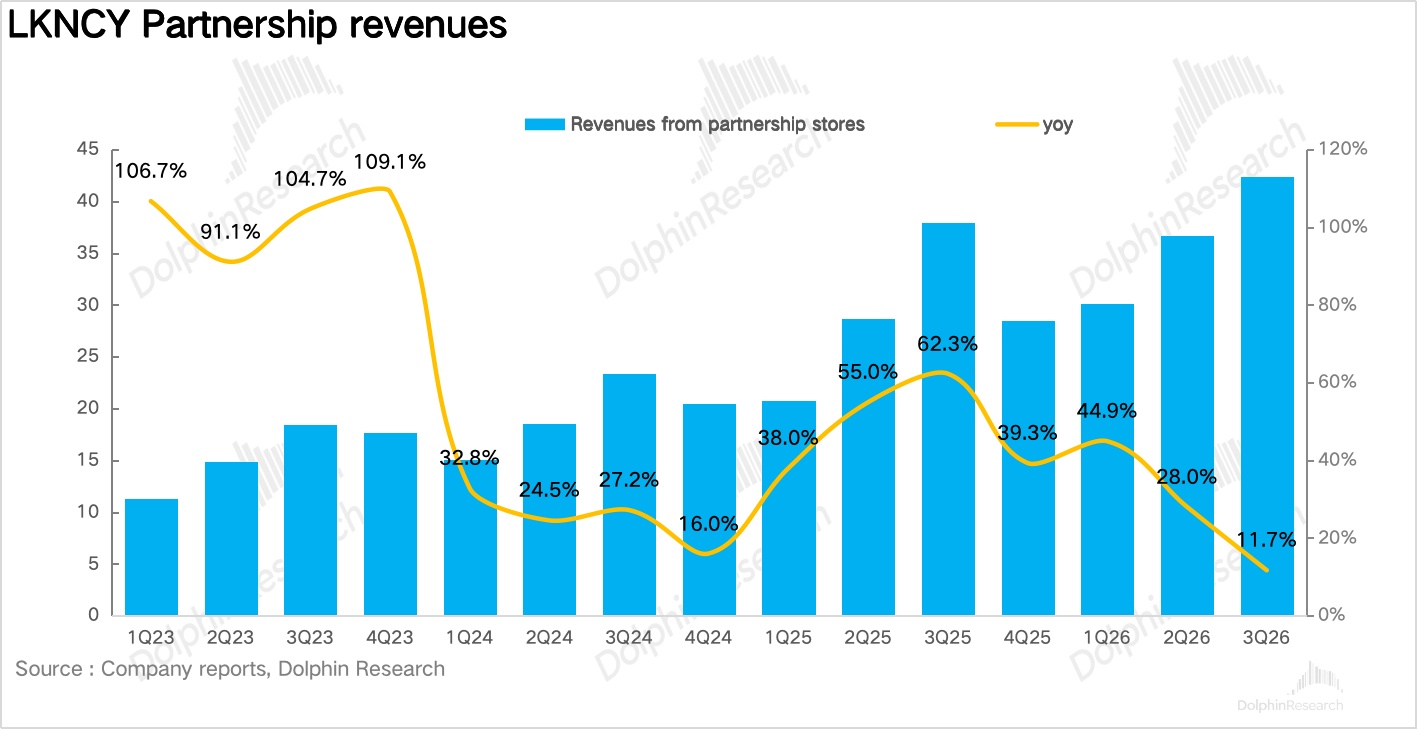
1) Revenue slightly below, growth cooled on the tough base. Q3 revenue was RMB 17.89bn (+17.0% YoY), a touch below consensus (~RMB 18.26bn). Growth was still driven by store expansion and user gains; self-operated store revenue rose 16.8% YoY and franchise revenue rose 11.7% YoY, both notably slower vs. Q2.
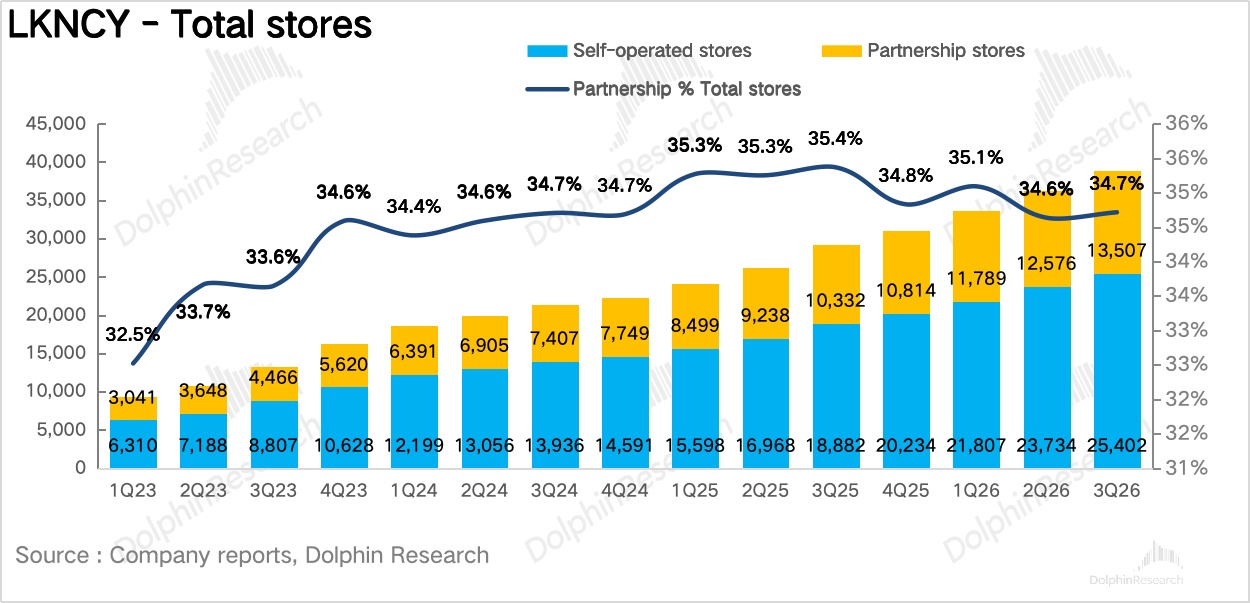
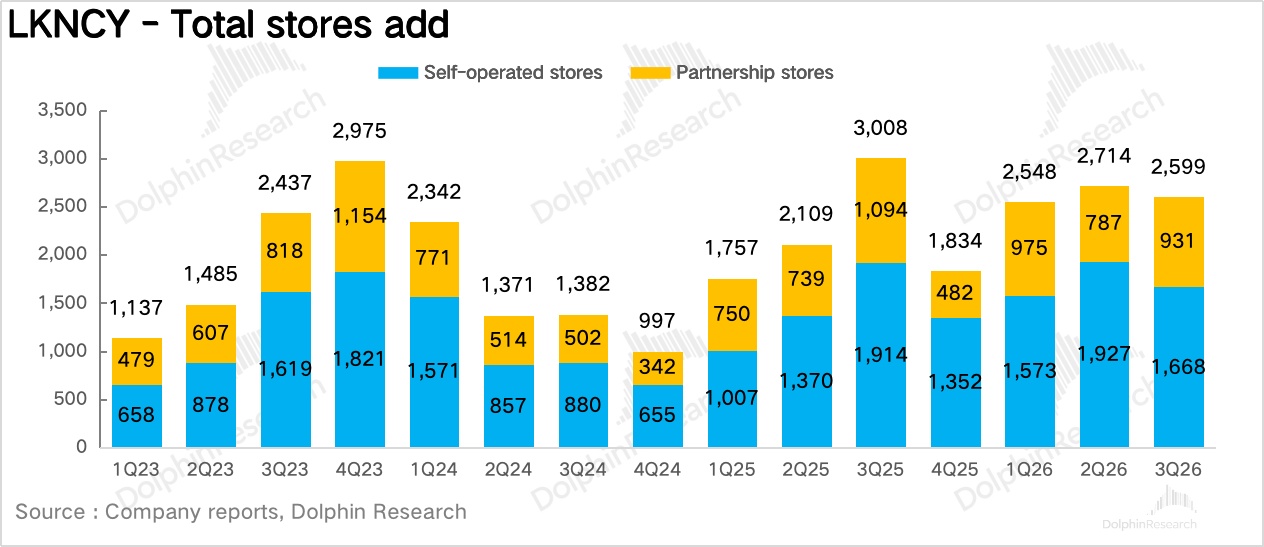
2) Openings held up; share remains the top priority. Luckin added a net 2,599 stores in Q3, a modest slowdown vs. Q2, ending with 38,909 stores (+33% YoY). Self-operated net adds were 1,668, still ahead of franchise, while overseas added 56 to approx. 279, with Malaysia the key market. At the current pace, surpassing 40k stores this year looks essentially locked.
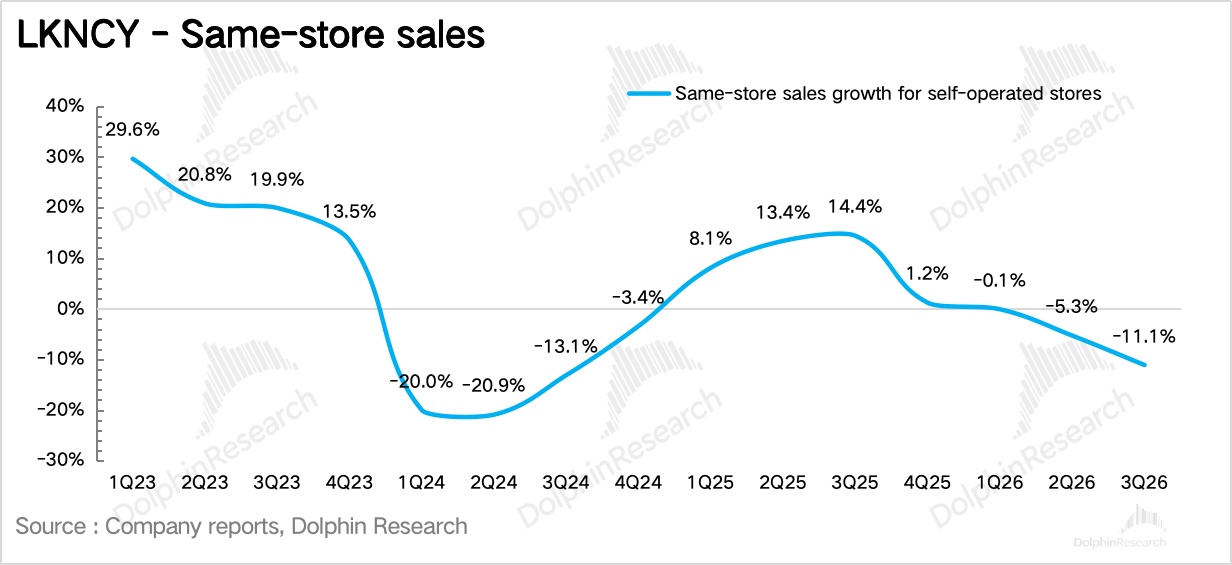
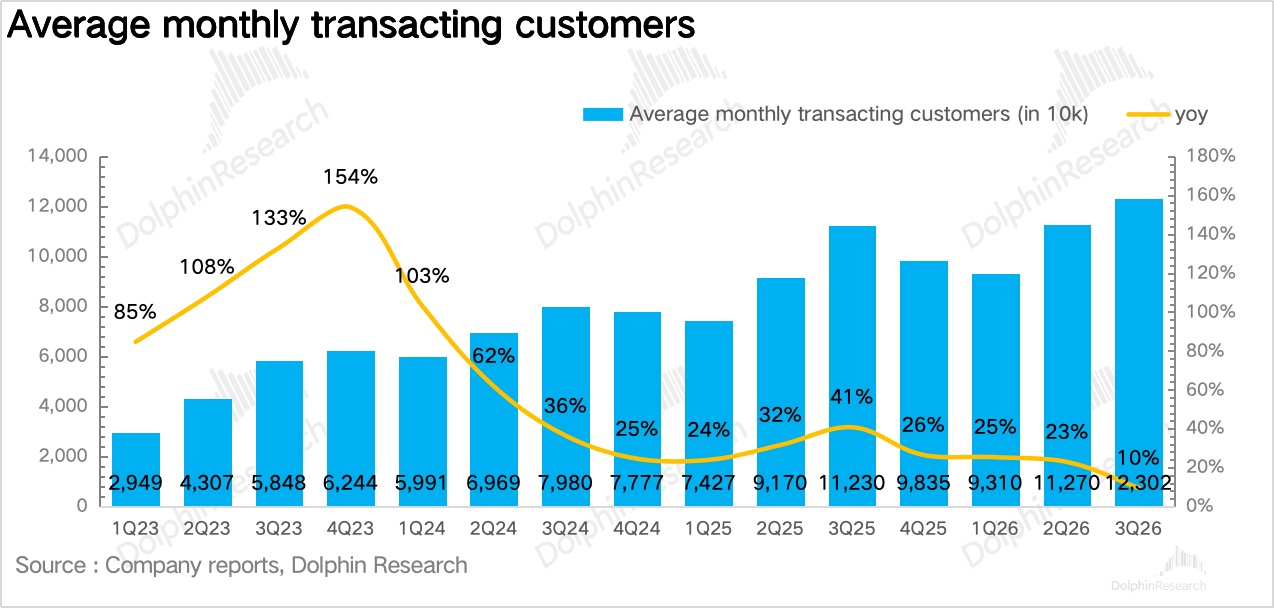
3) SSSG hit a yearly low, but users set a new high. Self-operated SSSG fell 11.1% YoY, widening from -5.3% in Q2, primarily due to the peak base from last year's heavy delivery subsidies in the same period. Meanwhile, monthly avg. transacting customers reached 123mn (+9.6% YoY), a record high, suggesting demand remains intact and SSS pressure is more about cannibalization from network densification.
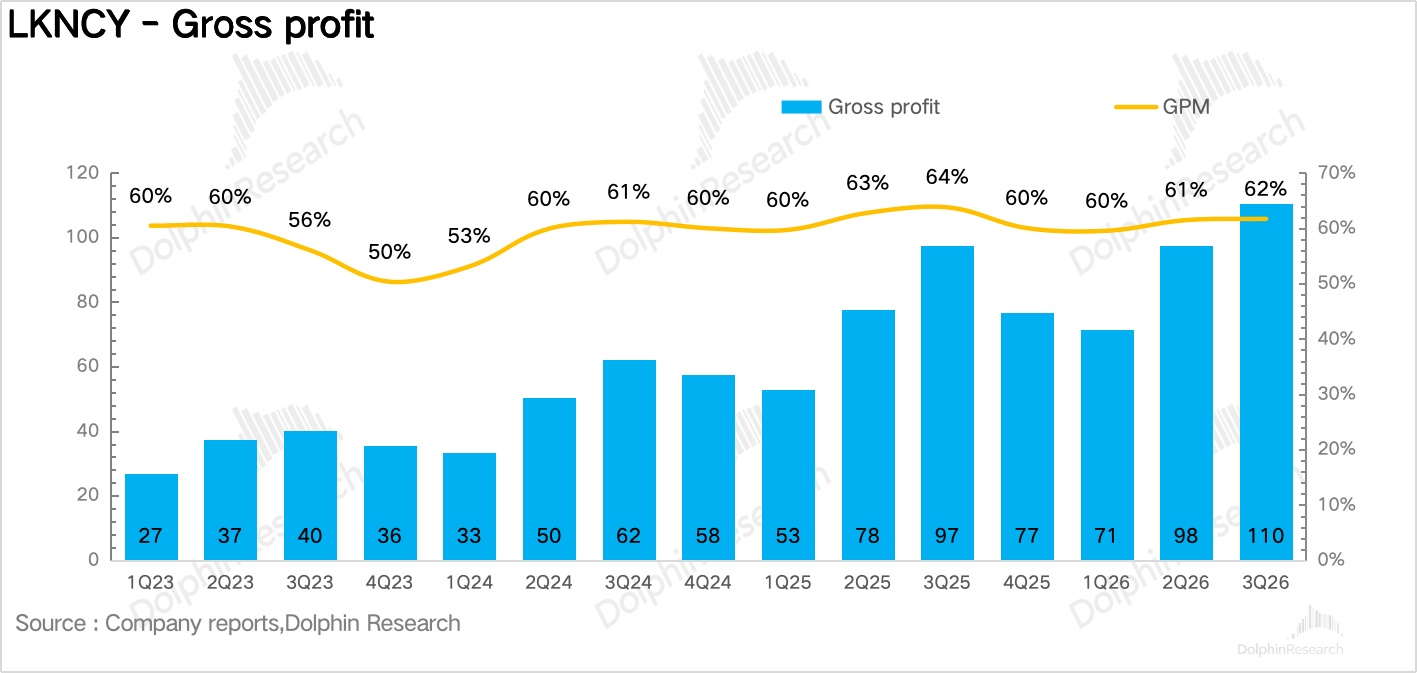
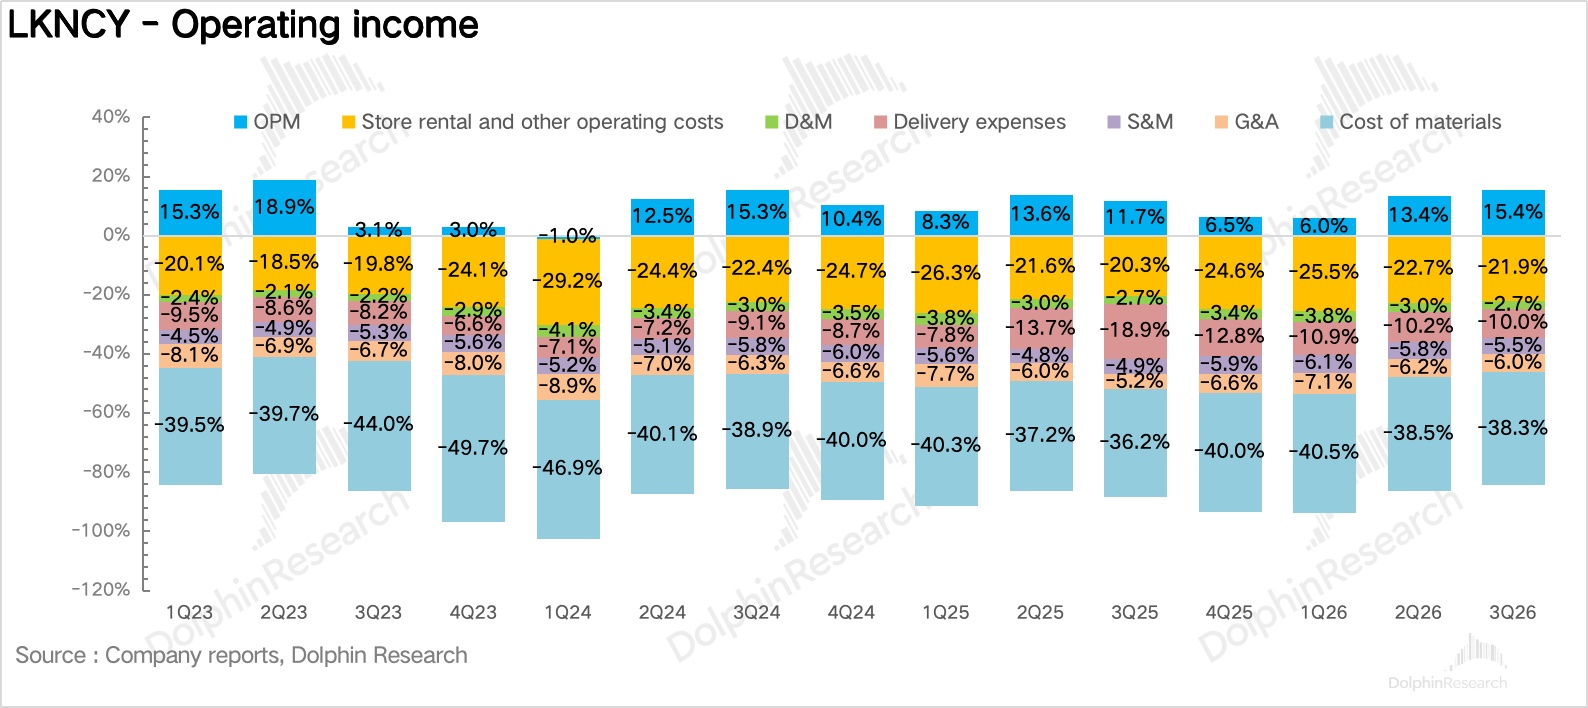
4) Delivery expense ratio fell sharply. Q3 GPM was 61.7%, down 210bps YoY, which Dolphin Research infers stemmed mainly from lower net price per cup amid heavier promotions on co-branded items and low-priced tea launches. Delivery expense was RMB 1.79bn (-38% YoY), with the ratio dropping to 10% from 18.9% a year ago, as the company attributed this to a marked shift in order mix from delivery to pickup.
5) Store-level margin rebounded, profit hit a quarterly high. With delivery expense sharply lower, store-level margin reached 23.3%, up 580bps YoY. On opex, heavier co-branding and RTD promotion pushed the S&M ratio up 60bps YoY to 5.5%, while higher SBC lifted G&A by 80bps to 6.0%. Non-GAAP OP was RMB 3.05bn (+58.2% YoY) with a 17.0% margin, a record high for a single quarter.
6) Key financial metrics at a glance
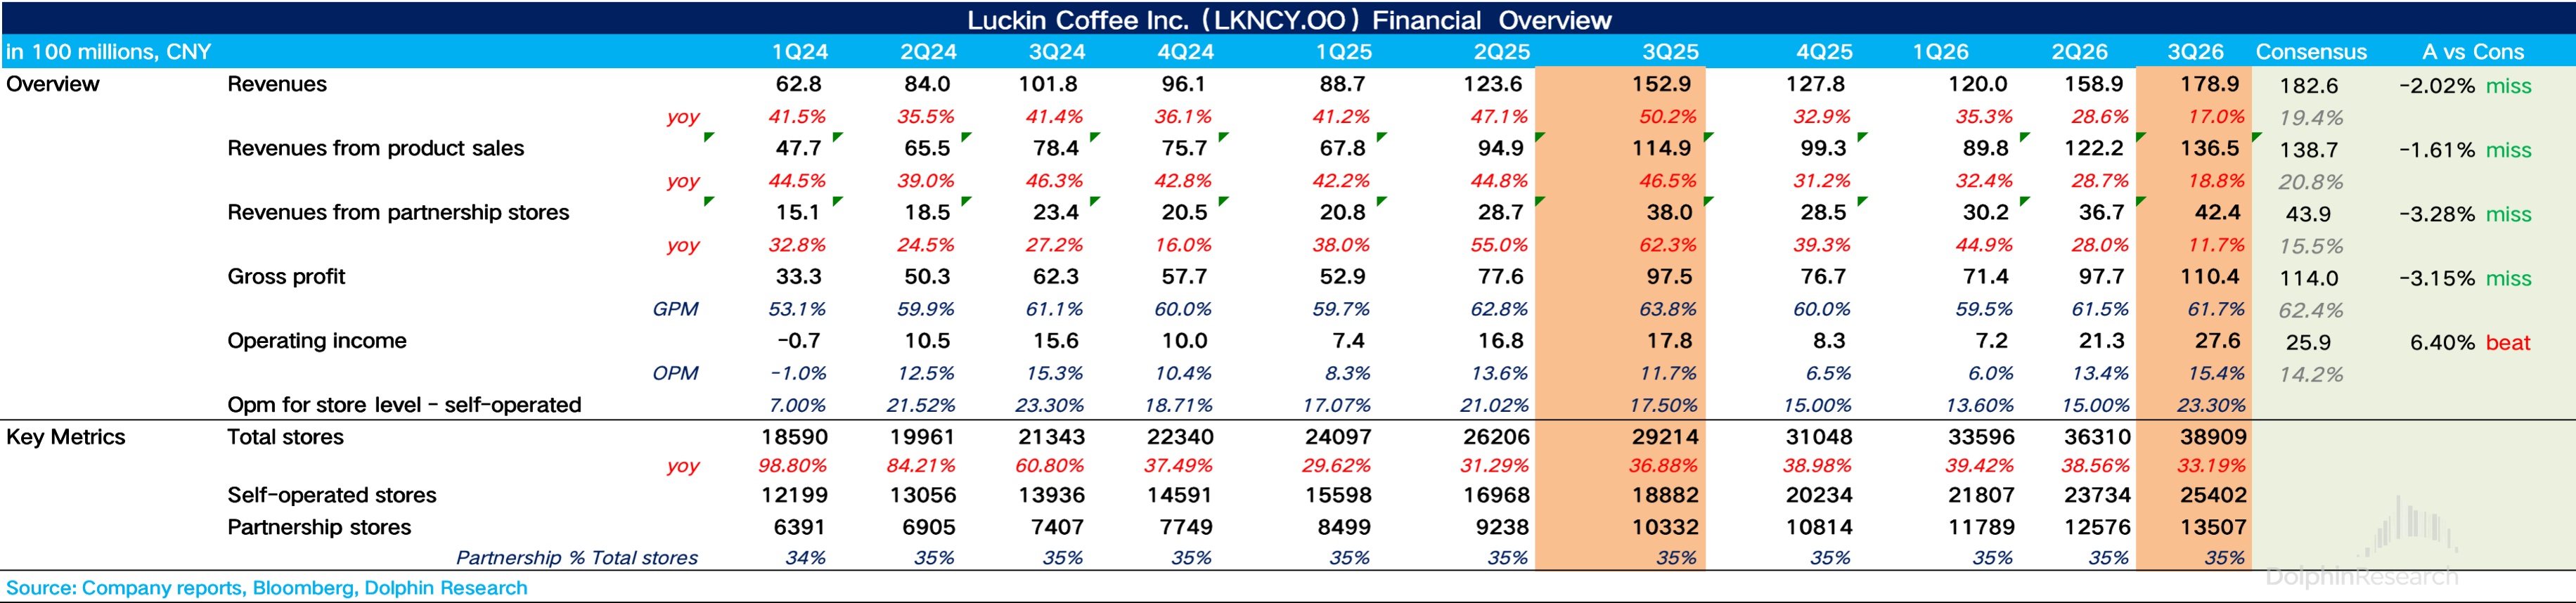
Dolphin Research overall view:
As noted last quarter, the market’s focus has shifted from near-term SSSG to the durability of margin improvement: 1) whether delivery expense ratio can keep easing, and 2) the QoQ slope of store-level margin recovery. Q3 delivered on both: delivery expense ratio looks near a new post-subsidy normal, and store-level margin rose another ~200bps QoQ to 23.3% despite -11% SSSG, showing stronger-than-expected resilience.
Luckin’s strategy also remains explicit—accept single-store dilution to gain share. Despite three consecutive quarters of negative SSSG, net adds stayed above 2,500 for the quarter, putting 40k stores within reach this year. Dolphin Research believes this is rational as long as store-level margin keeps improving—densification raises location moats and user reach, while per-store dilution fades as new stores ramp.
Looking to Q4, with last year’s Q4 SSSG at just +1.3%, the base eases sharply; coupled with research indicating over 100mn cups sold nationwide during Golden Week and comps turning slightly positive, Dolphin Research expects SSS declines to narrow materially in Q4, likely back to flat.
Beyond that, the YoY tailwind from delivery expenses should largely fade after Q2 2027, and margin gains will depend more on GPM and operating leverage. Encouragingly, arabica futures are down over 20% from last year’s peak; with procurement lag, coffee bean costs could become a GPM tailwind in 2027.
On valuation, Dolphin Research raises its 2026 Non-GAAP net income estimate to ~RMB 5.8bn (RMB 4.58bn achieved in the first three quarters). At a pre-market price of about $33 (market cap ~RMB 70bn), this implies ~12x 2026 and ~10x 2027 assuming ~20% profit growth, still well below the ~16x average since 2022. Despite an OTC discount, versus an estimated ~20% profit CAGR over the next three years, the current level does not look demanding. If the multiple re-rates to 15x, upside would be around 25%.
Below are a business overview and detailed charts:
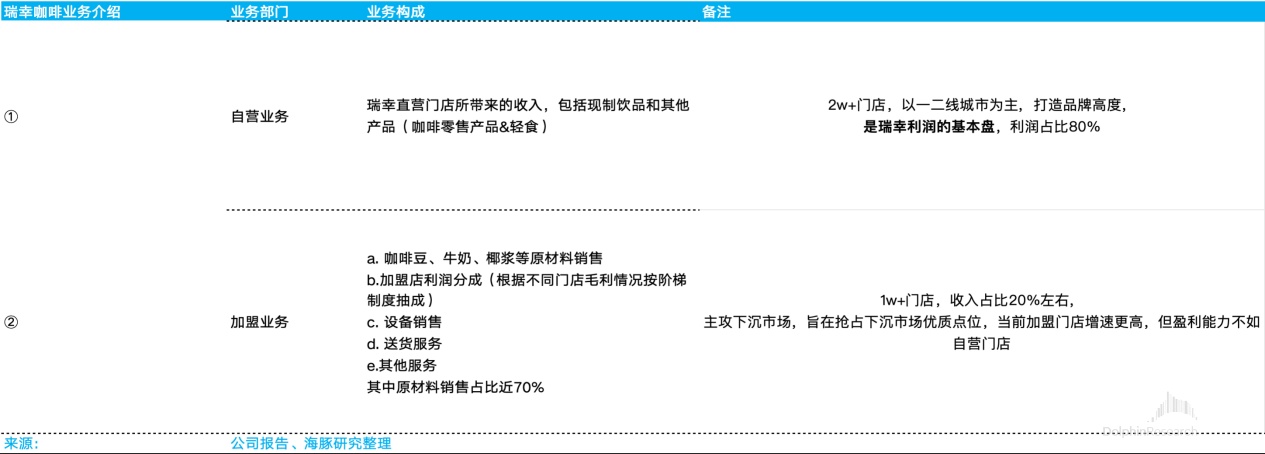
Per Luckin’s disclosures, the company operates two major lines: self-operated and franchise.
1) Self-operated refers to revenue from company-operated stores. By end-Q1 2026, there were 21,807 self-operated stores, mainly in Tier-1/2 cities, critical for brand building. This segment is the profit bedrock, contributing over 80% of profit, and is the focus for three key metrics: SSSG, store-level margin, and delivery expense.
2) Franchise revenue includes: sales of raw materials to franchisees (coffee beans, milk, coconut milk), profit-sharing based on store GP tiers, equipment sales, delivery services, and other services, with raw materials close to 70% and the core revenue driver. By end-Q1 2026, franchise stores totaled 11,789 with about 25% revenue mix, focused on lower-tier markets; while faster to open, they are less profitable than self-operated stores.
In addition, Luckin formally launched its retail CPG business starting in Q2:
- Bottled RTD (Luckin Ready-to-Drink): launched on Apr 28 via distributors and retail, asset-light without in-house plants, with OEM production entrusted to Uni-President Enterprises. Luckin handles brand, formulation, channel development, and marketing, a typical FMCG OEM model.
Earnings Season
Aug 3, 2026 results take: Luckin Coffee: Moving past delivery hangover, is the 'Little Blue Cup' entering a tailwind phase?
Apr 29, 2026 results take: <Luckin Coffee: Revenue up but profit not, when will the 'delivery hangover' end?>
Feb 26, 2026 results take: Luckin: Has the delivery war 'hijacked' the coffee leader?
Nov 17, 2025 results take: Luckin: A deep squat in profits for a better jump
Jul 30, 2025 results take: Luckin: The 'Little Blue Cup' surges, a clear runway for the coffee leader?
Apr 29, 2025 results take: Unwilling to be a penny-pincher, Luckin is 'stirring the pot' again?
Feb 21, 2025 results take: After the RMB 9.9 era: Luckin flips the script, Cotti hangs on
Deep Dives
Jan 16, 2024: Cotti struggles to stand firm, Luckin cannot be out-competed
Mar 14, 2023: Cutting out the tumor, Luckin wins its comeback fight
Feb 14, 2023: Luckin (Part I): Coffee goes rural; can the county-level boom last?
Risk disclosure and statement: Dolphin Research disclaimer and general disclosure
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.