


PLTR: Guidance keeps ramping, yet new contracts become a target for 'nitpicking'?


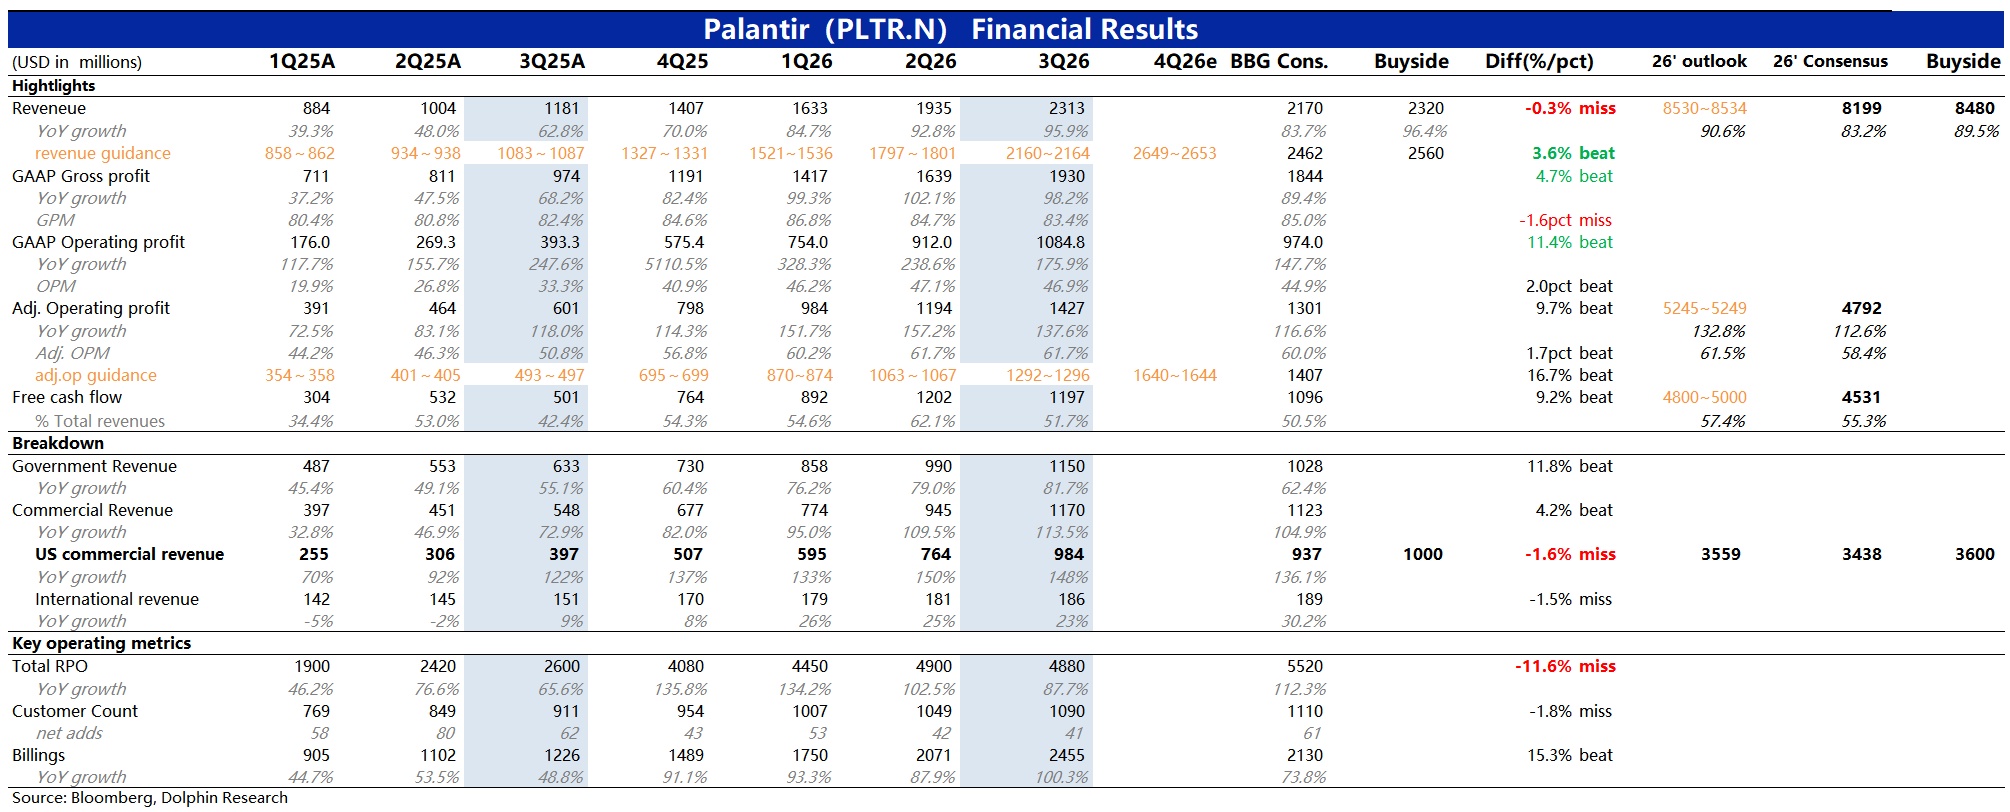
$Palantir Tech(PLTR.US) delivered another solid Q3 print, but with lofty expectations and softer leading indicators, the stock is unlikely to get much near-term follow-through from this report.
Drill-down:
1. Outlook: guidance beat vs. leading indicators miss
Given PLTR’s rich multiple is anchored in forward growth, start with the outlook. By outlook, we refer to next-quarter and full-year guidance, as well as leading indicators like bookings and customer count.
Q3 painted a mixed picture: Q4 revenue and profit guidance looked strong, implying accelerating growth with improving profitability. Yet new contract TCV fell QoQ and remaining performance obligations declined in absolute terms, casting a shadow beyond Q4.
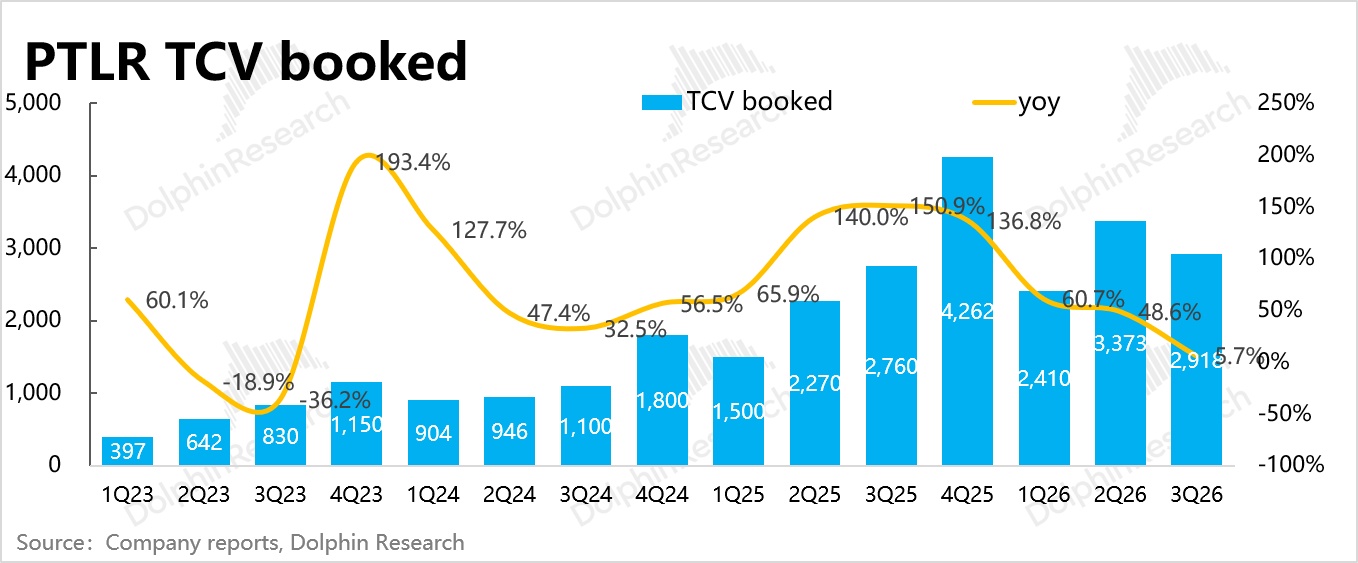
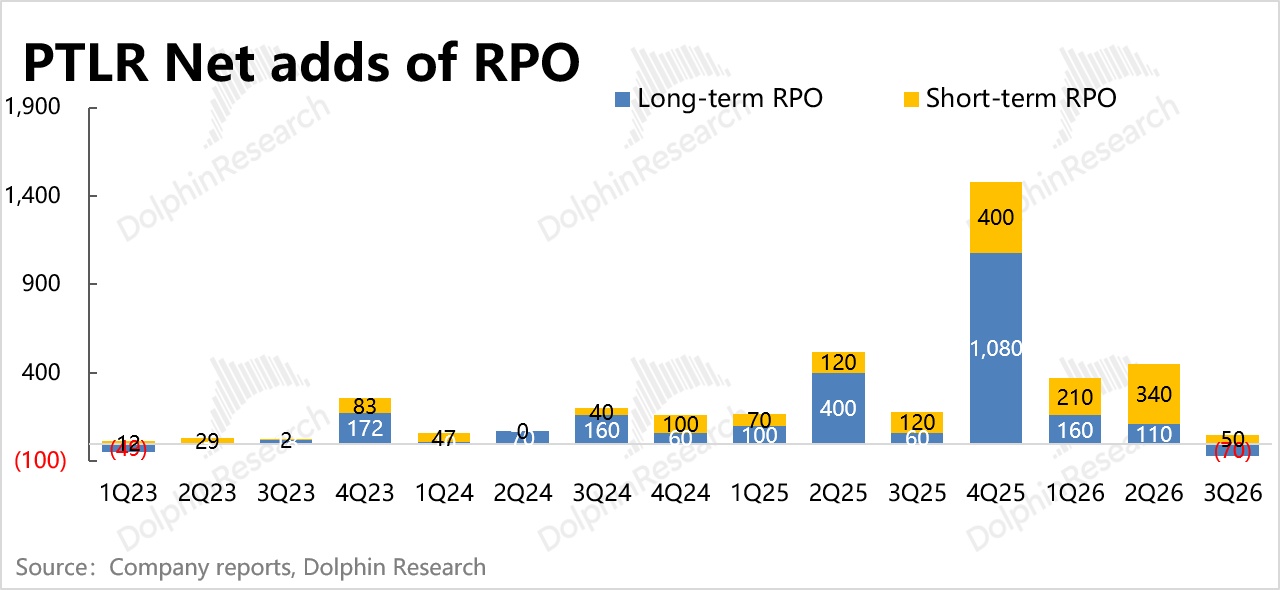
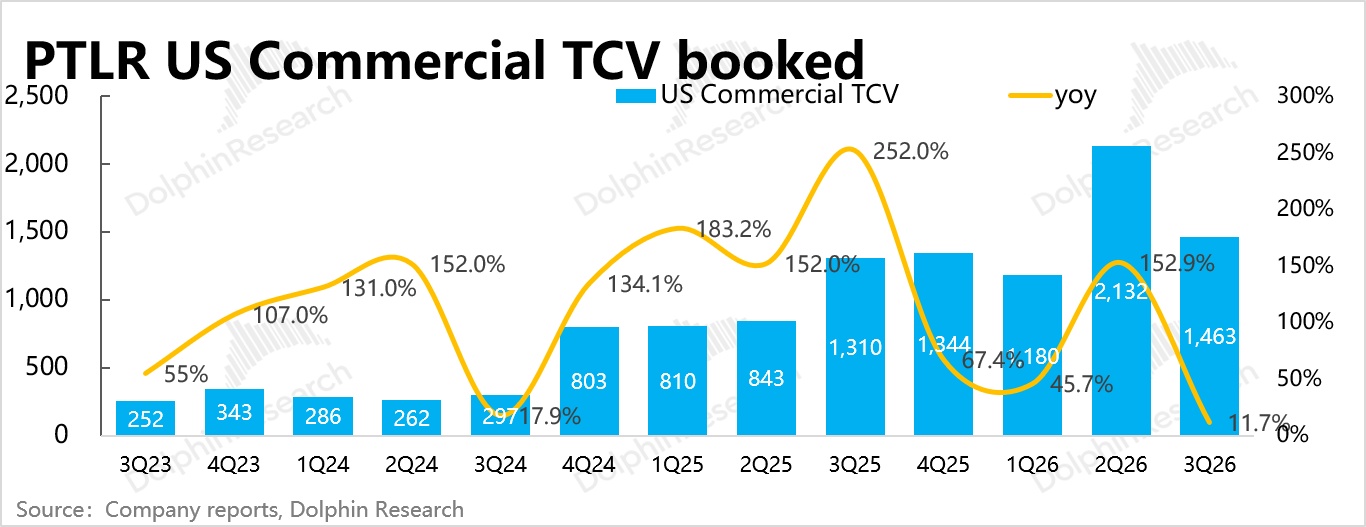
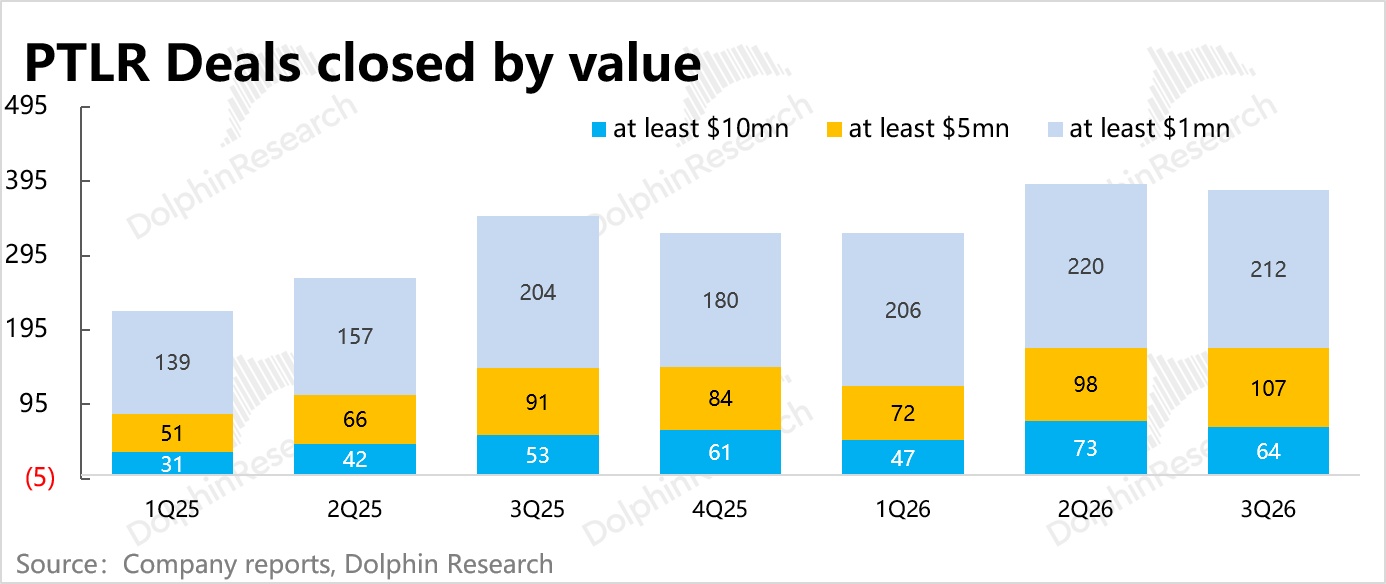
(1) Slower pace of large, long-dated wins: Q3 TCV was $2.9bn, down sequentially in absolute terms. The decline was mainly in US commercial, the primary driver, and the key point of dissatisfaction for the market. Fewer new wins also pulled RPO down QoQ, with the pressure concentrated in long-duration components.
(2) Strong near-term willingness to pay: Delivery on existing contracts remains healthy. Q4 guide implies revenue of $2.65bn (+88% YoY), suggesting continued high growth. While the growth rate appears to slow, PLTR typically guides conservatively; given historical beats, flat to accelerating growth remains very plausible.
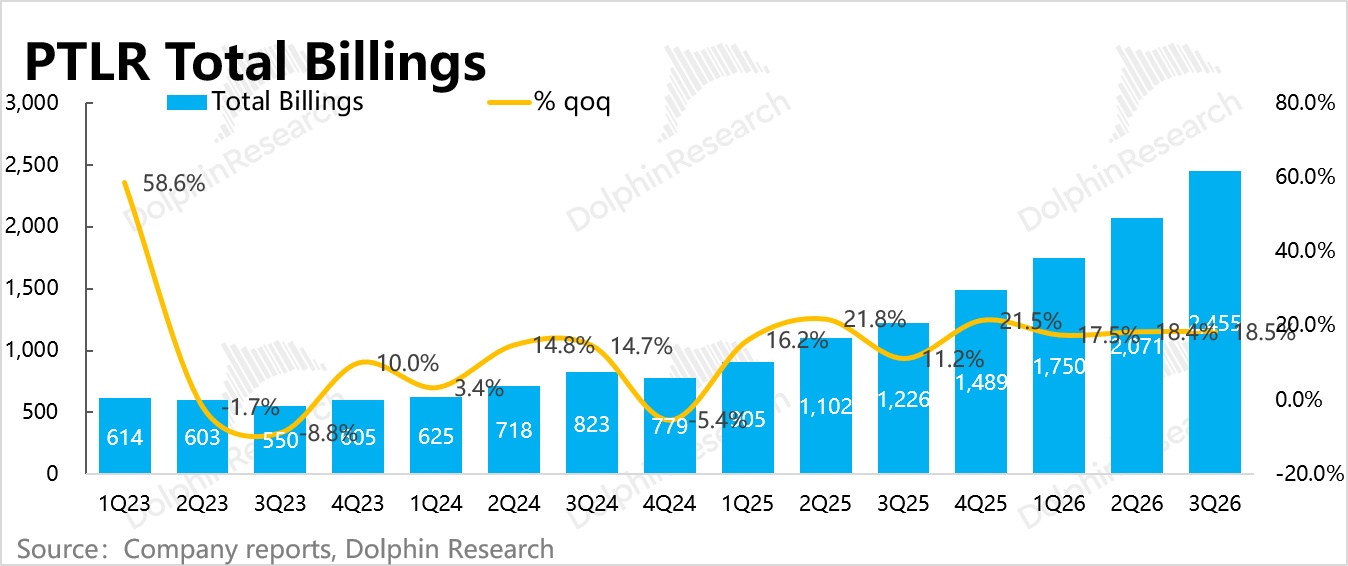
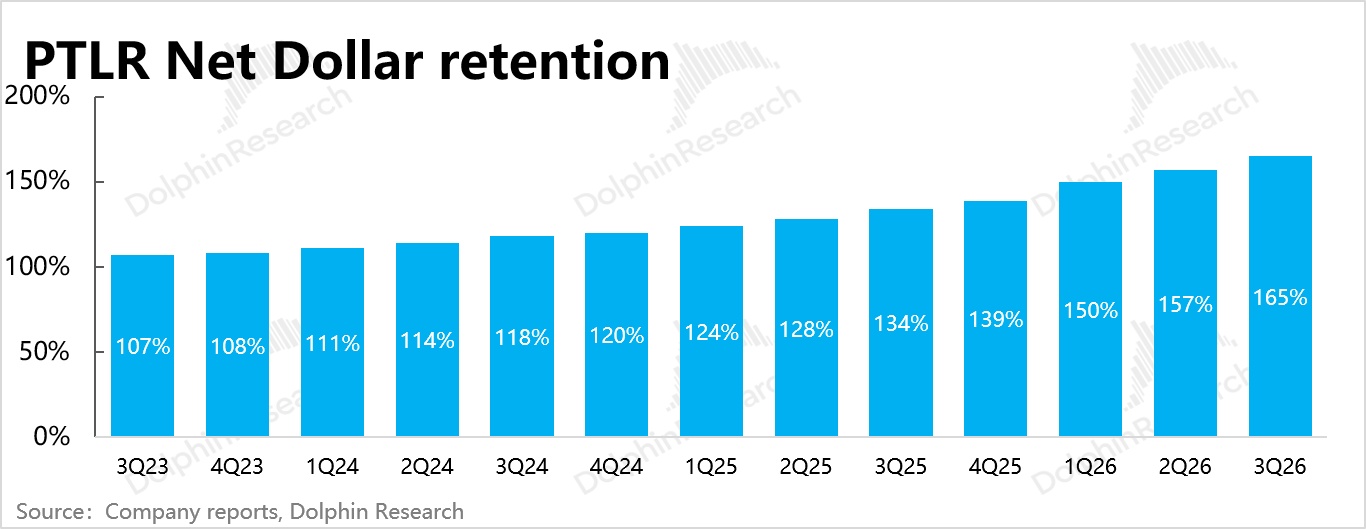
Q3 billings rose 100%, and total contract liabilities (incl. customer prepayments) increased by nearly $140mn QoQ. NDR improved to 165%, indicating solid execution on backlog and stronger upsell from existing customers.
(3) How to read 'guidance beat vs. leading indicators miss'?
Revenue is driven by near-term fulfillment of backlog, while bookings drive mid- to long-term revenue. Q3 bookings softness may reflect seasonality, especially after last quarter’s AIPCon 10-driven spike, but it also hints at challenges in landing new customers and longer-duration deals.
Evidence includes fewer $10mn+ deals QoQ and a drop in long-duration components within remaining backlog. New customer adds also slowed QoQ, underscoring rising friction in new logo acquisition. By contrast, existing customers kept upsizing and even increased usage. This suggests PLTR’s offerings continue to meet core clients’ customized needs, but high deployment cost and timelines make penetration beyond the core slower.
2. In-quarter performance: strong demand, but expectations were full
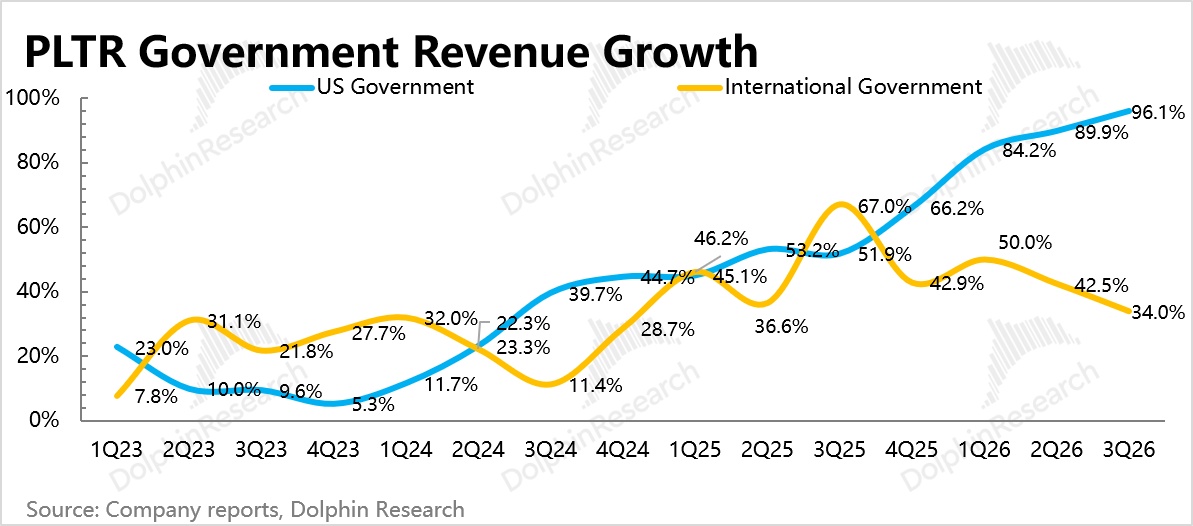
(1) Government: modest acceleration. The US remained the engine on both scale ($950mn) and growth (+96% YoY). Recent US Gov. moves to shift PLTR from standalone projects to production deployments and enterprise-grade platforms should deepen the moat of the core franchise.
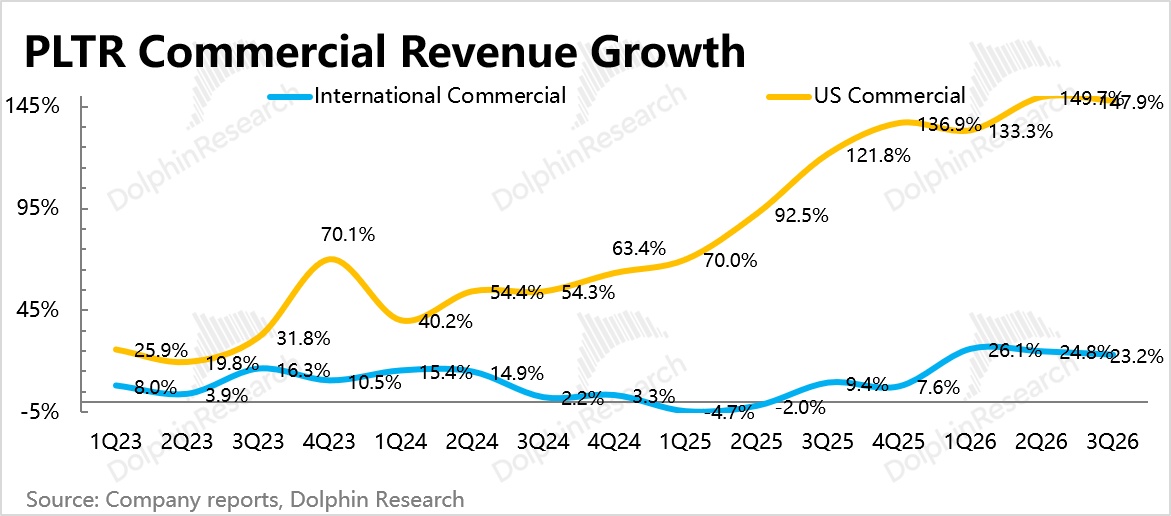
(2) Commercial: continued acceleration. US commercial revenue rose 148%, Intl up 23%; both were roughly flat QoQ, but buy-side expectations were higher. Since Q3, the customer reach has expanded, and PLTR doubled down on three vertical engines where software density remains low: financials, semis, and the new cloud, deepening and broadening ecosystem partnerships.
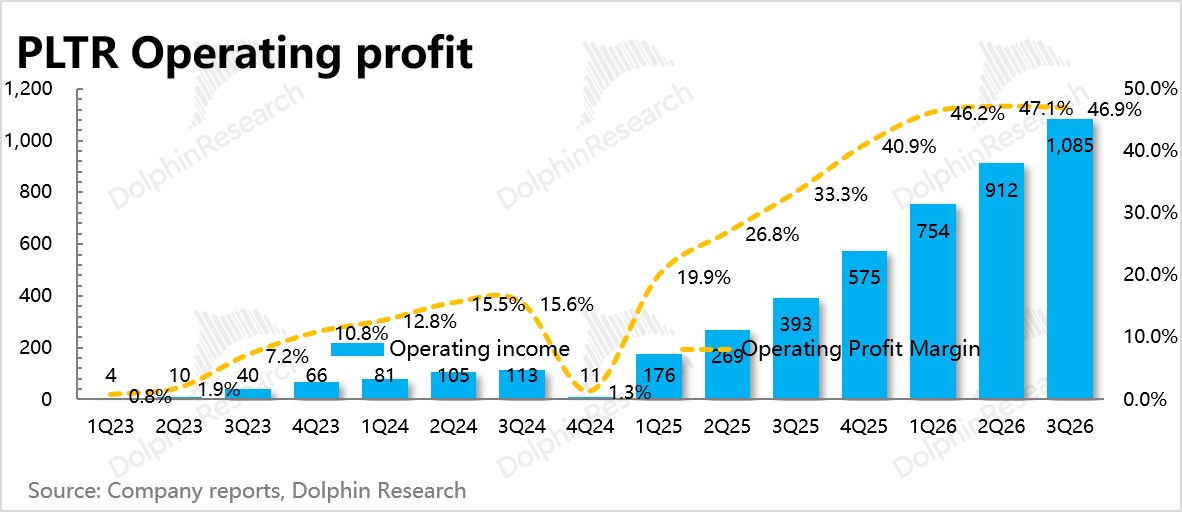
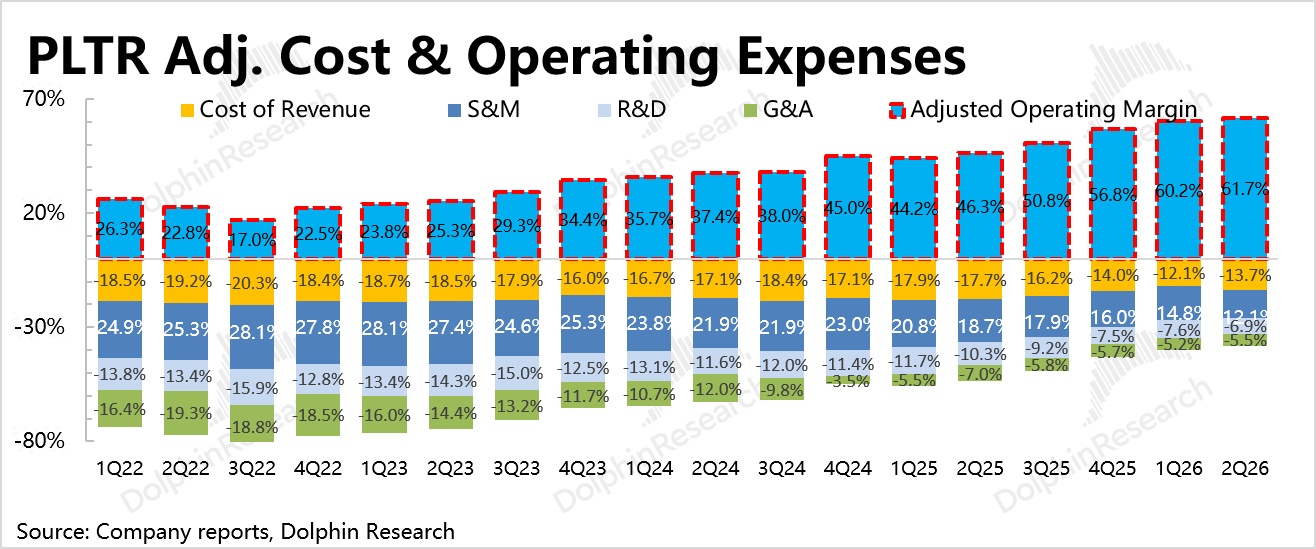
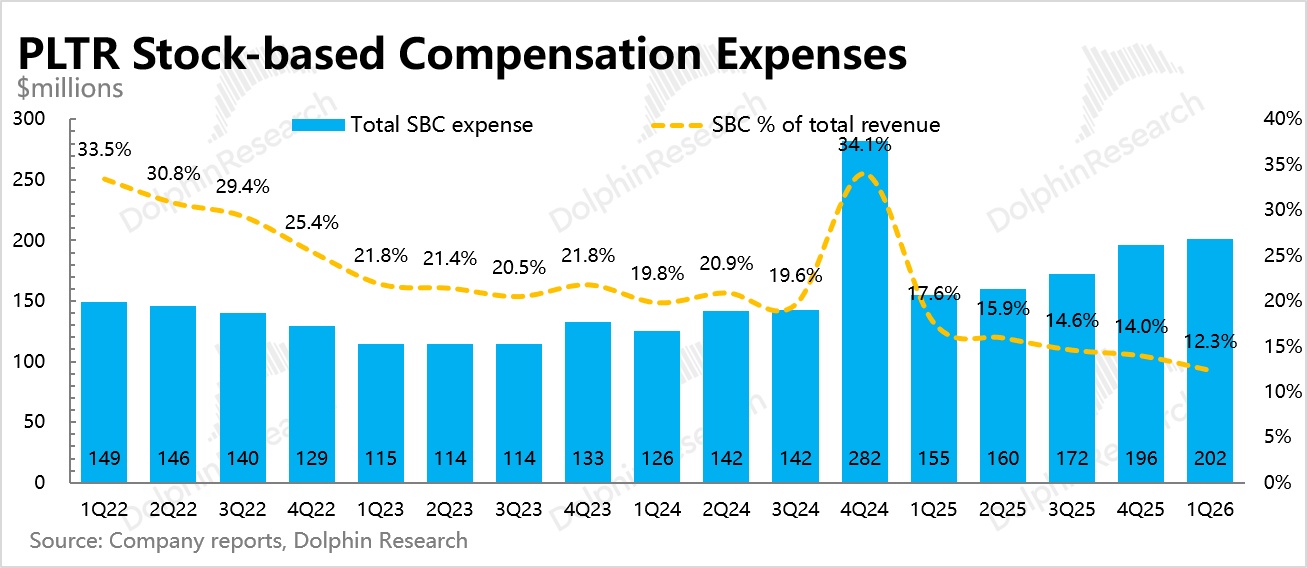
3. Margins steady for now: Q3 GPM slipped slightly QoQ, while opex remained disciplined and optimized. Ex-SBC, OPM was flat QoQ, effectively stable. Given the high-growth phase, minor intra-quarter slowdowns are not a big concern, and even with incremental competition, there is no need yet to step up spending to a level that would dent margins.
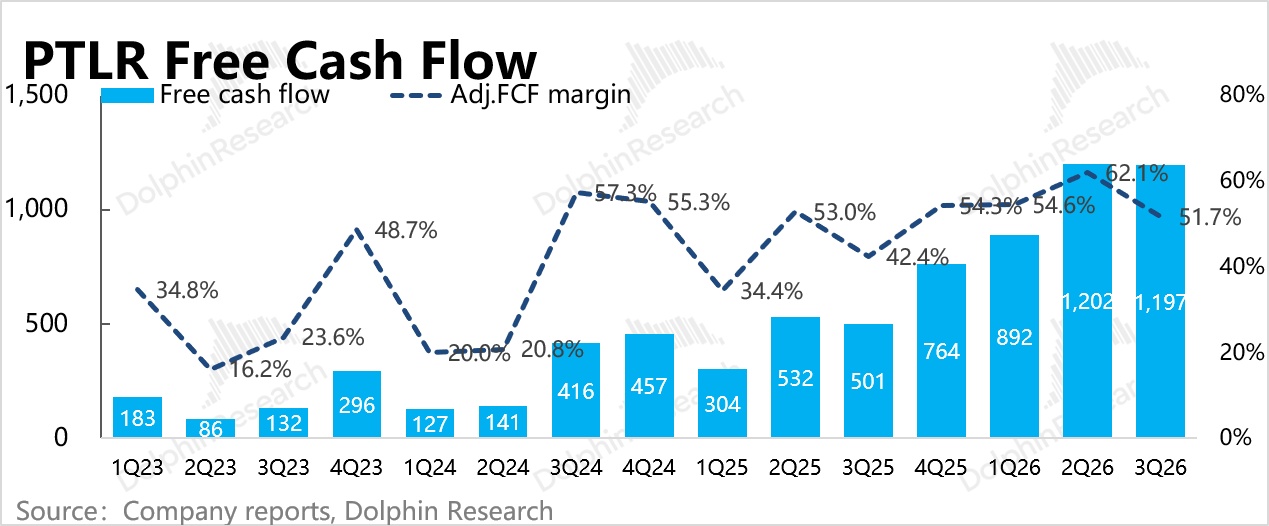
Cash flow is tied to contract cash collections, so there is seasonality. In Q3, collections were strong, especially on existing backlog; however, slower new bookings had some impact, leaving cash flow roughly flat at a high level. Mgmt guided full-year cash flow of $4.8–5.0bn. Cash plus short-term investments reached $10.5bn by quarter-end.
4. Earnings call Trans: Palantir (Trans): US Commercial First Tops Gov., FY Guide Raised Again
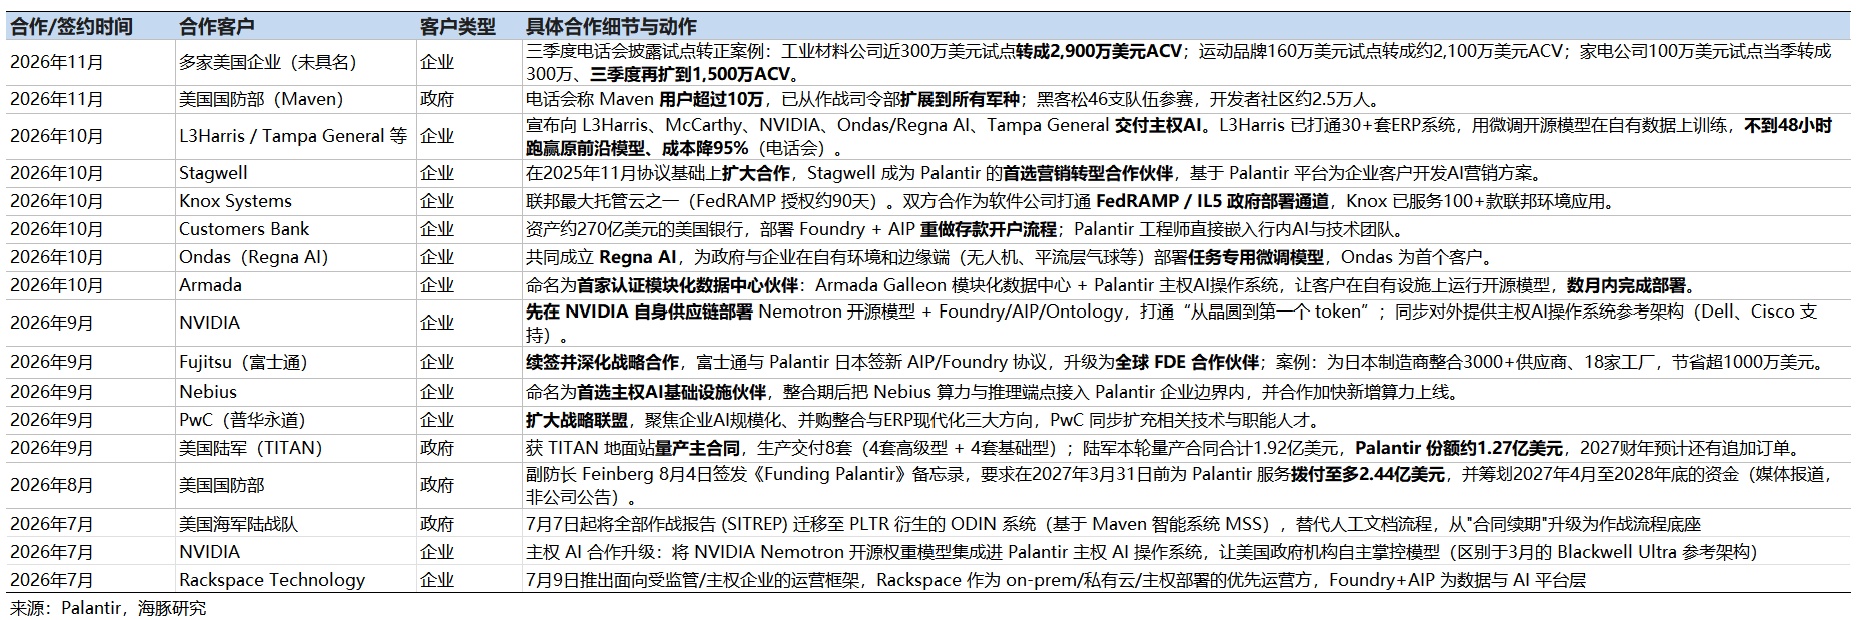
5. KPI snapshot & in-quarter ecosystem updates
Dolphin Research View
Overall, PLTR’s near-term fundamentals remain intact, but the slowdown in new bookings will be a target for bears. Some of the deceleration likely reflects seasonality and sales-cycle dynamics, with last quarter boosted by AIPCon 10. Meanwhile, faster drawdown of backlog and stronger renewals from existing customers highlight the competitiveness of PLTR’s offerings; once core users experience the product, conversion tends to deepen.
That said, the shift toward shorter initial terms among new customers warrants attention to AI-driven competitive dynamics. Especially among frontier AI labs and traditional software vendors with strong enterprise channels. OpenAI, Anthropic and Microsoft are typical examples, and since this year they have been piloting FDE-style engagement to mirror PLTR’s playbook.
We believe competition has yet to materially affect PLTR, as there remains a meaningful gap in practical utility. While PLTR is known for its FDE (forward-deployed) model, it is not dependent on FDE alone. PLTR’s FDE is not simple manpower scaling, but a closed-loop between deployment teams, product development, ontology building, and platform verticalization, with AI FDE and AIP Evolve turning deployment intelligence into code.
In practice, PLTR channels industry-specific know-how from deployments back into the platform, codifying it as reusable software and platform knowledge, embedding single-client learnings across the product for rapid replication across peers. This differs from many AI model/agent sales motions that emphasize client-specific deployment without systematic knowledge backflow.
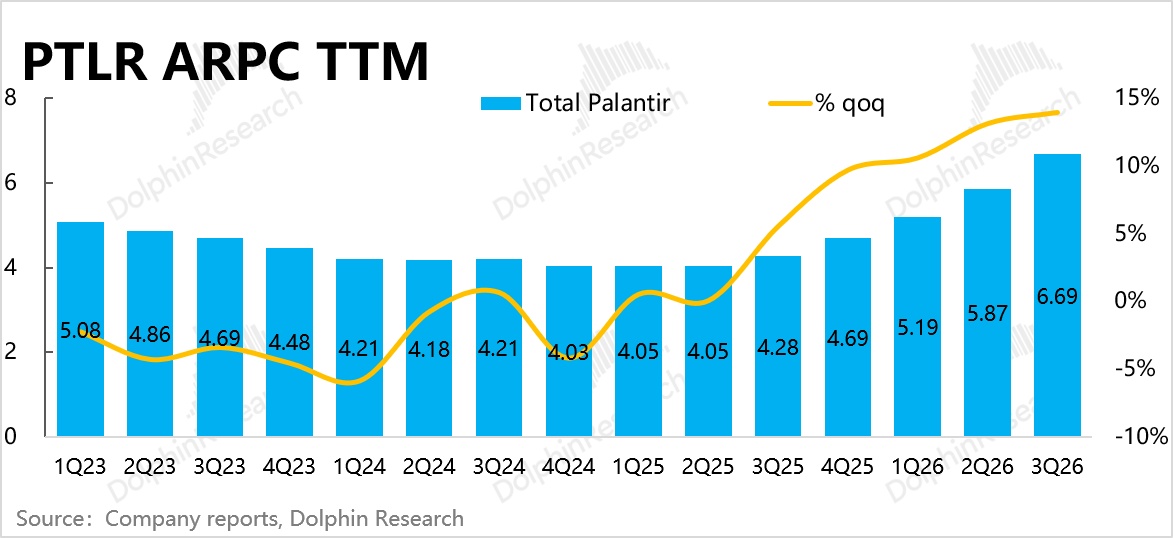
Thus, we see limited substitution risk on core demand near term, but some non-core use cases could face cost-based substitution via AI. PLTR’s LTM ARPC reached $6.69mn and rose another 14% QoQ in Q3. With expectations full and valuation rich (implied 2027 PS 35x, GAAP P/E 84x), any sustained bookings slowdown potentially tied to competition could weigh on bullish sentiment at these multiples.
Risk disclosure and statement: Dolphin Research Disclaimer & General Disclosure
Dolphin Research 'Palantir' historical coverage:
Earnings
Aug 4, 2026 Call Trans: Palantir (Trans): US Commercial Growth Expected to Sustain Q2 Pace Through YE Next Year
Aug 4, 2026 Post-earnings note: Palantir: Flaws Fixed, Is the Belief Stock Back in Full?
May 5, 2026 Call Trans: Palantir (Trans): Focused on Differentiated Custom Enterprise Service and True Autonomy, Unlike Legacy Software and Theoretical AI
May 5, 2026 Post-earnings note: Palantir: Software Doom Narratives Swell — Cracks Even in the Strongest Belief Stock?
Deep dives
Oct 13, 2023: Palantir: What Justifies the Premium Multiple?
Sep 26, 2023: Palantir: The 'Mysterious' Military Weapon Activated by AI
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.