


Tesla Q1 Preview: Tesla Deliveries, Margins Key as AI Spending Rises


Tesla is set to release its first-quarter 2026 earnings report on April 22.
Here’s Tiger Trade’s take on what to look for in Tesla’s earnings and the outlook for its stock.
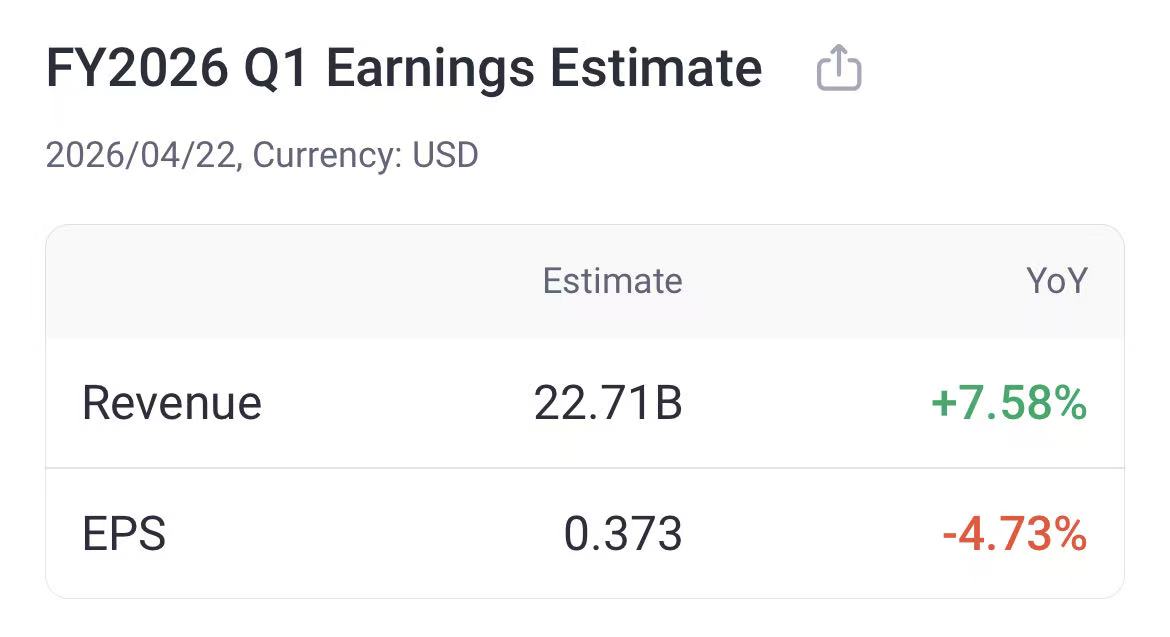
Tesla's Q1 revenue is expected to be $22.71B, up 7.58% YoY
EPS is projected at $0.373, down 4.73% YoY
 Tiger Trade
Tesla's Q4 Results and Q1 Deliveries
Tesla concluded fiscal 2025 with a resilient Q4, reporting revenue of $24.9 billion, surpassing analyst estimates of $24.7 billion. Despite pricing pressures in the automotive sector, the company delivered non-GAAP EPS of $0.50, beating the consensus estimate of $0.44.
A major highlight was the Energy Generation & Storage segment, which saw revenue grow 25% year-over-year (YOY) as deployments reached record levels. On a GAAP basis, the company posted net income of $840 million, maintaining its streak of profitability while generating $1.4 billion in free cash flow to fund its ambitious AI and robotics roadmap.
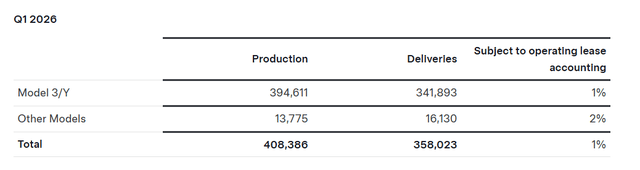
Looking to the first quarter, Tesla recently reported Q1 2026 deliveries of 358,023 vehicles. That fell slightly short of the 365,000 vehicle consensus estimate but still reflected a 6% YOY increase.
 With more than $44 billion in total cash as of Q4, Tesla is aggressively scaling its "unboxed" manufacturing process for the Cybercab. While near-term margins remain under pressure due to R&D spending, the company’s focus is squarely on its evolution into a high-margin, software-driven "physical AI" powerhouse.
Capital Expenditures to More Than Double to Invest in Physical AI
Tesla has admitted that it has transitioned from being “hardware centric” to becoming “a physical AI Company.” As well, in 2026 Tesla intends to increase growth through the addition of six new manufacturing lines covering vehicles, robotics, energy storage and battery technology.
Unfortunately, this new direction will require large amounts of capital: according to Tesla's 10-K filing, in 2026 its CapEx will be over $20 billion but Terafab - the planned 1-terawatt AI compute facility - was explicitly excluded from that figure. If fully realised, Terafab could cost in the mid-single-digit trillions, a number that dwarfs Tesla's entire automotive revenue base. Reuters and Bloomberg are already reporting that Musk's team has contacted multiple suppliers, suggesting plans are moving beyond concept. Combined with 100 GW of solar capacity ambitions, the investment cycle now extends well beyond what the auto business can fund through operations. Expect management commentary on Terafab phasing and funding to move the stock more than the revenue line.
The Autonomy-to-Revenue Timeline
Tesla's real inflection point as the transition from automotive to physical AI - spanning Robotaxi scaling, FSD monetisation, and Optimus production ramp. But limited concrete progress on autonomy timelines over recent months has weighed on the stock and kept investors cautious. The earnings call will be closely parsed for updated guidance on commercial Robotaxi rollout dates, FSD take-rate data, and Optimus unit economics.
Auto Margin Is A Key Metric
Tesla generated an impressive 17.9% automotive ex-credit non-GAAP margin in Q4 '25. Automotive margins could see modest upside from Tesla's shift to subscription-only pricing for Full Self-Driving. Investors will focus on early demand signals as US gasoline prices approach $4 per gallon. Tesla exited 4Q with sequential improvement in automotive gross margin ex-credits, though management has flagged persistent pressure from competition, tariffs and elevated product-development spending.

What Do Wall Street Analysts Say
Tesla’s upcoming earnings preview highlights a period of significant transition, with analysts forecasting a significant YOY increase in Q1 earnings as the company pivots toward its robotaxi future. TSLA stock currently earns a consensus "Hold" rating based on 30 analysts with coverage, featuring a wide split of 13 "Strong Buy" ratings, 11 “Hold” ratings, and 6 "Sell" ratings. With a mean price target of $401.13, TSLA stock offers potential upside of nearly 3% from current levels.
The long-term robotics and AI thesis remains compelling for Tesla. However, investors may face near-term volatility as the market weighs high capital expenditures against cooling EV delivery growth.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.