


 Discount


KLA Corp Stock (KLAC) Closed Down by 10.19% on Nov 20: Facts Behind the Movement


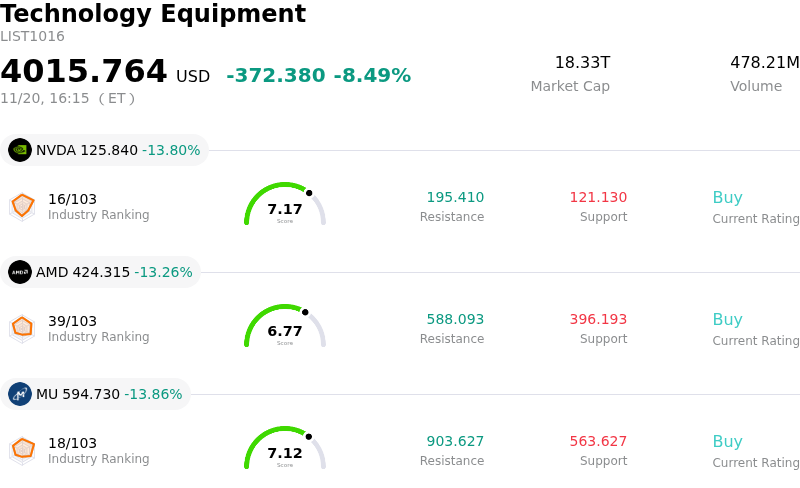
KLA Corp (KLAC) closed down by 10.19%. The Technology Equipment sector is down by 8.49%. The company underperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 13.80%; Advanced Micro Devices Inc (AMD) down 13.26%; Micron Technology Inc (MU) down 13.86%.
What is driving KLA Corp (KLAC)’s stock price down today?
KLA Corporation experienced severe downward pressure during the trading session, driven primarily by intensified concerns surrounding global wafer fabrication equipment spending and potential regulatory headwinds. As the dominant leader in semiconductor process control and yield management solutions, the company is highly sensitive to the capital expenditure cycles of leading foundry, logic, and memory manufacturers. Emerging indications of delayed fab expansions and deferred equipment procurement among Tier-1 chipmakers have triggered a swift reassessment of forward revenue trajectories for critical metrology and inspection platforms.
Compounding this cautious stance are renewed anxieties regarding international trade restrictions and export controls on advanced semiconductor tools. Given the company's notable operational exposure to capacity expansion programs in mainland China, heightened regulatory scrutiny over advanced packaging and process diagnostics creates immediate uncertainty around backlog conversion. Investors are increasingly pricing in the threat of order pushouts and restricted market access, which directly challenges a historically resilient source of high-margin tool shipments and related recurring service revenue.
Broader weakness across the semiconductor capital equipment sector has also intensified institutional selling. Cautious forward commentary from peer equipment suppliers and softer utilization metrics across mature nodes have heightened fears that a broad-based industry recovery is taking longer to materialize than previously anticipated. Because the company trades at a premium valuation multiple justified by its exceptional operating margins and dominant competitive moat, any evidence of deceleration in high-end optical inspection demand inevitably prompts aggressive multiple compression and risk offloading by asset managers.
From an institutional perspective, while the company maintains an indispensable structural role in enabling leading-edge gate-all-around architectures and advanced multi-die packaging, near-term risk-reward dynamics remain tilted toward caution. Key factors to watch over the coming weeks include revisions to customer capital budgets, order book cancellation rates, and further regulatory clarifications regarding cross-border equipment shipments. Until tangible stabilization in wafer fab equipment spending emerges, shares are expected to remain sensitive to macroeconomic sentiment and elevated industry volatility.
Technical Analysis of KLA Corp (KLAC)
Technically, KLA Corp (KLAC) shows a MACD (12,26,9) value of -1.339, indicating a sell signal. The RSI at 32.873 suggests neutral condition and the Williams %R at 99.329 suggests oversold condition. Please monitor closely.
Fundamental Analysis of KLA Corp (KLAC)
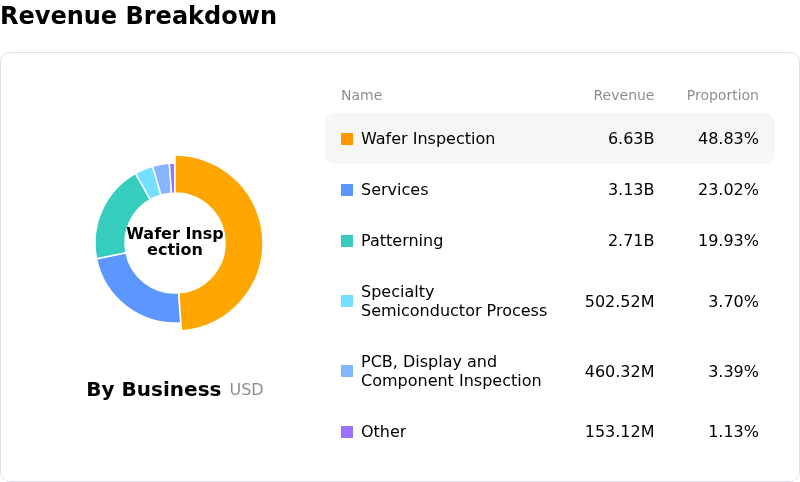
KLA Corp (KLAC) is in the Technology Equipment industry. Its latest annual revenue is $13.58B, ranking 15 in the industry. The net profit is $4.83B, ranking 11 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $214.38, a high of $275.00, and a low of $138.80.
More details about KLA Corp (KLAC)
Company Specific Risks:
- Elevated China Revenue Concentration Under Regulatory Threat: KLA derives approximately 34.5% of its quarterly revenue from mainland China, leaving its top line heavily exposed to imminent revenue impairment as renewed policy discussions around tighter U.S. Department of Commerce export controls on advanced semiconductor equipment threaten cross-border tool shipments.
- Wafer Fab Equipment Capex Pacing and Pushout Risks: Institutional analysts are highlighting growing risks of near-term capital expenditure pacing adjustments and cleanroom installation delays among leading foundry, logic, and memory clients, which directly threatens the delivery schedule and revenue recognition cadence for KLA's high-margin optical inspection and metrology tools.
- Multiple Vulnerability Amid AI Hardware Reassessment: With the stock trading at a sharp valuation premium exceeding 9.3x forward sales, KLA faces sustained multiple compression and price-target reductions from institutional desks as the market recalibrates expectations around the sustainability and monetization speed of AI-driven equipment backlogs.
- Persistent Executive Insider Selling Sentiment Overhang: Continued open-market divestment by top executive leadership—highlighted by large multi-million dollar equity sales from both Chief Executive Officer Richard Wallace and Chief Financial Officer Bren Higgins alongside zero insider purchases—continues to weigh heavily on institutional market sentiment during sector downturns.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.