


 Discount


Intel Corp Stock (INTC) Moved Down by 4.91% on Nov 20: Drivers Behind the Movement


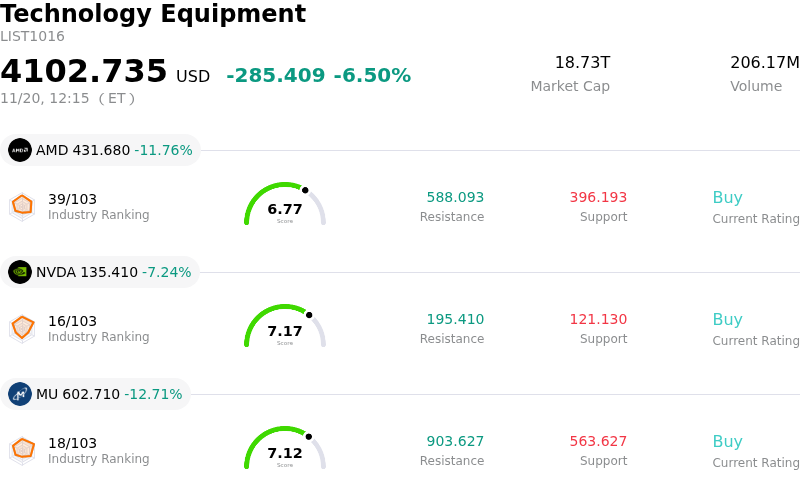
Intel Corp (INTC) moved down by 4.91%. The Technology Equipment sector is down by 6.50%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Advanced Micro Devices Inc (AMD) down 11.52%; NVIDIA Corp (NVDA) down 7.20%; Micron Technology Inc (MU) down 12.81%.
What is driving Intel Corp (INTC)’s stock price down today?
Intel faced notable downward pressure during the trading session as a confluence of structural industry headwinds, competitive challenges, and cautious institutional sentiment weighed heavily on the shares. A broader pullback across the semiconductor sector, coupled with risk-off positioning toward capital-intensive turnaround stories, triggered selling momentum. Investors increasingly favored peers with more direct and unencumbered exposure to next-generation artificial intelligence accelerators, leaving legacy architecture providers vulnerable to portfolio reallocations.
A primary fundamental concern remains the operational and financial drag associated with the company’s ambitious foundry roadmap. Market participants continue to scrutinize the substantial capital expenditures required to advance leading-edge process nodes against the reality of extended profitability timelines. Lingering uncertainty regarding high-volume external customer commitments and manufacturing yield progression has kept free cash flow visibility constrained. This high capital intensity restricts near-term balance sheet flexibility and creates persistent skepticism among institutional investors who are prioritizing near-term margin expansion.
Competitive dynamics across core business segments have added further pressure. In the data center domain, aggressive product cadence from direct rivals alongside the rapid adoption of internal custom silicon by major cloud hyperscalers continues to threaten server market share and erode pricing power. At the same time, the client computing franchise is navigating intensifying rivalry from competing architectures in the enterprise and consumer PC spaces. This dual-front competitive pressure raises concerns over the sustainability of volume recovery and gross margin trajectory.
Recent analyst sentiment has mirrored these operational realities, with several research desks maintaining a guarded stance regarding the timing and efficacy of the turnaround strategy. Heightened caution surrounding node transition schedules, paired with sensitive enterprise IT spending, leaves the shares susceptible to sharp pullbacks. Until the company can demonstrate sustained manufacturing yield improvements, announce major third-party foundry customer milestones, and decisively stem market share attrition in enterprise computing, the stock remains vulnerable to elevated volatility and discounted valuation multiples.
Technical Analysis of Intel Corp (INTC)
Technically, Intel Corp (INTC) shows a MACD (12,26,9) value of 0.959, indicating a neutral signal. The RSI at 29.145 suggests sell condition and the Williams %R at 87.884 suggests oversold condition. Please monitor closely.
Media Coverage of Intel Corp (INTC)
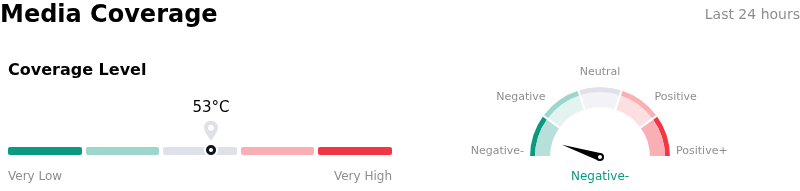
In terms of media coverage, Intel Corp (INTC) shows a coverage score of 53, indicating a moderate level of media attention. The overall market sentiment index is currently in extremely bearish zone.
Fundamental Analysis of Intel Corp (INTC)
Intel Corp (INTC) is in the Technology Equipment industry. Its latest annual revenue is $52.85B, ranking 6 in the industry. The net profit is $-267.00M, ranking 111 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Hold, with an average price target of $91.99, a high of $160.00, and a low of $63.00.
More details about Intel Corp (INTC)
Company Specific Risks:
- Uncertainty Over External Foundry Economics: An intraday rally faded sharply after Intel announced securing its first external customer for its 18A-P manufacturing node without disclosing the client's identity, order volume, deal valuation, or commercialization timeline, intensifying analyst skepticism regarding the foundry division's profitability and near-term revenue contribution.
- Strategic Divestment by Major Stakeholder: Recent regulatory 13-F disclosures confirmed that Nvidia reduced its Intel equity position by 25% (liquidating over 53 million shares down to 161.1 million), signaling waning institutional confidence and exerting sustained selling pressure on the stock.
- Federal Securities Litigation Over Concealed Demand Slump: A newly filed shareholder class action lawsuit in federal court claims executive leadership failed to disclose significant channel inventory gluts, rising component costs, and severe weakness in Client Computing demand prior to Intel's recent revenue guidance cut.
- Persistent Server CPU Market Share Erosion: Recent institutional research reports highlighted ongoing market share loss in high-margin data center and server processors to AMD and ARM-based architectures, heightening margin compression risks alongside heavy 18A development costs and underutilized fabrication capacity.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.