


 Discount


ASML Holding NV Stock (ASML) Moved Down by 4.24% on Nov 20: Drivers Behind the Movement


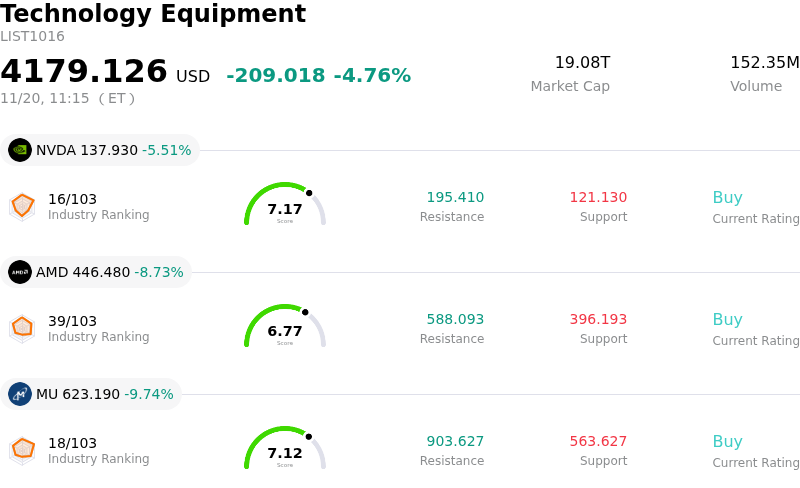
ASML Holding NV (ASML) moved down by 4.24%. The Technology Equipment sector is down by 4.76%. The company outperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 5.63%; Advanced Micro Devices Inc (AMD) down 8.94%; Micron Technology Inc (MU) down 9.94%.
What is driving ASML Holding NV (ASML)’s stock price down today?
ASML experienced noticeable downside pressure during the session, weighed down by a confluence of industry-wide semiconductor capital expenditure caution and broader valuation compression across the technology sector. With risk-off sentiment emerging in global equity markets, high-multiple semiconductor equipment manufacturers faced amplified selling momentum as institutional investors reassessed the near-term cadence of wafer fab equipment spending.
A primary catalyst dampening investor sentiment revolves around ongoing capital expenditure discipline among tier-one foundries and memory manufacturers. As leading chipmakers calibrate their capacity additions to address near-term demand pockets while pacing broader capacity buildouts, scrutiny surrounding the velocity of advanced extreme ultraviolet and deep ultraviolet tool deliveries has intensified. Worries over the timing of backlog conversion and potential order pushouts in both leading-edge and mature nodes have prompted market participants to trim exposure to long-cycle equipment suppliers.
Geopolitical and regulatory overhangs continue to serve as a recurring source of volatility for the company. Persistent uncertainty regarding international trade policies and export control restrictions on advanced semiconductor manufacturing technology has kept investors on edge. Potential headwinds affecting shipments and recurring servicing revenue in key regional markets, particularly Greater China, contribute to a cautious outlook regarding the company's addressable market outside of core AI-driven hardware spending.
From an institutional perspective, while ASML retains a formidable competitive moat and an irreplaceable position in next-generation lithography critical for artificial intelligence and high-performance computing, near-term valuation remains sensitive to cyclical equipment digestion. Portfolio managers are exercising tactical prudence, awaiting clearer confirmation of accelerated fab utilization and re-accelerated booking momentum before stepping back into the stock with high conviction.
Technical Analysis of ASML Holding NV (ASML)
Technically, ASML Holding NV (ASML) shows a MACD (12,26,9) value of -26.707, indicating a sell signal. The RSI at 30.305 suggests neutral condition and the Williams %R at 94.649 suggests oversold condition. Please monitor closely.
Fundamental Analysis of ASML Holding NV (ASML)
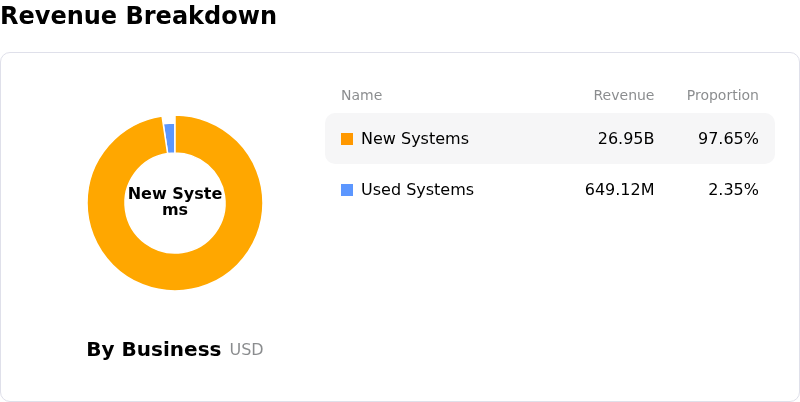
ASML Holding NV (ASML) is in the Technology Equipment industry. Its latest annual revenue is $36.83B, ranking 8 in the industry. The net profit is $10.83B, ranking 7 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $2203.99, a high of $2858.00, and a low of $1450.00.
More details about ASML Holding NV (ASML)
Company Specific Risks:
- Geopolitical and Export Restriction Escalation: Tightening multilateral export controls from the U.S. and Dutch governments threaten ASML's deep ultraviolet (DUV) immersion lithography shipments to China, jeopardizing a market segment that has historically accounted for over a quarter of net system sales.
- Installed Base Management Service Vulnerability: Regulatory curbs extending to maintenance, servicing, and spare parts supply for previously delivered equipment in restricted regions risk eroding high-margin, recurring Installed Base Management revenue streams.
- Leading-Edge Logic and Memory Capex Deferrals: Key semiconductor foundry and memory clients are adjusting capital expenditure timelines in non-AI segments, prompting delivery delays for low-NA and high-NA extreme ultraviolet (EUV) systems that threaten net order intake momentum.
- Operating Deleverage and Margin Compression: Near-term gross margin performance faces downward pressure due to elevated manufacturing and R&D costs associated with High-NA EUV ramp-ups while tool delivery schedules fluctuate under volatile customer fab readiness timelines.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.