


 Discount


SanDisk Corporation Stock (SNDK) Moved Down by 3.30% on Nov 18: What Signal Does It Send?


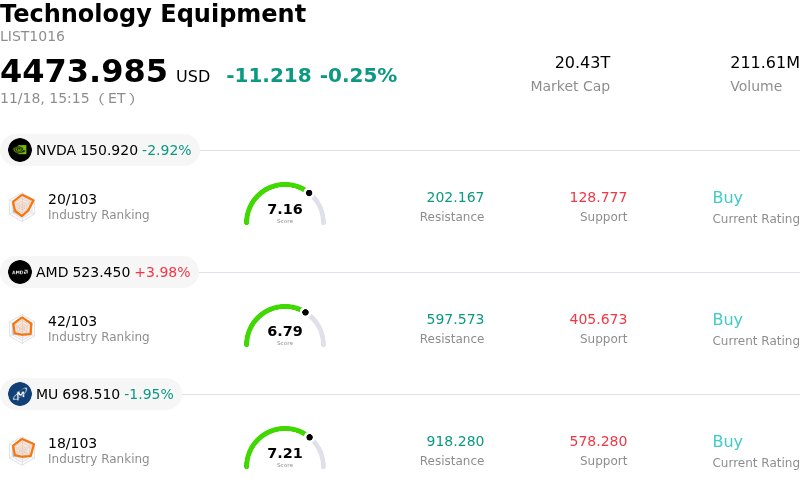
SanDisk Corporation (SNDK) moved down by 3.30%. The Technology Equipment sector is down by 0.25%. The company underperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 2.84%; Advanced Micro Devices Inc (AMD) up 3.98%; Micron Technology Inc (MU) down 1.99%.
What is driving SanDisk Corporation (SNDK)’s stock price down today?
Sandisk experienced notable downward pressure during the trading session, driven primarily by widespread softness across semiconductor and artificial intelligence hardware equities. A broad-based rotation out of momentum-driven technology infrastructure names weighed heavily on memory and storage providers, with peer chipmakers sharing similar intraday declines. Heightened market sensitivity regarding the pace of ongoing capital expenditure among enterprise data center operators has prompted institutional desks to trim high-beta technology exposures, creating an immediate headwind for the stock.
Compounding this intraday volatility is tactical positioning ahead of the company's scheduled eight-for-one stock split. Institutional investors and derivatives market participants frequently recalibrate risk exposures and rebalance books prior to major corporate actions, particularly as options markets prepare for operational pauses and strike-price adjustments. These mechanical capital shifts and hedging reallocations have introduced temporary order-flow imbalances, accelerating downside pressure during regular market hours.
From an industry and operational perspective, investor attention is shifting toward potential headwinds in the broader memory cycle. Despite substantial recent expansion in enterprise solid-state drive shipments, market sentiment is clouded by concerns over decelerating price momentum in the NAND flash segment and sequential demand moderation in retail consumer channels. Concurrently, persistent supply-chain concentration with key fabrication partners and longer-term competitive expansion from alternative global memory suppliers continue to induce multiple compression across the sector.
In summary, the recent pullback is the product of macro-level profit taking across semiconductor names, pre-split institutional liquidity adjustments, and heightened scrutiny over cyclical flash memory pricing. While structural demand for high-capacity AI storage remains robust over a multi-quarter horizon, near-term price discovery is likely to remain volatile until technical rebalancing flows subside and broader technology market sentiment stabilizes.
Technical Analysis of SanDisk Corporation (SNDK)
Technically, SanDisk Corporation (SNDK) shows a MACD (12,26,9) value of -17.856, indicating a sell signal. The RSI at 29.928 suggests sell condition and the Williams %R at 95.643 suggests oversold condition. Please monitor closely.
Media Coverage of SanDisk Corporation (SNDK)
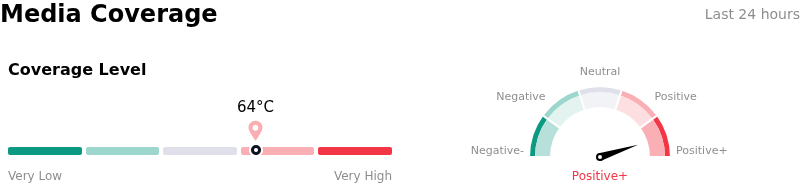
In terms of media coverage, SanDisk Corporation (SNDK) shows a coverage score of 64, indicating a high level of media attention. The overall market sentiment index is currently in extremely bullish zone.
Fundamental Analysis of SanDisk Corporation (SNDK)
SanDisk Corporation (SNDK) is in the Technology Equipment industry. Its latest annual revenue is $20.25B, ranking 8 in the industry. The net profit is $11.43B, ranking 2 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $2024.13, a high of $3000.00, and a low of $1020.00.
More details about SanDisk Corporation (SNDK)
Company Specific Risks:
- NAND Price Forecast Downgrades and Looming Oversupply: GF Securities downgraded its NAND pricing outlook, warning of an impending market glut as early as next year and revising expectations from sequential price growth to flat pricing in Q1 followed by sustained declines, primarily driven by a sharp contraction in non-AI demand.
- Severe Spot Price Erosion and Gross Margin Pressure: TrendForce and industry tracking data show that NAND spot prices have dropped 20% over the past two weeks, with 512Gb wafer pricing plunging 32% sequentially, signaling rapid deceleration in average selling prices (ASPs) that directly threatens Sandisk's premium gross margins.
- Aggressive Competitor Capacity Expansion by YMTC: Market oversupply concerns are intensifying as Yangtze Memory Technologies Corp (YMTC) aggressively expands its production and supply targets for next year, creating structural headwinds that limit pricing power across client and enterprise SSD markets.
- Wafer Supply Concentration and Weakening Consumer Demand: Sandisk remains heavily dependent on joint-venture partner Kioxia for nearly all of its wafer supply at a time when Kioxia's profit forecast has missed consensus, compounding risks from Sandisk's recent 29% sequential drop in consumer segment revenue.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.