


 Discount


Qualcomm Inc Stock (QCOM) Moved Down by 3.02% on Nov 18: Facts Behind the Movement


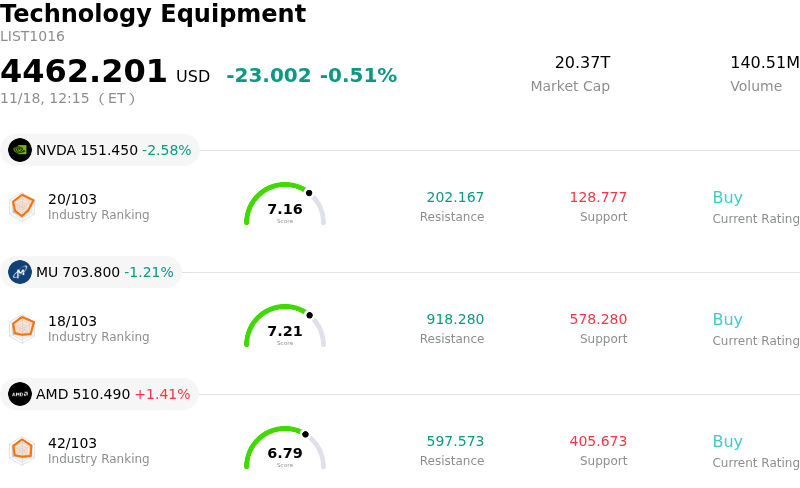
Qualcomm Inc (QCOM) moved down by 3.02%. The Technology Equipment sector is down by 0.51%. The company underperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 2.62%; Micron Technology Inc (MU) down 1.22%; Advanced Micro Devices Inc (AMD) up 1.41%.
What is driving Qualcomm Inc (QCOM)’s stock price down today?
Qualcomm faced notable selling pressure during the session, driven by broad-based weakness across the semiconductor complex and renewed scrutiny over the pace of demand recovery in the global smartphone ecosystem. Market participants remain sensitive to consumer spending trends, particularly across key international markets where handset replacement cycles have yet to exhibit a robust, broad-based acceleration. While the market has previously priced in substantial optimism around on-device generative artificial intelligence and new edge computing architectures, near-term order visibility among major original equipment manufacturers remains cautious, dampening expectations for immediate volume expansion.
Compounding this cautious macro backdrop are ongoing concerns regarding competitive dynamics and long-term customer concentration. Investors continue to monitor the terminal impact of Apple’s eventual transition toward proprietary cellular modems, which poses a persistent structural headwind to Qualcomm’s core baseband revenue over the multi-year horizon. Simultaneously, competitive pressure from rivals in the flagship and upper-mid-tier Android categories threatens to limit pricing power and operating margin expansion. While Qualcomm has demonstrated solid execution in diversifying its revenue base toward automotive platforms, connected IoT devices, and next-generation PC silicon, these growth pillars are not yet large enough to fully insulate the company’s bottom line from cyclical swings in mobile handsets.
From an institutional standpoint, the pullback reflects tactical portfolio de-risking and valuation multiple compression amid broader technology sector consolidation. Portfolio managers appear reluctant to aggressively accumulate shares without definitive evidence of an accelerating high-margin licensing cycle and sustained market share gains in non-smartphone verticals. Until clear catalysts emerge to confirm that enterprise and consumer edge AI adoption can drive meaningful, high-margin revenue acceleration, Qualcomm's near-term trading is likely to remain constrained by the cyclical realities of the global handset market.
Technical Analysis of Qualcomm Inc (QCOM)
Technically, Qualcomm Inc (QCOM) shows a MACD (12,26,9) value of -0.882, indicating a sell signal. The RSI at 41.344 suggests neutral condition and the Williams %R at 61.451 suggests sell condition. Please monitor closely.
Media Coverage of Qualcomm Inc (QCOM)
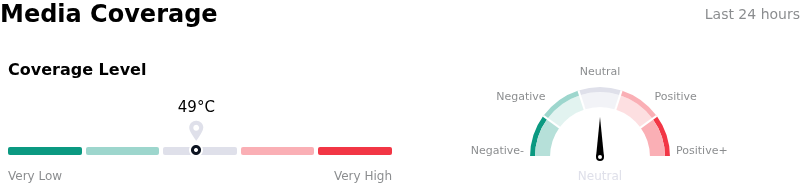
In terms of media coverage, Qualcomm Inc (QCOM) shows a coverage score of 49, indicating a moderate level of media attention. The overall market sentiment index is currently in neutral zone.
Fundamental Analysis of Qualcomm Inc (QCOM)
Qualcomm Inc (QCOM) is in the Technology Equipment industry. Its latest annual revenue is $43.12B, ranking 7 in the industry. The net profit is $13.63B, ranking 6 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Hold, with an average price target of $0.00, a high of $0.00, and a low of $0.00.
More details about Qualcomm Inc (QCOM)
Company Specific Risks:
- U.S. Export Controls Severing ByteDance AI Deal: Baird reduced Qualcomm's price target after stripping an anticipated custom ASIC design engagement with ByteDance from its model, citing U.S. government export control restrictions that ban AI chip collaboration and funding with the TikTok parent firm.
- Accelerating Apple Modem Phase-Out: Management's recent outlook confirms that revenue from Apple's handset modem sockets is actively winding down as internal replacement chips ramp, eliminating Qualcomm's historical December holiday seasonal strength and leaving core handset sales vulnerable.
- Operating Margin Compression and Rising Input Costs: Near-term guidance signals QCT pre-tax margins contracting to 20%–22% (down from 24%–26%), weighed down by elevated semiconductor input costs and the gross-margin-dilutive transition into custom data center silicon.
- Balance Sheet Leverage and Institutional Divestment: Qualcomm's filing of a $4 billion multi-tranche senior debt offering has increased leverage concerns, compounding selling pressure alongside major institutional stake cuts and technical breakdown below the 200-day moving average.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.