


 Discount


KLA Corp Stock (KLAC) Moved Down by 3.68% on Nov 16: Facts Behind the Movement


KLA Corp (KLAC) moved down by 3.68%. The Technology Equipment sector is down by 2.95%. The company underperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 2.85%; Micron Technology Inc (MU) down 5.81%; Apple Inc (AAPL) down 0.78%.
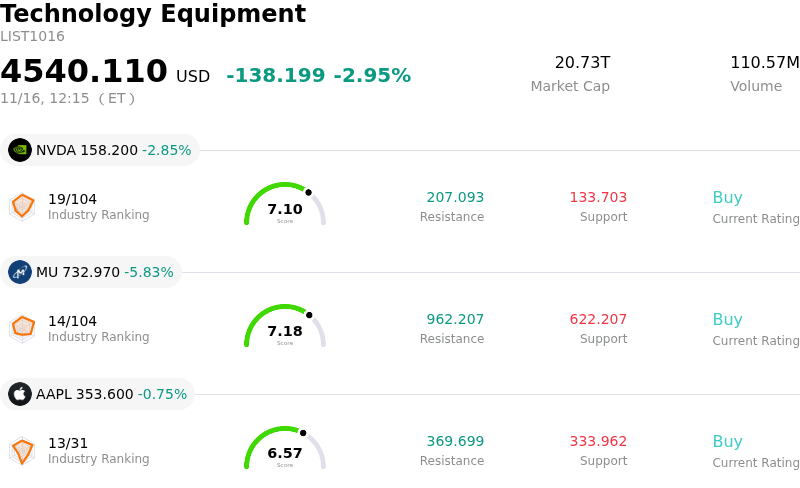
What is driving KLA Corp (KLAC)’s stock price down today?
KLA Corporation encountered notable downward pressure during the trading session, reflecting a broader pullback across the semiconductor capital equipment sector. As market sentiment shifted toward risk aversion, high-multiple semiconductor equipment names experienced synchronized selling, driven by macro crosscurrents and heightened scrutiny over near-term wafer fab equipment spending trajectories. Investors frequently treat process diagnostic and metrology providers as high-beta barometers of global chipmaking expansion, making the stock particularly vulnerable to sector-wide profit-taking.
A primary fundamental headwind centers on capital expenditure cadence among top-tier foundry, logic, and memory manufacturers. While long-term demand for advanced packaging, gate-all-around architectures, and high-bandwidth memory remains robust, near-term capacity additions face timing adjustments. Institutional participants are actively reassessing whether leading chipmakers will pace their equipment deliveries into subsequent quarters to balance current inventory and fab buildout schedules. Because KLA generates substantial revenue from advanced optical inspection and electron-beam metrology tied directly to yield ramp phases, any indication of pushouts in fab tool installation schedules dampens immediate revenue visibility.
Geopolitical uncertainties and cross-border trade restrictions continue to introduce persistent friction for the wafer fab equipment cohort. Heightened export oversight regarding advanced semiconductor tools shipped to foreign markets, particularly China, remains a key overhang for equipment providers. Given that trailing-edge capacity investments in China have represented a meaningful tailwind for process control tools in recent operating cycles, market participants remain cautious about the sustainability of these orders amid tightening regulatory scrutiny and licensing bottlenecks.
Macroeconomic conditions and fixed-income market volatility have further exacerbated multiple compression across the semiconductor space. Fluctuations in benchmark bond yields often prompt institutional portfolio managers to rebalance away from premium-valuation technology leaders toward more defensive allocations. For KLA, which trades at a valuation reflecting its dominant market share and high gross margin profile, elevated discount rates mechanically compress forward price-to-earnings multiples.
Looking ahead, institutional focus remains anchored on the trajectory of foundry utilization rates, the resilience of memory recovery, and customer yield challenges at leading-edge nodes where process control intensity is structurally higher. Until market participants gain definitive evidence that customer capital expenditure commitments are accelerating rather than plateauing, KLA shares are likely to exhibit heightened sensitivity to broader macroeconomic data and peer-group earnings updates.
Technical Analysis of KLA Corp (KLAC)
Technically, KLA Corp (KLAC) shows a MACD (12,26,9) value of 2.411, indicating a neutral signal. The RSI at 42.008 suggests neutral condition and the Williams %R at 56.932 suggests sell condition. Please monitor closely.
Fundamental Analysis of KLA Corp (KLAC)
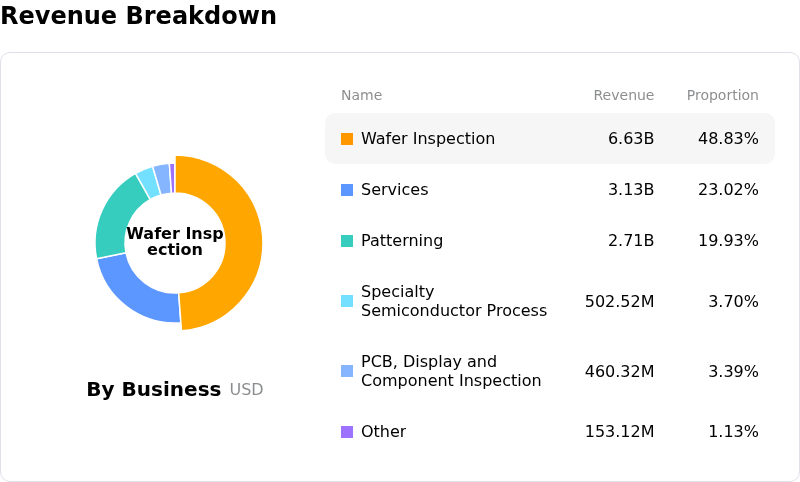
KLA Corp (KLAC) is in the Technology Equipment industry. Its latest annual revenue is $13.58B, ranking 15 in the industry. The net profit is $4.83B, ranking 11 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $214.38, a high of $275.00, and a low of $138.80.
More details about KLA Corp (KLAC)
Company Specific Risks:
- Sector-Wide Multiple Compression and Capex Sustainability Concerns: Recent earnings reactions and analyst commentary across peer semiconductor equipment manufacturers have catalyzed severe valuation compression, as institutional analysts cite heightened vulnerability across the wafer fab equipment cohort should artificial intelligence infrastructure spending decelerate or fail to sustain aggressive forward buildout expectations.
- Projected Chinese Revenue Contraction and Export Scrutiny: After China accounted for roughly 34.5% of quarterly revenue, forward guidance and industry projections signal a steep decline toward the low-20% range, compounded by ongoing U.S. export restrictions, border customs scrutiny on China-bound inspection tools, and accelerating domestic Chinese equipment substitution.
- Sustained Executive Insider Liquidations: Persistent insider disposal filings revealing millions of dollars in executive share liquidations against zero open-market insider purchases have dampened investor sentiment, reinforcing concerns among institutional market participants that the current equipment demand upcycle may be approaching a localized peak.
- Floating-Rate Debt Exposure Amid Capex Timing Vulnerability: Regulatory disclosures indicate heightened balance-sheet sensitivity following the conversion of $2.00 billion of fixed-rate notes into floating-rate liabilities via interest rate swaps, elevating financial carrying risks during an operating environment where customer capex deferrals could quickly compress equipment delivery schedules.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles











Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.