


Intel Corp Stock (INTC) Moved Down by 4.11% on Nov 12: Drivers Behind the Movement


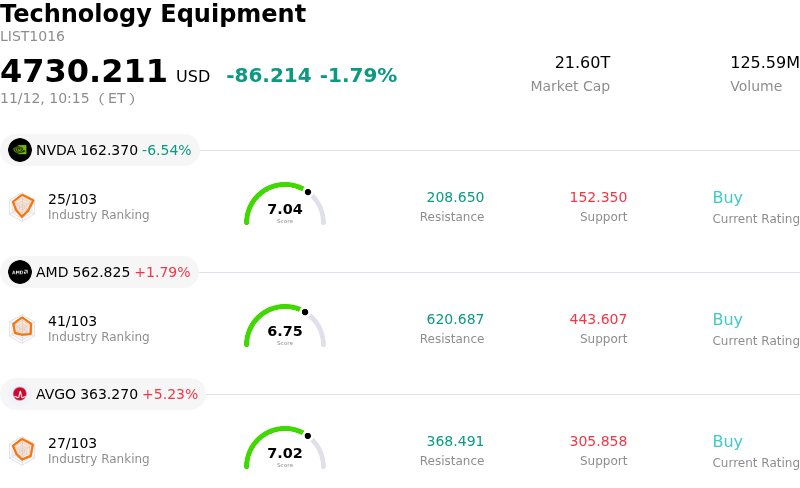
Intel Corp (INTC) moved down by 4.11%. The Technology Equipment sector is down by 1.79%. The company underperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 6.78%; Advanced Micro Devices Inc (AMD) up 1.33%; Broadcom Inc (AVGO) up 4.96%.
What is driving Intel Corp (INTC)’s stock price down today?
Intel experienced sharp downward pressure during the session, driven by a convergence of industry-wide semiconductor headwinds, persistent skepticism regarding the timeline of its foundry turnaround, and heightened competitive concerns in high-performance computing. Institutional investors appear increasingly cautious, reflecting a broader risk-off posture across cyclical hardware and capital-intensive technology names.
A key driver behind the decline stems from ongoing scrutiny of Intel Foundry. While the company continues to advance its process roadmap, the market remains fixated on execution risk, operational yields, and the substantial capital expenditures required to maintain parity with Asian foundry leaders. Investors are demanding clearer evidence of external customer wins and meaningful volume commitments to justify the elevated spending profile. In the absence of immediate margin accretion, the heavy depreciation burden continues to weigh on investor sentiment and intermediate profitability expectations.
Simultaneously, competitive pressures across core enterprise and data center segments remain intense. Hyperscalers and cloud service providers continue to prioritize artificial intelligence infrastructure, where rival accelerator platforms dominate capital deployment. In traditional server central processing units, market share dynamics remain unfavorable, with competitors leveraging architecture efficiencies to challenge Intel’s legacy dominance. Furthermore, the client computing segment faces a measured recovery trajectory, as enterprise refresh cycles for artificial intelligence personal computers ramp up more gradually than previously anticipated.
From a portfolio allocation standpoint, recent institutional repositioning suggests a rotation toward higher-margin semiconductor peers with clearer visibility into artificial intelligence monetization. Cautious commentary from Wall Street analysts, alongside subdued near-term earnings revision trends, has further capped upside momentum. Concerns regarding sustained free cash flow generation amidst multi-billion-dollar fabrication commitments continue to depress valuation multiples relative to the broader chip index.
Looking ahead, Intel’s trajectory hinges on its ability to demonstrate sustained manufacturing execution, improve operational gross margins, and secure high-profile third-party foundry agreements. Until the market sees tangible proof that foundry revenue can offset the headwinds in legacy compute markets, the stock is likely to remain subject to heightened volatility and range-bound institutional participation. Risk management remains paramount, with close attention warranted on upcoming supplier checks, capital allocation updates, and enterprise IT spending forecasts.
Technical Analysis of Intel Corp (INTC)
Technically, Intel Corp (INTC) shows a MACD (12,26,9) value of -1.730, indicating a sell signal. The RSI at 32.640 suggests neutral condition and the Williams %R at 80.960 suggests oversold condition. Please monitor closely.
Media Coverage of Intel Corp (INTC)
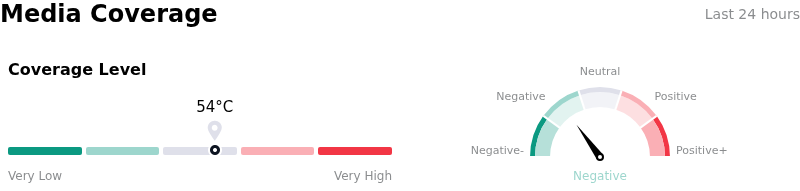
In terms of media coverage, Intel Corp (INTC) shows a coverage score of 54, indicating a moderate level of media attention. The overall market sentiment index is currently in bearish zone.
Fundamental Analysis of Intel Corp (INTC)
Intel Corp (INTC) is in the Technology Equipment industry. Its latest annual revenue is $52.85B, ranking 6 in the industry. The net profit is $-267.00M, ranking 111 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Hold, with an average price target of $91.99, a high of $160.00, and a low of $63.00.
More details about Intel Corp (INTC)
Company Specific Risks:
- Severe Gross Margin and Earnings Compression: Recent analyst commentary continues to trigger intraday volatility following Intel's weak fourth-quarter guidance, which projects non-GAAP gross margin contracting to approximately 38% (down from 44.1% in the prior quarter) and non-GAAP EPS falling by over 50% sequentially to $0.25.
- Prolonged PC Demand Contraction: Management's projection of a 12% drop in the global personal computer total addressable market for 2026—accompanied by warnings that steep volume declines will persist through at least the first half of 2027—poses immediate downside pressure on core Client Computing Group cash flows.
- Lack of Commercial Traction in External Foundry Operations: Multiple institutional downgrades from firms such as Bank of America and UBS highlight mounting skepticism over Intel Foundry Services, specifically citing insufficient commitments from third-party customers to validate aggressive capital expenditures.
- Data Center Supply Constraints and Share Vulnerability: Persistent packaging and component bottlenecks are restricting Intel's operational capacity to fulfill data center processor demand, capping immediate volume realization and risking market share losses to competing server-chip architectures.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.