


Arm Holdings PLC Stock (ARM) Moved Down by 3.02% on Nov 12: A Full Analysis


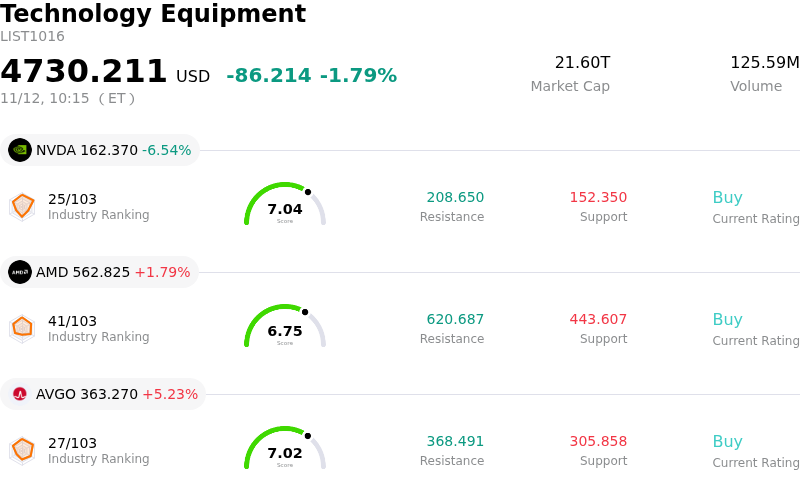
Arm Holdings PLC (ARM) moved down by 3.02%. The Technology Equipment sector is down by 1.79%. The company underperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 6.78%; Advanced Micro Devices Inc (AMD) up 1.56%; Broadcom Inc (AVGO) up 5.19%.
What is driving Arm Holdings PLC (ARM)’s stock price down today?
Arm Holdings experienced downward pressure during the trading session, driven by ongoing investor digestion of fundamental headwinds in its royalty revenue streams, valuation multiple compression across high-multiple semiconductor peers, and persistent legal and licensing overhangs.
The primary catalyst weighing on sentiment stems from structural concerns regarding end-market demand following the company’s recent financial disclosures. While upfront licensing revenue continues to benefit from artificial intelligence architectural adoption and enterprise commitments, royalty revenues have visibly lagged market expectations. Because royalties directly reflect actual device shipments and production runs, the deceleration in this segment signals protracted softness across the broader consumer electronics and smartphone supply chains. Investors view this divergence as an indication that monetization of next-generation architectures is taking longer to materialize at scale, clouding near-term operational momentum.
Compounding this fundamental friction is margin scrutiny tied to the company’s evolving business model. Capital expenditures and research and development spending have trended higher as Arm pushes deeper into advanced compute subsystems and custom silicon development. While these initiatives aim to capture greater economic value per chip, they introduce execution risks, expand operating costs, and generate potential friction with key ecosystem licensees. Furthermore, near-term revenue guidance offered limited upside relative to elevated consensus expectations, prompting institutional desks to trim forward valuation multiples on a stock that still carries a substantial growth premium.
Uncertainty surrounding major customer relationships also remains an active drag on sentiment. Lingering litigation and dispute dynamics with foundational partners, particularly Qualcomm, sustain an overhang on future licensing terms and compliance frameworks. These legal frictions complicate revenue visibility and heighten the perceived risk profile of Arm’s core intellectual property licensing agreements.
Finally, broader macroeconomic and factor-driven dynamics amplified the retreat. Elevated Treasury yields and a cautious macro tone have triggered selective de-risking across expensive technology and semiconductor intellectual property names. With high-beta growth assets facing systematic profit-taking, Arm’s combination of slowing royalty velocity, rising development costs, and customer dispute risk left shares vulnerable to intraday selling.
Technical Analysis of Arm Holdings PLC (ARM)
Technically, Arm Holdings PLC (ARM) shows a MACD (12,26,9) value of 1.523, indicating a neutral signal. The RSI at 42.678 suggests neutral condition and the Williams %R at 53.967 suggests neutral condition. Please monitor closely.
Fundamental Analysis of Arm Holdings PLC (ARM)
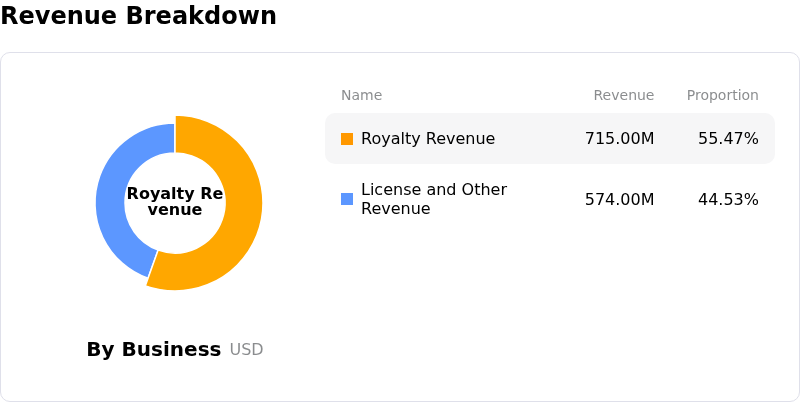
Arm Holdings PLC (ARM) is in the Technology Equipment industry. Its latest annual revenue is $4.92B, ranking 24 in the industry. The net profit is $904.00M, ranking 18 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $0.00, a high of $0.00, and a low of $0.00.
More details about Arm Holdings PLC (ARM)
Company Specific Risks:
- Smartphone Royalty Deceleration: Royalty revenue growth decelerated to just 8% year-over-year in the latest quarterly report, as persistent softness in global smartphone unit shipments and extended consumer replacement cycles continue to drag on high-margin royalty streams and offset broader AI data-center momentum.
- Post-Earnings Analyst Price Target Reductions: Major Wall Street institutions, including JPMorgan, TD Cowen, and Barclays, cut their price targets following quarterly earnings, citing an absence of near-term guidance catalysts and questioning whether current royalty monetization rates can sustain the company’s elevated trading multiples.
- Execution and Supply Constraints in Custom Silicon Transition: The company's strategic push into producing proprietary server and AGI CPUs creates acute execution risks, subjecting Arm to severe advanced-node foundry capacity bottlenecks at TSMC while concurrently creating direct channel conflicts with its primary architectural licensing customers.
- Contractual Breach Findings and Licensing Overhang with Qualcomm: Recent federal court jury findings that Arm breached its Architectural License Agreement and interfered in partner dealings—alongside ongoing bench proceedings regarding good-faith licensing terms—create protracted legal overhang and the risk of disrupted royalty collections from one of its largest ecosystem partners.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.