


Marvell Technology Inc Stock (MRVL) Moved Down by 4.38% on Nov 12: What Investors Need To Know


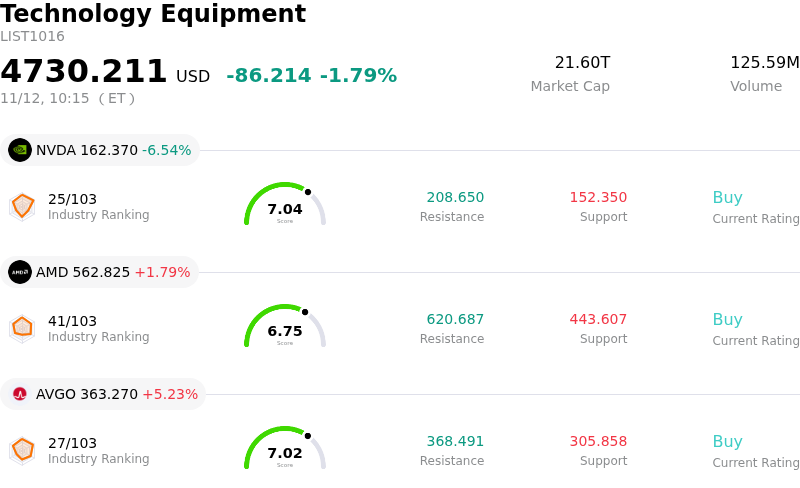
Marvell Technology Inc (MRVL) moved down by 4.38%. The Technology Equipment sector is down by 1.79%. The company underperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 6.78%; Advanced Micro Devices Inc (AMD) up 1.56%; Broadcom Inc (AVGO) up 5.19%.
What is driving Marvell Technology Inc (MRVL)’s stock price down today?
Marvell Technology faced clear downward pressure during the trading session, largely reflecting broader risk-off sentiment across high-multiple semiconductor equities alongside specific structural considerations surrounding custom cloud silicon. As macro expectations recalibrate and interest rate trajectories create valuation headwinds for growth assets, institutional capital has rotated out of extended momentum names within the artificial intelligence infrastructure trade, leaving richly valued hardware suppliers vulnerable to heightened selling activity.
At the core of investor scrutiny is the margin trajectory and deployment cadence of Marvell’s custom application-specific integrated circuit programs for cloud hyperscalers. While design wins with tier-one cloud providers provide substantial top-line momentum, custom compute processors inherently carry lower gross margin profiles compared to high-performance merchant silicon. Markets frequently react negatively to expectations of shifting product mix, as accelerated volume ramps in lower-margin custom programs risk diluting blended profitability if not fully offset by operational leverage or higher-margin optical solutions.
Simultaneously, the pace of recovery across Marvell’s legacy business segments continues to temper institutional enthusiasm. While data center interconnects and optical digital signal processors exhibit sustained structural demand driven by accelerated computing clusters, legacy exposure in enterprise networking, carrier infrastructure, and consumer-facing end markets continues to experience sluggish cyclical demand. This divergent growth profile limits operating margin expansion and raises concern that non-cloud revenue drag could partially offset near-term datacenter tailwinds.
Heightened competitive pressure from specialized networking and custom silicon rivals also weighs on sentiment. Large competitors with dominant market share in hyperscaler custom accelerators and switching silicon pose ongoing competitive threats, keeping execution and pricing risks elevated. For institutional portfolios, while Marvell remains strategically positioned across key connectivity and compute secular themes, near-term capital allocation favors tactical caution until clearer evidence of margin stabilization and broad-based demand normalization materializes.
Technical Analysis of Marvell Technology Inc (MRVL)
Technically, Marvell Technology Inc (MRVL) shows a MACD (12,26,9) value of -7.128, indicating a sell signal. The RSI at 36.489 suggests neutral condition and the Williams %R at 76.007 suggests sell condition. Please monitor closely.
Media Coverage of Marvell Technology Inc (MRVL)
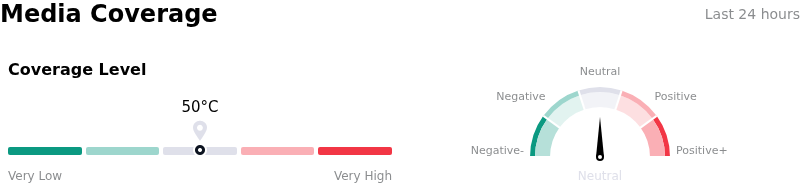
In terms of media coverage, Marvell Technology Inc (MRVL) shows a coverage score of 50, indicating a moderate level of media attention. The overall market sentiment index is currently in neutral zone.
Fundamental Analysis of Marvell Technology Inc (MRVL)
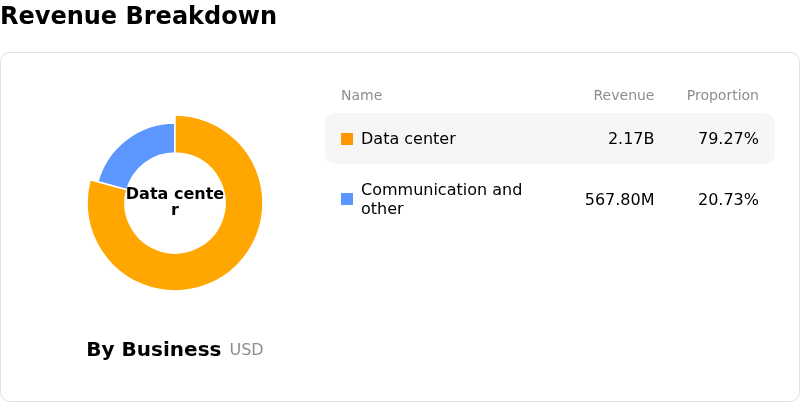
Marvell Technology Inc (MRVL) is in the Technology Equipment industry. Its latest annual revenue is $8.19B, ranking 19 in the industry. The net profit is $2.67B, ranking 13 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $314.95, a high of $450.00, and a low of $175.00.
More details about Marvell Technology Inc (MRVL)
Company Specific Risks:
- Severe Equity Dilution from Lumentum Acquisition: Marvell's massive all-stock agreement to acquire optical component maker Lumentum Holdings has triggered severe market pushback, as the required issuance of new equity reduces existing shareholders' ownership to approximately 67% and threatens immediate mid-single-digit EPS dilution that projected cost synergies cannot offset.
- Institutional Analyst Downgrades and Valuation Cuts: Multiple research firms, including Bank of America and TD Cowen, have downgraded MRVL to Neutral/Hold and slashed price targets by up to 50%, citing poorly timed M&A near the peak of the optical transceiver cycle, potential customer conflicts, and a protracted regulatory timeline extending to 2028.
- Transaction Instability and Renegotiation Risk: The sharp decline in Marvell's market valuation following the deal announcement has significantly eroded the nominal value of the all-stock consideration offered to Lumentum, increasing the risk of target shareholder revolt, deal failure, or costly renegotiations.
- Regional Moratorium Threats to AI Data Center Deployments: Emerging political and regulatory proposals across key infrastructure hubs (such as Texas, Ohio, and Georgia) calling for construction moratoriums on new hyperscale facilities present an immediate threat to forward demand for Marvell's data center networking processors, custom ASICs, and electro-optics platforms.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.