


Dell Technologies Inc Stock (DELL) Moved Down by 5.10% on Nov 12: Facts Behind the Movement


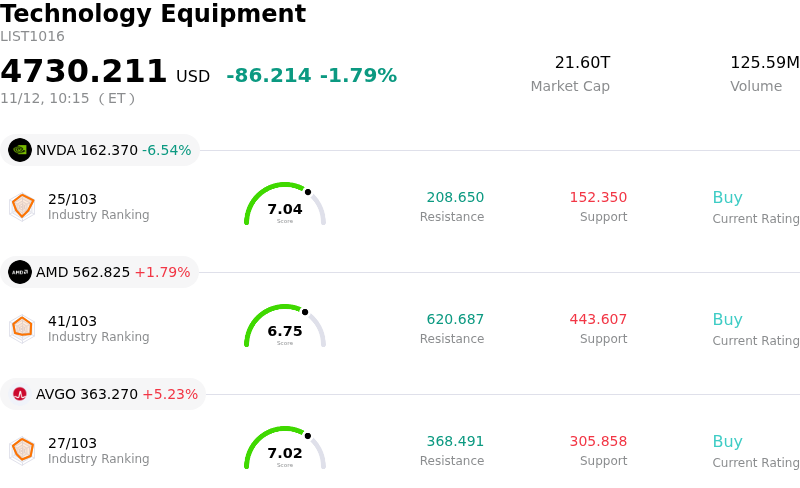
Dell Technologies Inc (DELL) moved down by 5.10%. The Technology Equipment sector is down by 1.79%. The company underperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 6.78%; Advanced Micro Devices Inc (AMD) up 1.56%; Broadcom Inc (AVGO) up 5.19%.
What is driving Dell Technologies Inc (DELL)’s stock price down today?
Dell Technologies shares experienced notable downward pressure during the session, reflecting a confluence of macroeconomic hesitation, margin headwinds within enterprise hardware, and broader profit-taking across artificial intelligence infrastructure beneficiaries. Institutional investors have increasingly scrutinized the profitability profile of AI-optimized servers, where surging component costs and competitive pricing continue to pose challenges to gross margins.
A primary catalyst weighing on sentiment centers on profitability dynamics within Dell's Infrastructure Solutions Group. While demand for high-density AI servers remains robust, the pass-through economics of expensive graphics processing units and high-bandwidth memory have historically diluted corporate gross margins. With spot and contract prices for enterprise storage and dynamic random-access memory remaining elevated, market participants are growing cautious that the cost of goods sold will outpace pricing power, limiting operating leverage despite elevated top-line delivery volumes.
At the same time, the anticipated commercial personal computer refresh cycle driven by artificial intelligence-enabled PCs and legacy operating system upgrades has progressed at a more measured pace than previously priced into the stock. Corporate IT procurement departments continue to exercise budget discipline, prioritizing specialized cloud and data center workloads over large-scale client device fleet overhauls. This extended sales cycle in the Client Solutions Group removes an essential high-margin buffer that typically offsets data center capital expenditure volatility.
Competitive dynamics in the server market also contribute to the current derisking. Rival original equipment manufacturers and contract design manufacturers have intensified aggressive bidding to secure tier-two cloud service provider and enterprise deployments, raising concerns over market share preservation and potential pricing concessions. In parallel, broader risk-off positioning across semiconductor and hardware peers has prompted multi-asset funds to trim exposure to cyclical technology names ahead of upcoming corporate earnings prints.
From a structural perspective, Dell maintains strong cash flow generation capabilities and disciplined shareholder return programs via buybacks and dividends. However, over the near term, institutional conviction requires clear evidence of margin stabilization across next-generation server architectures and tangible acceleration in commercial PC replacements before a durable valuation floor can be established.
Technical Analysis of Dell Technologies Inc (DELL)
Technically, Dell Technologies Inc (DELL) shows a MACD (12,26,9) value of -12.070, indicating a sell signal. The RSI at 37.398 suggests neutral condition and the Williams %R at 79.635 suggests sell condition. Please monitor closely.
Media Coverage of Dell Technologies Inc (DELL)
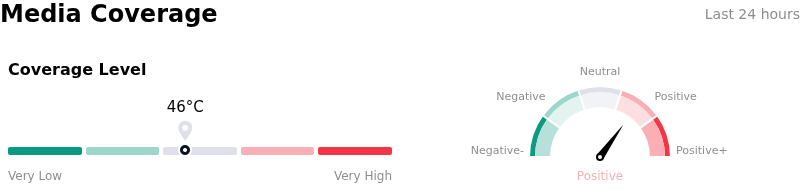
In terms of media coverage, Dell Technologies Inc (DELL) shows a coverage score of 46, indicating a moderate level of media attention. The overall market sentiment index is currently in bullish zone.
Fundamental Analysis of Dell Technologies Inc (DELL)
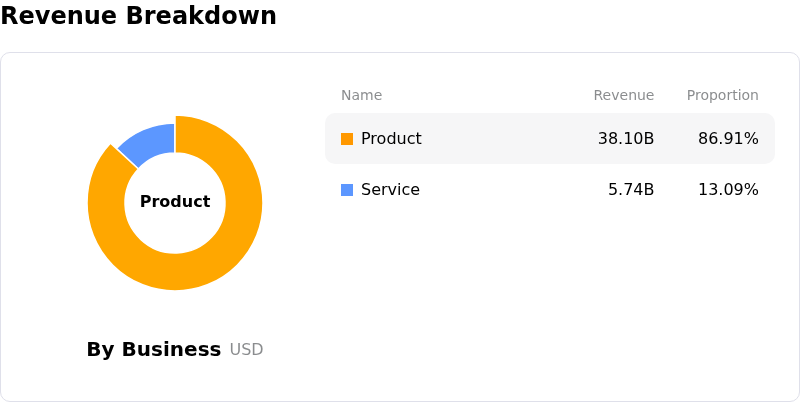
Dell Technologies Inc (DELL) is in the Technology Equipment industry. Its latest annual revenue is $113.54B, ranking 2 in the industry. The net profit is $5.94B, ranking 4 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $588.12, a high of $700.00, and a low of $499.80.
More details about Dell Technologies Inc (DELL)
Company Specific Risks:
- AI Infrastructure Supply-Chain Vulnerability: Severe leadership disruption at key GPU partner NVIDIA has injected immediate uncertainty into enterprise infrastructure deployment, threatening fulfillment timelines and conversion rates across Dell's $95 billion AI server order backlog.
- Analyst Downgrade on Core Segment Weakness: A fresh rating downgrade by UBS to Neutral reflects institutional concern over persistent volume contraction within the Client Solutions Group, warning that prolonged weakness in traditional PC demand will trigger valuation multiple compression.
- Component Cost Inflation and Margin Compression: Acute price surges and supply tightness in DRAM and NAND memory are placing direct downward pressure on server manufacturing margins, elevating the risk of profitability erosion if component inflation cannot be passed on to enterprise buyers.
- Insider Liquidation Pressures: Form 4 and Form 144 regulatory filings showing notable insider divestment activity have intensified intraday selling, compounding market unease regarding customer financing cash burn and working capital strain ahead of third-quarter earnings.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.