


Broadcom Inc Stock (AVGO) Opened Up by 4.68% on Nov 12: Key Drivers Unveiled


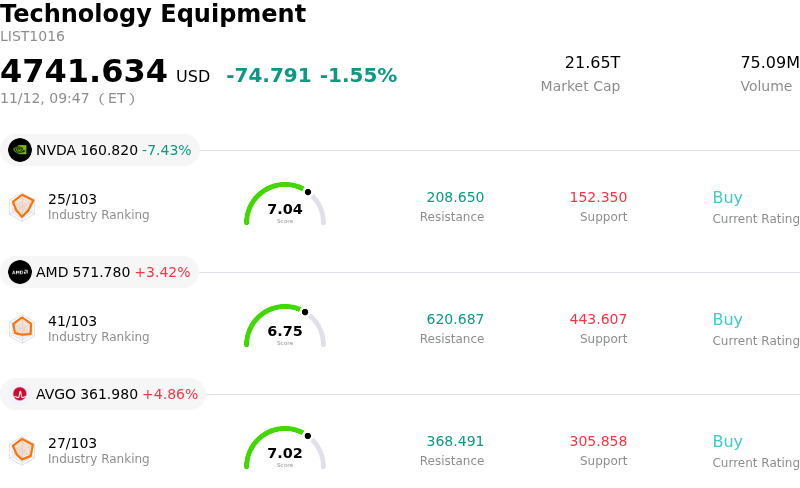
Broadcom Inc (AVGO) opened up by 4.68%. The Technology Equipment sector is down by 1.55%. The company outperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 7.77%; Advanced Micro Devices Inc (AMD) up 2.69%; Broadcom Inc (AVGO) up 4.68%.
What is driving Broadcom Inc (AVGO)’s stock price up today?
Broadcom is experiencing robust upside momentum, propelled primarily by sustained institutional confidence in its custom artificial intelligence accelerator pipeline and next-generation networking infrastructure. Hyperscale cloud service providers continue to aggressively expand their capital expenditure allocations toward custom silicon to optimize workload efficiency and reduce long-term operational costs. Broadcom's deeply entrenched design partnerships with major cloud titans for specialized processing units provide durable, multi-year revenue visibility, cementing its position as the premier merchant partner for proprietary hyperscale infrastructure.
In parallel, the rapid scaling of high-density computing clusters is driving elevated demand for Broadcom’s high-throughput networking portfolio. As training and inference workloads expand exponentially, data center operators increasingly prioritize bandwidth density, low latency, and energy efficiency. Broadcom directly benefits from this structural shift through its market-leading Ethernet switching platforms, routing solutions, and optical interconnects. The broader industry transition toward open Ethernet architectures over proprietary interconnect fabrics reinforces Broadcom's pricing power and content gains per computing node.
Beyond hardware, the operational optimization and monetization of VMware continue to reinforce the company's financial profile. Broadcom’s strategic shift of VMware's customer base toward multi-year subscription licenses has accelerated recurring software revenue growth while expanding operating margins. Institutional investors view this dual-engine framework—pairing hyper-growth custom silicon with highly cash-generative, mission-critical enterprise software—as an exceptionally resilient corporate model capable of funding sustained debt reduction, dividend growth, and share repurchases.
Constructive sell-side revisions and broader market enthusiasm for leading semiconductor infrastructure have further catalyzed buying interest. Analysts have increasingly highlighted the company's expanding backlog in custom silicon and structural networking tailwinds, prompting upward adjustments to forward earnings estimates and target valuations. While cyclical fluctuations in traditional consumer wireless and legacy enterprise storage require ongoing monitoring, the compounding acceleration in artificial intelligence infrastructure spending remains the dominant driver sustaining the stock's upward momentum.
Technical Analysis of Broadcom Inc (AVGO)
Technically, Broadcom Inc (AVGO) shows a MACD (12,26,9) value of 8.084, indicating a neutral signal. The RSI at 59.636 suggests neutral condition and the Williams %R at 0.910 suggests overbought condition. Please monitor closely.
Media Coverage of Broadcom Inc (AVGO)
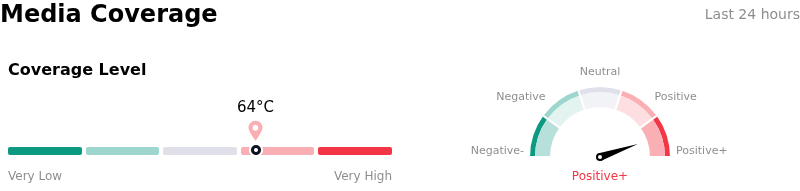
In terms of media coverage, Broadcom Inc (AVGO) shows a coverage score of 64, indicating a high level of media attention. The overall market sentiment index is currently in extremely bullish zone.
Fundamental Analysis of Broadcom Inc (AVGO)
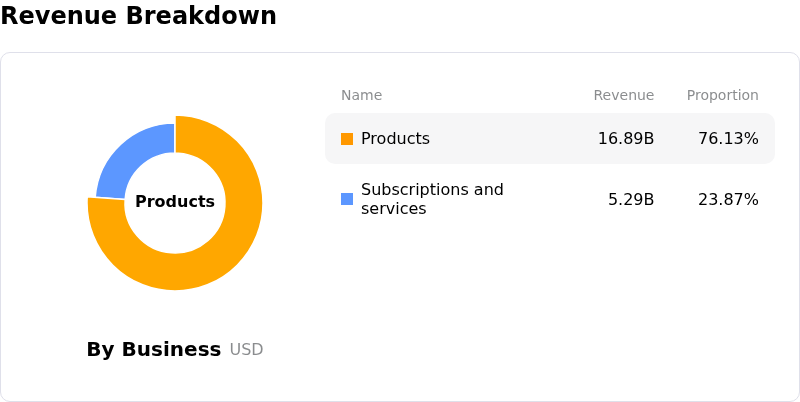
Broadcom Inc (AVGO) is in the Technology Equipment industry. Its latest annual revenue is $63.89B, ranking 5 in the industry. The net profit is $23.13B, ranking 5 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $516.73, a high of $663.00, and a low of $215.88.
More details about Broadcom Inc (AVGO)
Company Specific Risks:
- Escalating Contingent Liabilities and Customer Financing Exposure: Regulatory disclosures and institutional analyst reviews highlight Broadcom's surging off-balance-sheet commitments, where customer lease backstops and debt financing guarantees tied to key artificial intelligence partners have escalated toward $72 billion in maximum potential liabilities, exposing the firm to severe counterparty credit risk.
- Severe Revenue Concentration Among Hyperscale AI Clients: Broadcom's top five end customers now generate roughly 55% of total company revenue, with custom AI accelerator (XPU) growth concentrated across only a handful of mega-cap customers, leaving near-term earnings highly vulnerable to single-client capital expenditure reductions or project timeline deferrals.
- Geopolitical Displacement in Chinese Enterprise Networking: Accelerated state-mandated domestic technology substitution in China is driving state-owned data centers and telecommunications operators toward domestic networking alternatives, threatening Broadcom's dominant market share in high-throughput Ethernet switching and routing silicon.
- Supply Chain Concentration and Margin Compression: Overwhelming reliance on TSMC for more than 90% of advanced semiconductor wafer fabrication exposes operations to critical single-foundry supply bottlenecks, while a shifting revenue mix toward custom ASIC hardware relative to high-margin software threatens near-term operating margin contraction.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.