


Palo Alto Networks Inc Stock (PANW) Opened Down by 4.35% on Nov 12: Facts Behind the Movement


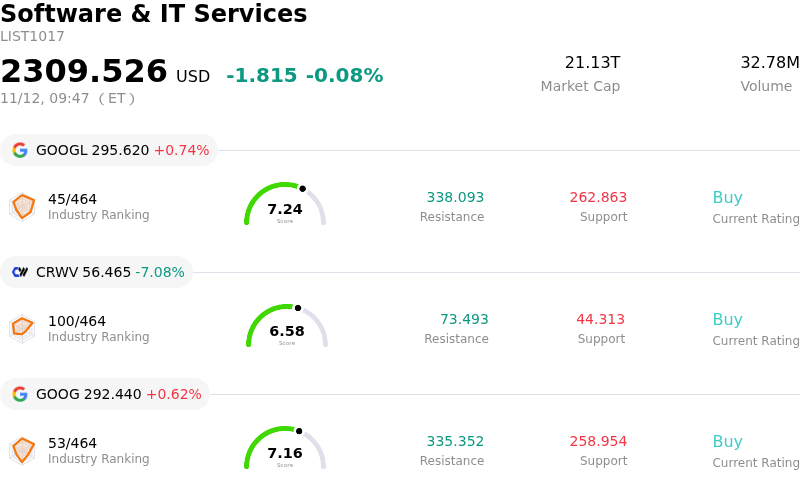
Palo Alto Networks Inc (PANW) opened down by 4.35%. The Software & IT Services sector is down by 0.08%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Alphabet Inc Class A (GOOGL) up 0.79%; CoreWeave Inc (CRWV) down 7.01%; Alphabet Inc Class C (GOOG) up 0.68%.
What is driving Palo Alto Networks Inc (PANW)’s stock price down today?
Palo Alto Networks experienced notable downward pressure today as institutional investors engaged in risk-off positioning and profit-taking ahead of the company's upcoming quarterly financial results. Market participants are increasingly cautious about the setup for large-cap cybersecurity names, reflecting apprehension that elevated valuation multiples leave minimal room for execution missteps. Following recent earnings reports across the broader enterprise software and network security landscape that highlighted decelerating product cycles and extended sales scrutiny, market sentiment has turned defensive.
A central factor weighing on the shares is investor anxiety surrounding the company's ongoing platformization strategy. While platform consolidation is designed to capture market share over the long term, near-term promotional incentives, bundled customer agreements, and deferred monetization schedules continue to raise questions about sequential billings momentum and operating margin expansion. Institutional desks appear reluctant to maintain full exposure into the print, choosing instead to trim positions to mitigate asymmetric downside risks should forward guidance or net new annual recurring revenue fall short of consensus targets.
The broader macroeconomic environment has also contributed to today's pullback. Uneven trends in bond yields and broader tech sector consolidation have disproportionately affected high-multiple growth equities. With premium valuations demanding consistent operational outperformance, any signs of enterprise budget constraints or elongated deal-closing cycles create immediate valuation friction.
Compounding this cautious tone, sector-wide scrutiny regarding newly identified zero-day vulnerabilities across perimeter firewall management interfaces has introduced minor tactical overhangs. Although such disclosure cycles are relatively routine in the infrastructure security domain, they serve as a reminder of headline risks and implementation challenges for customers, dampening short-term sentiment.
From an institutional perspective, today's drop reflects tactical de-risking rather than a structural deterioration of Palo Alto Networks' enterprise moat. While long-term demand drivers in artificial intelligence security and cloud defense remain intact, short-term price discovery is dominated by pre-earnings hedging and heightened sensitivity to near-term profitability metrics.
Technical Analysis of Palo Alto Networks Inc (PANW)
Technically, Palo Alto Networks Inc (PANW) shows a MACD (12,26,9) value of -8.140, indicating a sell signal. The RSI at 38.388 suggests neutral condition and the Williams %R at 90.333 suggests oversold condition. Please monitor closely.
Fundamental Analysis of Palo Alto Networks Inc (PANW)
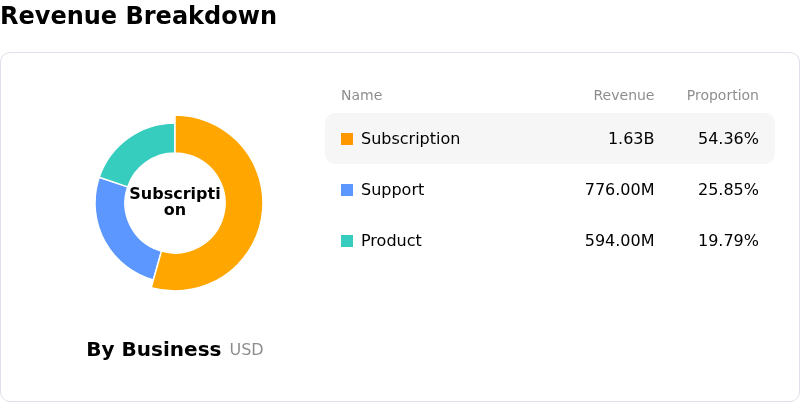
Palo Alto Networks Inc (PANW) is in the Software & IT Services industry. Its latest annual revenue is $11.48B, ranking 34 in the industry. The net profit is $307.00M, ranking 90 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $401.69, a high of $525.00, and a low of $190.00.
More details about Palo Alto Networks Inc (PANW)
Company Specific Risks:
- Pre-Earnings De-risking and Elevated Execution Bar: Institutional commentary ahead of the upcoming fiscal first-quarter earnings release emphasizes that the stock requires an above-consensus beat of at least 3% merely to defend current price levels, prompting aggressive pre-earnings positioning cuts and heightened intraday volatility as traders brace for potential contract pushouts.
- Gross Margin Dilution and M&A Integration Overhang: Operational profitability is facing near-term pressure from escalating cloud hosting and memory infrastructure costs, further aggravated by capital allocation risks, integration overhead, and share dilution associated with recent inorganic transactions, including the CyberArk integration and the reported $500 million cash pursuit of Clutch Security.
- Decelerating Next-Generation Security ARR Trajectory: Investor sentiment remains constrained by projections of a sharp growth normalization in Next-Generation Security (NGS) annual recurring revenue toward the low-20% range—down significantly from prior 60%+ levels—while aggressive upfront discounting and extended free trials utilized in the "platformization" strategy continue to weigh on cash conversion.
- Acute Multiple Compression Sensitivity: Trading at roughly 75 times forward earnings, the equity carries an extreme valuation premium relative to enterprise software peers, leaving shares highly vulnerable to severe intraday drawdowns upon any marginal downward revision to forward billings or free cash flow margin guidance.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.