


ServiceNow Inc Stock (NOW) Moved Up by 3.75% on Nov 11: Facts Behind the Movement


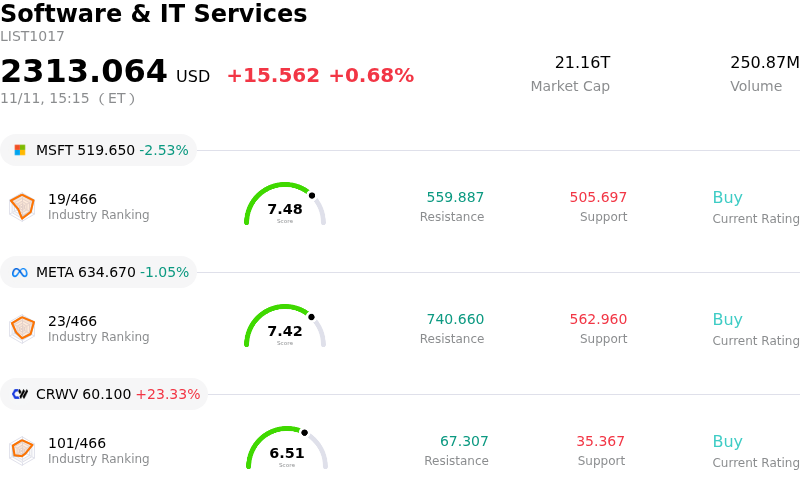
ServiceNow Inc (NOW) moved up by 3.75%. The Software & IT Services sector is up by 0.68%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Microsoft Corp (MSFT) down 2.52%; Meta Platforms Inc (META) down 1.04%; CoreWeave Inc (CRWV) up 23.33%.
What is driving ServiceNow Inc (NOW)’s stock price up today?
ServiceNow experienced notable upward momentum during the trading session, driven by broad-based strength in large-cap enterprise cloud software and renewed institutional appetite for high-visibility compounders. Investors reacted positively to robust enterprise spending signals, reflecting confidence that mission-critical digital workflow and automation platforms continue to capture a disproportionate share of global IT budgets.
A primary fundamental catalyst fueling this advance is the accelerating operationalization of generative artificial intelligence across enterprise environments. ServiceNow has established clear leadership in translating AI capabilities into measurable business productivity through its Now Assist portfolio, driving higher average contract values and expanding net new annual contract value. As enterprise organizations increasingly seek to consolidate fragmented point solutions into unified workflow architectures, the company's core platform benefits from strong retention metrics and expanding remaining performance obligations, providing exceptional multi-year revenue visibility.
Institutional capital flows also provided meaningful support throughout the session. Favorable broader market risk appetite, coupled with stabilizing yields, encouraged a reallocation toward cash-generative technology leaders with solid operating leverage. Sell-side sentiment across Wall Street has remained constructive, with analysts emphasizing the platform's durable subscription growth trajectory and its ability to consistently expand operating margins while scaling free cash flow. This consensus reinforces institutional confidence in ServiceNow as a core holding within enterprise software allocations.
Looking ahead, the sustainability of this upward trend will hinge on the company's ability to maintain high renewal rates and expand its presence across employee, customer, and creator workflows. While near-term momentum is well-supported by structural demand for back-office digital transformation and workflow modernization, investors should remain attentive to broader corporate IT spending scrutiny, sales cycle timing, and competitive dynamics across cloud enterprise automation.
Technical Analysis of ServiceNow Inc (NOW)
Technically, ServiceNow Inc (NOW) shows a MACD (12,26,9) value of -6.984, indicating a sell signal. The RSI at 31.614 suggests neutral condition and the Williams %R at 89.936 suggests oversold condition. Please monitor closely.
Media Coverage of ServiceNow Inc (NOW)
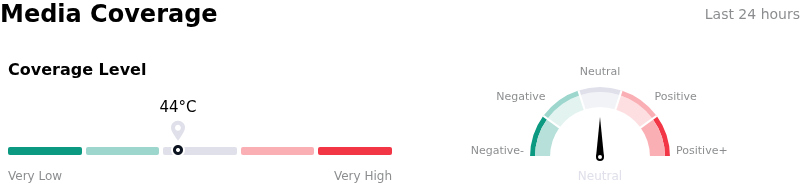
In terms of media coverage, ServiceNow Inc (NOW) shows a coverage score of 44, indicating a moderate level of media attention. The overall market sentiment index is currently in neutral zone.
Fundamental Analysis of ServiceNow Inc (NOW)
ServiceNow Inc (NOW) is in the Software & IT Services industry. Its latest annual revenue is $13.28B, ranking 28 in the industry. The net profit is $1.75B, ranking 30 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $159.00, a high of $266.00, and a low of $72.00.
More details about ServiceNow Inc (NOW)
Company Specific Risks:
- Deceleration in Forward Bookings and cRPO Guidance: Market sentiment remains impaired by fourth-quarter current remaining performance obligations (cRPO) growth projected to slow to 18.5% constant currency (down from 21% in the prior quarter), driven by contract pull-forwards into earlier periods, an unfavorable mix shift toward on-premises public sector contracts, and termination-for-convenience clauses that cloud forward subscription visibility.
- Operating Margin Compression and Elevated Integration Costs: Profitability faces acute pressure as fourth-quarter operating margin guidance dropped to 32.0% (down from 33.7% year-over-year), compounded by GAAP operating margin compression to 9.5% resulting from rising acquisition expenses, heavier infrastructure debt, and aggressive capital outlays to deploy generative AI capabilities.
- Securities Law Inquiries and Class Action Exposure: Legal risks escalated following formal announcements by shareholder rights litigators, including Pomerantz LLP, initiating investigations into potential executive securities fraud and misrepresentations concerning performance obligations and billing trajectories.
- Structural Disruption to Seat-Based Subscription Models: Institutional analysts are actively downgrading price targets due to fears that enterprise adoption of autonomous, agentic AI workflows will cannibalize ServiceNow's core per-user licensing model, leading to renewal down-scoping and reduced net-new seat expansion across enterprise clients.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.