


Corning Inc Stock (GLW) Moved Up by 7.88% on Nov 11: Drivers Behind the Movement


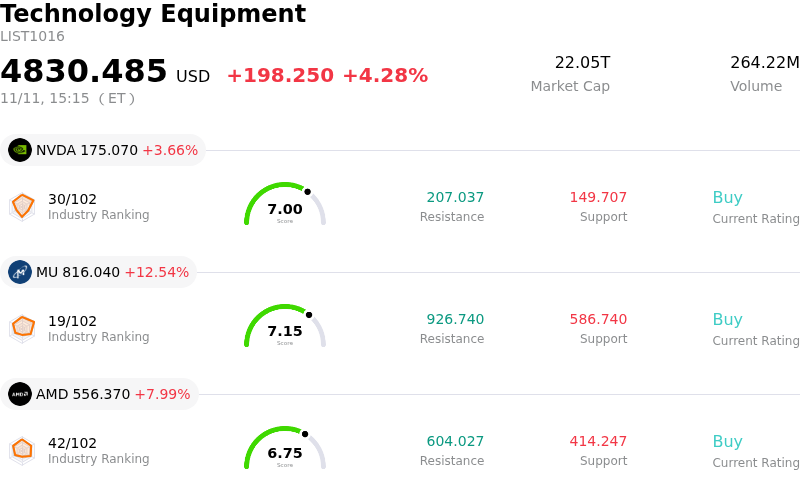
Corning Inc (GLW) moved up by 7.88%. The Technology Equipment sector is up by 4.28%. The company outperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) up 3.61%; Micron Technology Inc (MU) up 12.45%; Advanced Micro Devices Inc (AMD) up 7.98%.
What is driving Corning Inc (GLW)’s stock price up today?
Corning experienced substantial upward intraday momentum primarily driven by high-profile Wall Street research coverage that catalyzed institutional buying interest. Jefferies initiated coverage on the company with a Buy rating and a constructive price target, reinforcing market conviction in Corning's structural transformation from a diversified materials and display glass manufacturer into a premier artificial intelligence optical infrastructure provider. The bullish initiation highlighted that the equity presents an appealing risk-reward profile, providing investors with an attractive entry point as high-speed optical connectivity becomes an indispensable foundation for generative AI data center buildouts.
A core pillar underpinning the positive sentiment is the acute supply-demand imbalance across high-density optical networking components. The research commentary emphasized a persistent global shortfall of optical fiber relative to soaring hyperscaler demand, which significantly enhances Corning's multiyear revenue visibility and strengthens commercial commitments from major cloud customers. As AI model architectures scale and GPU cluster interconnects require ever-higher bandwidth and lower latency, data centers are shifting critical connectivity from copper to advanced optical solutions. This transition allows Corning to command superior pricing power, deploy denser and higher-value product architectures, and capture expanding market share across hyperscale deployments.
The broader market response also reflects sustained institutional reassessment of the company’s fundamental trajectory following robust operational results and management's Springboard growth initiatives. The Optical Communications segment continues to serve as the company's primary earnings engine, generating rapid enterprise sales growth and substantial margin leverage. Furthermore, multiyear supply agreements backed by customer cash commitments have materially derisked future capacity expansions, easing investor concerns around capital intensity.
Combined with long-term optionality in co-packaged optics and integrated photonics platforms, institutional investors are increasingly viewing Corning as an essential picks-and-shovels enabler of the AI infrastructure wave. This structural repositioning, paired with favorable analyst sponsorship, catalyzed aggressive capital inflows and reinforced a strong bullish trend throughout the session.
Technical Analysis of Corning Inc (GLW)
Technically, Corning Inc (GLW) shows a MACD (12,26,9) value of -0.239, indicating a sell signal. The RSI at 44.400 suggests neutral condition and the Williams %R at 39.354 suggests buy condition. Please monitor closely.
Fundamental Analysis of Corning Inc (GLW)
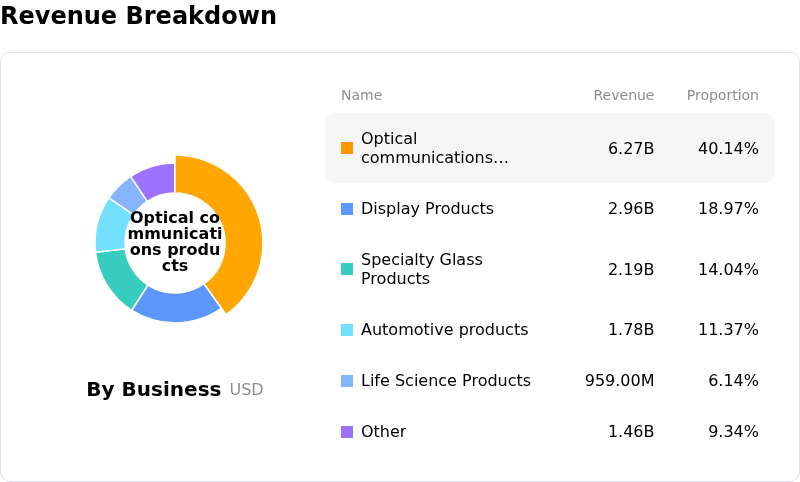
Corning Inc (GLW) is in the Technology Equipment industry. Its latest annual revenue is $15.63B, ranking 7 in the industry. The net profit is $1.60B, ranking 3 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $177.07, a high of $220.00, and a low of $132.00.
More details about Corning Inc (GLW)
Company Specific Risks:
- Institutional Price Target Revision and Multiple Compression: Sanford C. Bernstein reduced its price target on Corning from $140 to $120 while maintaining a Market Perform rating, precipitating selling pressure and exacerbating downside risks for a stock trading at an elevated valuation multiple.
- Sentiment Reversal in AI Optical Infrastructure: An accelerating pullback across AI infrastructure and data center "picks-and-shovels" plays has directly hit Corning's premium valuation, raising concerns that high expectations for its Optical Communications segment will encounter order digestion or deceleration.
- Persistent Headwinds in Consumer Electronics and Glass Innovations: Softer smartphone replacement cycles and component cost inflation impacting key OEMs, including Apple, continue to pressure demand and drag on revenue growth within Corning's core Glass Innovations and Gorilla Glass businesses.
- Elevated Capital Expenditures and Solar Segment Ramp Drag: Aggressive capital expenditure acceleration to fund facility expansions—rising to $545 million—alongside operational friction and bottom-line losses in scaling domestic solar module and wafer production, presents near-term risks to free cash flow and margin expansion.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.