


Qualcomm Inc Stock (QCOM) Moved Up by 4.62% on Nov 11: What Signal Does It Send?


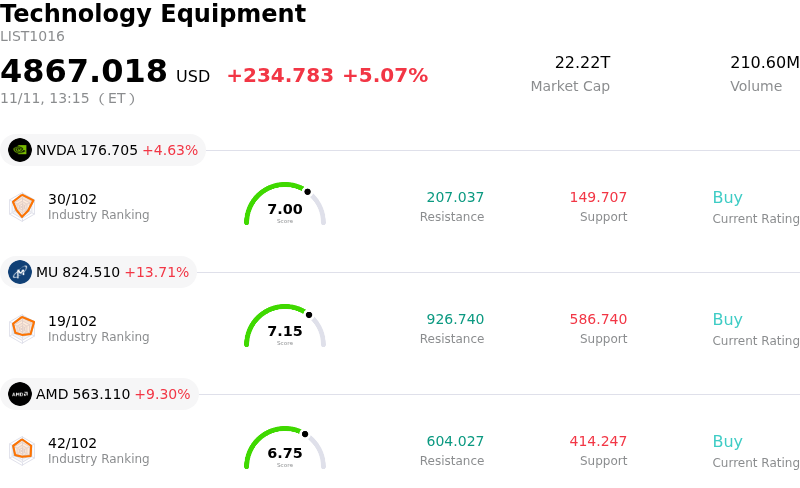
Qualcomm Inc (QCOM) moved up by 4.62%. The Technology Equipment sector is up by 5.07%. The company underperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) up 4.60%; Micron Technology Inc (MU) up 13.73%; Advanced Micro Devices Inc (AMD) up 9.29%.
What is driving Qualcomm Inc (QCOM)’s stock price up today?
Qualcomm shares advanced firmly as institutional capital responded favorably to positive momentum across the company’s core handset business alongside accelerating traction in its edge artificial intelligence and diversification initiatives. The upward price action reflects renewed market confidence in the semiconductor giant’s ability to sustain top-line expansion and expand margins despite broader cyclical crosscurrents in the consumer electronics space.
A key fundamental catalyst driving buying interest is the ongoing recovery in the premium tier smartphone market, particularly across key Asian original equipment manufacturer channels. Qualcomm’s flagship Snapdragon mobile platforms continue to command solid pricing power and share within high-end Android devices, driven by increasing consumer demand for on-device generative artificial intelligence capabilities. This strength has alleviated near-term concerns regarding handset replacement cycles, demonstrating that content gains per device remain a durable growth engine for the chipmaker.
Beyond smartphones, institutional investors are increasingly rewarding Qualcomm for its multi-year revenue diversification strategy. The company’s automotive segment continues to demonstrate robust momentum, supported by a sizable design-win pipeline for the Snapdragon Digital Chassis that delivers sticky, multi-year revenue visibility as software-defined vehicles proliferate. Concurrently, initial market feedback on Qualcomm’s ARM-based Snapdragon compute platforms for next-generation personal computers has bolstered the narrative that the firm can establish a meaningful, high-margin foothold in the mainstream and commercial PC markets, thereby reducing structural reliance on legacy handset licensing and modem revenue.
Wall Street sentiment has turned incrementally constructive, with several research desks reiterating positive ratings and highlighting attractive risk-reward dynamics given Qualcomm’s cash generation and shareholder return profile. Analysts have underscored that the company’s expansion into automotive, industrial IoT, and AI-enabled computing effectively dampens terminal valuation risks associated with eventual modem insourcing by major clients such as Apple.
From a strategic perspective, institutional portfolio managers should continue to monitor consumer demand health in global smartphone markets, licensing royalty negotiations, and competitive developments in the mobile processor and AI PC landscape. Nonetheless, the prevailing upward movement signals strong market endorsement of Qualcomm’s transition from a mobile-centric communications vendor into an expansive, diversified edge-computing leader.
Technical Analysis of Qualcomm Inc (QCOM)
Technically, Qualcomm Inc (QCOM) shows a MACD (12,26,9) value of 1.192, indicating a neutral signal. The RSI at 55.012 suggests neutral condition and the Williams %R at 10.699 suggests overbought condition. Please monitor closely.
Media Coverage of Qualcomm Inc (QCOM)
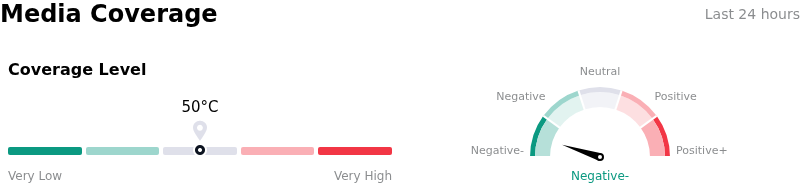
In terms of media coverage, Qualcomm Inc (QCOM) shows a coverage score of 50, indicating a moderate level of media attention. The overall market sentiment index is currently in extremely bearish zone.
Fundamental Analysis of Qualcomm Inc (QCOM)
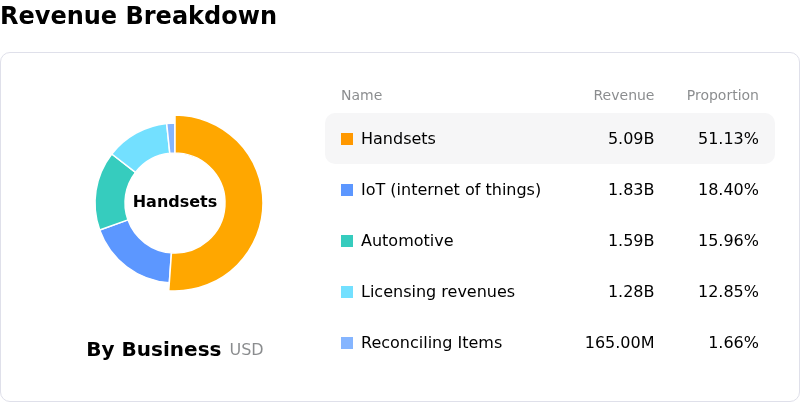
Qualcomm Inc (QCOM) is in the Technology Equipment industry. Its latest annual revenue is $43.12B, ranking 7 in the industry. The net profit is $13.63B, ranking 6 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Hold, with an average price target of $0.00, a high of $0.00, and a low of $0.00.
More details about Qualcomm Inc (QCOM)
Company Specific Risks:
- Analyst Downgrade and Prolonged Margin Compression: Freedom Broker downgraded Qualcomm from Buy to Hold and cut its price target to $185, warning that aggressive R&D spending and execution costs associated with scaling into AI PCs and data center silicon will depress corporate operating margins for longer than consensus anticipated.
- Severe Contraction in Core Handset Revenue and QCT Profitability: Institutional research desks have sharply lowered price targets following disclosures of a 26% year-over-year slump in smartphone chip sales, driven by global handset softness and rising component costs, which dragged guided QCT operating margins down to 20%–22%.
- Accelerating Apple Modem Revenue Disintermediation: Analysts continue to downgrade outlooks due to imminent customer concentration losses, as Apple prepares to halve its reliance on Qualcomm 5G modems in favor of in-house silicon, leaving a multi-billion-dollar top-line gap that automotive and IoT segments cannot immediately backfill.
- Increased Debt Load and Financing Costs from $4 Billion Debt Issuance: Regulatory filings confirmed Qualcomm priced a five-tranche, $4.0 billion senior notes offering with coupons as high as 5.80%, which expands financial leverage and permanently escalates ongoing debt-service expenses.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.