


Marvell Technology Inc Stock (MRVL) Moved Up by 11.87% on Nov 11: Facts Behind the Movement


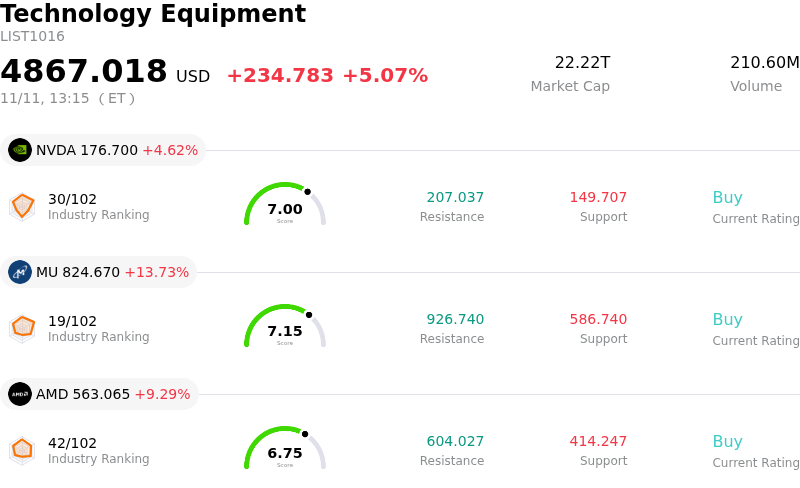
Marvell Technology Inc (MRVL) moved up by 11.87%. The Technology Equipment sector is up by 5.07%. The company outperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) up 4.60%; Micron Technology Inc (MU) up 13.73%; Advanced Micro Devices Inc (AMD) up 9.29%.
What is driving Marvell Technology Inc (MRVL)’s stock price up today?
Marvell Technology experienced a substantial surge driven primarily by accelerating institutional optimism surrounding its custom artificial intelligence silicon pipeline and cloud data center optical interconnect portfolio. Renewed confidence in multi-generational application-specific integrated circuit design wins with tier-one cloud service providers has reinforced market expectations that Marvell is cementing its position as an indispensable hardware enabler in hyperscale computing clusters. Strong demand indicators for high-speed electro-optics, optical digital signal processors, and custom accelerator programs served as a powerful upside catalyst, triggering aggressive buy-side accumulation across the semiconductor complex.
From an industry perspective, hyperscalers continue to accelerate the diversification of their compute architectures toward tailored custom silicon to optimize total cost of ownership and energy efficiency. Marvell remains exceptionally well positioned to capture this capital expenditure reallocation through its leading-edge physical layer interconnect intellectual property and advanced packaging capabilities. Concurrently, the relentless upgrade cycle toward higher-bandwidth data center networking has bolstered demand for Marvell’s optical interconnect solutions, helping to decisively overshadow historical cyclical lulls across legacy enterprise networking and carrier infrastructure end markets. As structurally higher-margin AI data center revenue increasingly dominates the company’s overall mix, valuation multiples have expanded alongside improved visibility into multi-year revenue runways.
Market sentiment and capital flows further amplified the upward momentum. Upward revisions to forward operational expectations by institutional analysts highlighted Marvell’s accelerating operating leverage and gross margin expansion profile as high-value cloud programs ramp into high-volume manufacturing. This positive fundamental reassessment prompted broad-based institutional reallocation and systematic momentum buying within top-tier semiconductor beneficiaries. While investors will remain attentive to execution timing on next-generation custom compute tape-outs, customer concentration, and advanced packaging foundry allocation, the prevailing narrative reflects an accelerating growth inflection powered by indispensable custom silicon and networking leadership.
Technical Analysis of Marvell Technology Inc (MRVL)
Technically, Marvell Technology Inc (MRVL) shows a MACD (12,26,9) value of -9.809, indicating a sell signal. The RSI at 39.747 suggests neutral condition and the Williams %R at 66.859 suggests sell condition. Please monitor closely.
Media Coverage of Marvell Technology Inc (MRVL)
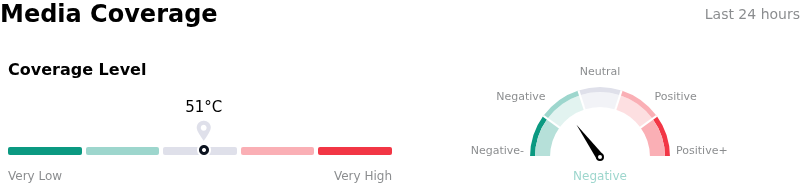
In terms of media coverage, Marvell Technology Inc (MRVL) shows a coverage score of 51, indicating a moderate level of media attention. The overall market sentiment index is currently in bearish zone.
Fundamental Analysis of Marvell Technology Inc (MRVL)
Marvell Technology Inc (MRVL) is in the Technology Equipment industry. Its latest annual revenue is $8.19B, ranking 19 in the industry. The net profit is $2.67B, ranking 13 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $314.95, a high of $450.00, and a low of $175.00.
More details about Marvell Technology Inc (MRVL)
Company Specific Risks:
- Substantial Shareholder Dilution from Lumentum Acquisition: Marvell's definitive all-stock agreement to acquire Lumentum for an implied enterprise value of $115 billion requires issuing 4.5 MRVL shares per Lumentum share, increasing outstanding shares by roughly 49% and diluting existing shareholders to approximately 67% ownership, driving heavy selling over per-share earnings dilution.
- Prolonged Regulatory Clearance and Geopolitical Closing Risks: With the transaction closing timeline extended out toward 2028, Marvell faces severe multi-year deal overhang and heightened antitrust regulatory risk, most notably securing critical approvals from China's SAMR amid ongoing cross-border semiconductor trade tensions.
- Ecosystem Friction and Optical Customer Conflicts: Institutional analysts flagged substantial channel risk, warning that acquiring Lumentum's laser, transceiver, and optical hardware businesses transforms Marvell into a direct competitor against its primary merchant digital signal processor (DSP) customers.
- Institutional Downgrades Over Premium Valuation: Major brokerages, including Bank of America and TD Cowen, downgraded MRVL and slashed price targets following the announcement, citing the steep valuation paid—roughly 33 times forward operating profitability—and heightened execution risk across custom silicon and optical architectures.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.