


KLA Corp Stock (KLAC) Moved Up by 6.50% on Nov 11: A Full Analysis


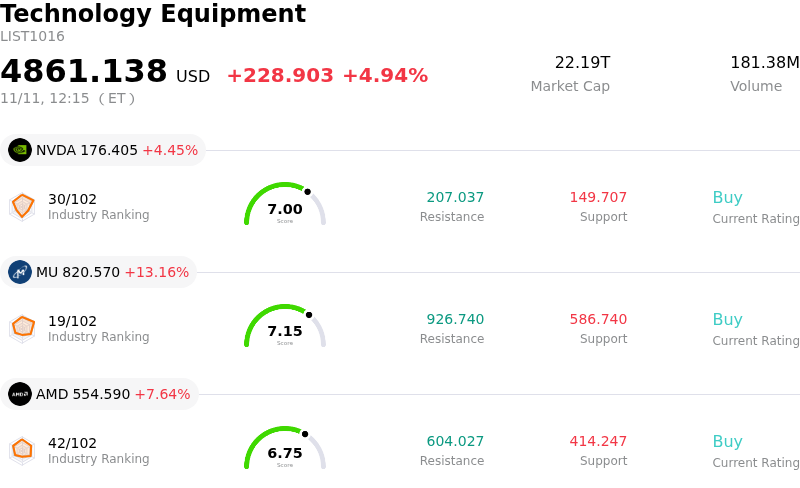
KLA Corp (KLAC) moved up by 6.50%. The Technology Equipment sector is up by 4.94%. The company outperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) up 4.56%; Micron Technology Inc (MU) up 13.19%; Advanced Micro Devices Inc (AMD) up 7.64%.
What is driving KLA Corp (KLAC)’s stock price up today?
Shares of KLA Corporation advanced sharply during intraday trading, buoyed by a robust rebound across the semiconductor equipment complex and renewed institutional conviction in the structural durability of wafer fabrication capital expenditures. Following a period of sector-wide valuation compression and oversold technical conditions, buyers stepped in aggressively, supported by reassuring demand signals across leading-edge foundry, logic, and high-bandwidth memory manufacturing. Investor sentiment was further amplified by broader market recognition that process control spending remains one of the most resilient and non-discretionary segments within hardware technology.
The primary catalyst supporting the stock is the accelerating capital allocation toward advanced packaging and sub-three-nanometer node transitions. As chipmakers implement complex architectures such as gate-all-around transistors and multi-die chiplet integration, defect density risks multiply exponentially, necessitating significantly higher inspection and metrology intensity per wafer. Because yield management directly dictates economic profitability for tier-one foundries and memory producers, KLA benefits from defensive pricing power and structural market share dominance in optical inspection and patterned defect detection. Upbeat commentary regarding multi-year wafer fab equipment growth and expanding equipment backlogs has reinforced confidence that customer tool orders are accelerating rather than slowing.
Fundamental support was reinforced by solid operational execution and disciplined balance sheet management, as evidenced by recent credit rating upgrades citing expanding operating margins and sustainable cash generation. KLA’s high-margin equipment profile, coupled with a growing recurring revenue base from its installed-base services business, provides superior earnings visibility compared to more commoditized fabrication peers. This operational insulation shields the company from cyclical volatility while positioning it for substantial operating leverage as artificial intelligence hardware infrastructure spending broadens.
Despite the strong upward trajectory, institutional investors continue to monitor key risks, including potential export control revisions impacting advanced tool shipments to international markets and customer concentration among major foundry and memory manufacturers. Elevated valuation multiples also leave the equity sensitive to broader technology sector multiple resets. Nonetheless, today’s pronounced advance demonstrates institutional rotation back into core semiconductor enablers, reflecting strong confidence in KLA’s indispensable role in driving next-generation silicon manufacturing yields.
Technical Analysis of KLA Corp (KLAC)
Technically, KLA Corp (KLAC) shows a MACD (12,26,9) value of 2.489, indicating a neutral signal. The RSI at 50.736 suggests neutral condition and the Williams %R at 19.237 suggests overbought condition. Please monitor closely.
Media Coverage of KLA Corp (KLAC)
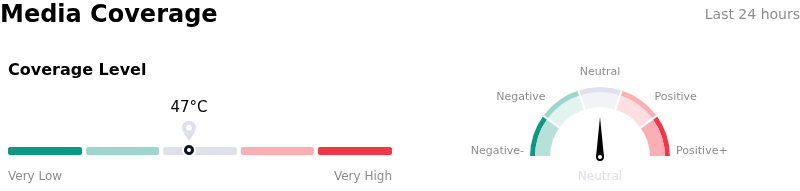
In terms of media coverage, KLA Corp (KLAC) shows a coverage score of 47, indicating a moderate level of media attention. The overall market sentiment index is currently in neutral zone.
Fundamental Analysis of KLA Corp (KLAC)
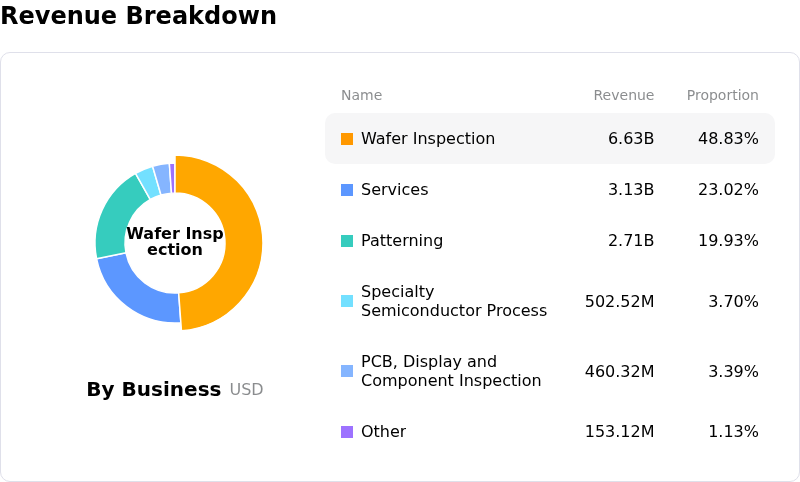
KLA Corp (KLAC) is in the Technology Equipment industry. Its latest annual revenue is $13.58B, ranking 15 in the industry. The net profit is $4.83B, ranking 11 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $214.38, a high of $275.00, and a low of $138.80.
More details about KLA Corp (KLAC)
Company Specific Risks:
- China Revenue Exposure and Domestic Tool Substitution: Reports indicating that major Chinese memory chipmakers are aggressively accelerating the adoption of domestic wafer fabrication and inspection tools pose an acute threat to KLA's elevated China revenue exposure (accounting for approximately 26% of total revenue), heightening the risk of order cancellations and stricter trade curbs.
- Supply Chain and Cleanroom Delivery Bottlenecks: Lingering component shortages and cleanroom capacity constraints are creating delivery bottlenecks, threatening to constrain advanced process-control equipment shipments into 2027 and risking margin degradation on delayed system integrations.
- Analyst Valuation Multiples De-Rating: Institutional research desks have sharply cut price-target multiples—compressing earnings multiples toward 28x from 36x—citing an overvalued trailing P/E relative to near-term wafer fabrication equipment spending cycles and potential moderation in high-margin leading-logic intensity.
- Prolonged Executive Insider Liquidations: Regulatory disclosures highlighting cumulative insider disposals exceeding $112 million with zero insider purchases over recent periods have triggered institutional selling pressure, raising governance concerns regarding top-line durability at the current point in the semiconductor equipment cycle.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.