


Dell Technologies Inc Stock (DELL) Moved Up by 13.84% on Nov 11: Drivers Behind the Movement


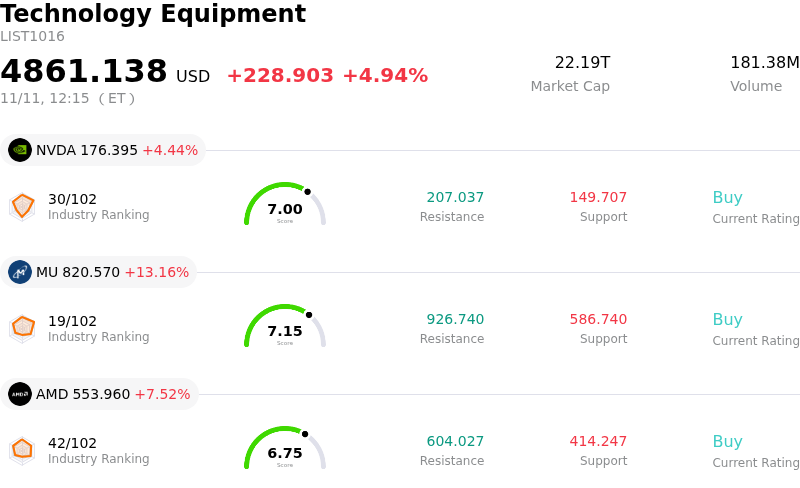
Dell Technologies Inc (DELL) moved up by 13.84%. The Technology Equipment sector is up by 4.94%. The company outperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) up 4.56%; Micron Technology Inc (MU) up 13.19%; Advanced Micro Devices Inc (AMD) up 7.64%.
What is driving Dell Technologies Inc (DELL)’s stock price up today?
Dell Technologies experienced a sharp upward move during trading, driven by accelerating institutional demand and a powerful catalyst across its core enterprise AI infrastructure business. Market sentiment turned decidedly bullish as investors reacted to expanding order books for high-performance AI servers and indications of robust commercial execution. Strong performance within the Infrastructure Solutions Group has reaffirmed the company's leadership position in capitalizing on the massive, ongoing buildout of enterprise-grade compute and generative AI architectures.
A key fundamental driver behind the rally is the continued scaling of its AI-optimized server lineup, which has seen substantial order intake from tier-two cloud service providers, enterprise clients, and sovereign cloud initiatives. Sustained backlog growth and improved supply chain delivery cycles for cutting-edge accelerators have allowed the company to convert intense hardware demand into accelerating top-line expansion and resilient operating margins. Furthermore, deeper collaboration with premier chipmakers on integrated AI factory deployments has broadened the company's addressable enterprise market, dampening prior market concerns over margin dilution and demonstrating durable pricing power in complex liquid-cooled and dense compute solutions.
At the industry level, investor confidence was further reinforced by signs of cyclical stabilization in broader enterprise hardware spending. The commercial client segment is demonstrating steady improvement, supported by aging enterprise installed bases and corporate refresh cycles transitioning toward AI-capable endpoints. This stabilization within the Client Solutions Group provides a more balanced earnings profile, ensuring that cash generation remains robust across both server and client computing divisions.
From a capital markets perspective, the stock received additional momentum from widespread positive analyst commentary, target price revisions, and institutional portfolio reallocation. Institutional market participants increasingly view the firm as one of the most operationally sound and cash-generative beneficiaries of the enterprise artificial intelligence infrastructure wave, especially given management's commitment to returning substantial free cash flow to shareholders via buybacks and dividends. With market appetite for profitable hardware enablers remaining strong, positive momentum continues to be anchored by high visibility into multi-quarter order pipelines and disciplined operational execution.
Technical Analysis of Dell Technologies Inc (DELL)
Technically, Dell Technologies Inc (DELL) shows a MACD (12,26,9) value of -15.683, indicating a sell signal. The RSI at 41.114 suggests neutral condition and the Williams %R at 65.813 suggests sell condition. Please monitor closely.
Media Coverage of Dell Technologies Inc (DELL)
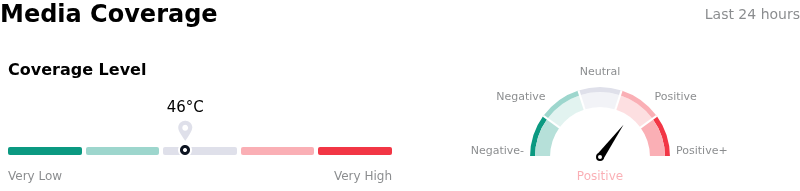
In terms of media coverage, Dell Technologies Inc (DELL) shows a coverage score of 46, indicating a moderate level of media attention. The overall market sentiment index is currently in bullish zone.
Fundamental Analysis of Dell Technologies Inc (DELL)
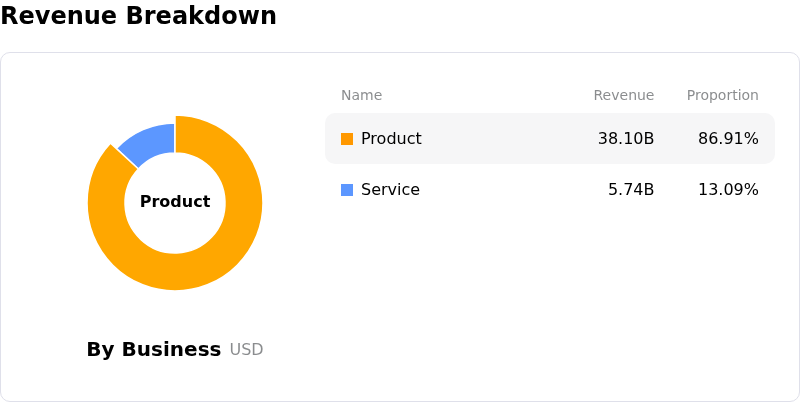
Dell Technologies Inc (DELL) is in the Technology Equipment industry. Its latest annual revenue is $113.54B, ranking 2 in the industry. The net profit is $5.94B, ranking 4 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $588.12, a high of $700.00, and a low of $499.80.
More details about Dell Technologies Inc (DELL)
Company Specific Risks:
- AI Server Operating Margin Compression: Mounting analyst scrutiny indicates that Dell's top-line surge in AI-optimized server revenue is largely driven by passing through elevated component and memory costs rather than high-margin proprietary enterprise solutions, leaving AI server operating margins tethered near 5% and diluting consolidated gross profitability as server volumes scale.
- Neocloud Customer Concentration and Backlog Conversion: A significant portion of Dell's enterprise hardware order backlog relies on debt-reliant neocloud vendors and specialized cloud providers, exposing Dell to delivery deferrals or order cancellation risks if key customers face liquidity crunches or escalating debt servicing costs before converting bookings into cash flow.
- Data Center Regulatory and Grid Constraints: Escalating municipal and policy scrutiny over hyperscale electricity consumption and localized grid limits—specifically including proposed municipal data center restrictions in Texas—threatens to stall customer site readiness, creating delivery bottlenecks and delaying hardware deployment timelines.
- Client Solutions Group (CSG) Margin Attrition: Lingering enterprise sluggishness across commercial PC refresh cycles, paired with rising component procurement input costs, restricts cash generation and profitability in Dell's Client Solutions segment, reducing its historical ability to subsidize lower-margin infrastructure buildouts.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.