


NVIDIA Corp Stock (NVDA) Moved Up by 3.88% on Nov 11: Facts Behind the Movement


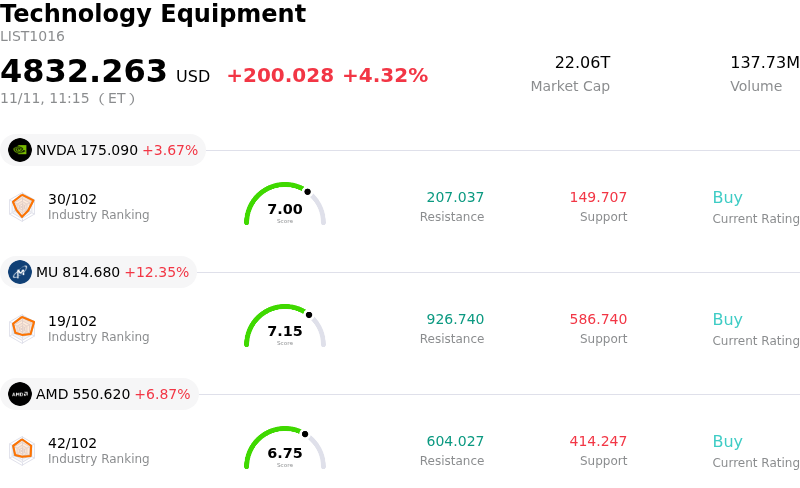
NVIDIA Corp (NVDA) moved up by 3.88%. The Technology Equipment sector is up by 4.32%. The company underperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) up 3.88%; Micron Technology Inc (MU) up 12.68%; Advanced Micro Devices Inc (AMD) up 7.07%.
What is driving NVIDIA Corp (NVDA)’s stock price up today?
Nvidia recorded strong gains today as robust institutional demand and renewed optimism across the accelerated computing sector propelled the stock higher. The upward momentum is largely underpinned by sustained capital expenditure commitments from major cloud hyperscalers and tier-one enterprise customers. As large-scale artificial intelligence model training and inference deployments expand globally, demand for advanced data center graphics processors and full-stack computing platforms continues to outpace broader semiconductor cyclicality. Investors reacted favorably to ongoing channel checks indicating accelerating rack-scale deployments and solid production yields across advanced silicon architectures.
Complementing hardware demand, the company’s enterprise networking and software monetization engines are providing additional top-line stability and margin insulation. Rapid enterprise adoption of high-throughput networking solutions, coupled with recurring enterprise software licenses, is deepening customer lock-in within the proprietary software ecosystem. Furthermore, easing packaging constraints across leading semiconductor foundry partners has enhanced component availability, allowing Nvidia to fulfill backlogged data center orders more efficiently and reducing market concerns over supply chain bottlenecks.
From a macroeconomic and market structure standpoint, broader tech sentiment was bolstered by a supportive liquidity environment and steady institutional capital reallocation back into high-beta mega-cap leaders. Ahead of upcoming corporate earnings releases, sell-side analysts have broadly reiterated constructive price targets, citing durable pricing power and visibility into sovereign computing initiatives as key structural tailwinds. This combination of upward earnings revisions and steady institutional accumulation has fueled intraday short-covering and sustained buying pressure.
Looking ahead, institutional investors will closely monitor upcoming quarterly revenue guidance, gross margin trajectory, and commentary on product transition timelines. While execution risk, export restriction compliance, and power infrastructure availability in global data centers remain pertinent risk factors, the current price action highlights persistent investor confidence in Nvidia as the foundational backbone of enterprise computing infrastructure.
Technical Analysis of NVIDIA Corp (NVDA)
Technically, NVIDIA Corp (NVDA) shows a MACD (12,26,9) value of -7.986, indicating a sell signal. The RSI at 30.140 suggests neutral condition and the Williams %R at 82.662 suggests oversold condition. Please monitor closely.
Media Coverage of NVIDIA Corp (NVDA)
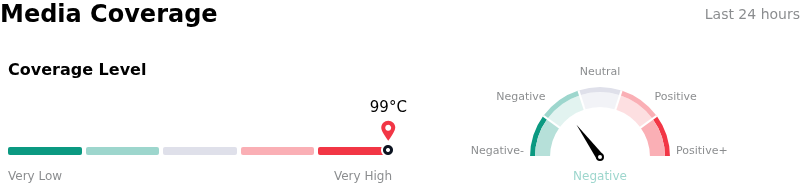
In terms of media coverage, NVIDIA Corp (NVDA) shows a coverage score of 99, indicating a very high level of media attention. The overall market sentiment index is currently in bearish zone.
Fundamental Analysis of NVIDIA Corp (NVDA)
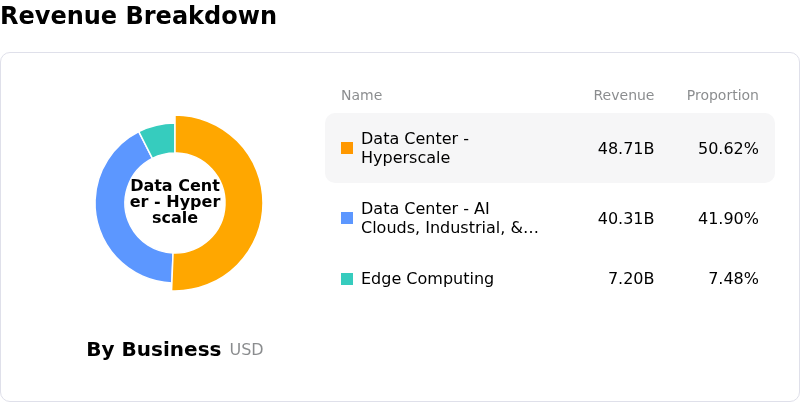
NVIDIA Corp (NVDA) is in the Technology Equipment industry. Its latest annual revenue is $215.94B, ranking 1 in the industry. The net profit is $120.07B, ranking 1 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $323.83, a high of $515.00, and a low of $180.00.
More details about NVIDIA Corp (NVDA)
Company Specific Risks:
- Executive Continuity and Governance Inquiry: An independent board review and federal inquiry into CEO Jensen Huang regarding interactions linked to foreign intelligence concerns have intensified key-person governance risk, triggering heightened leadership uncertainty, congressional scrutiny, and shareholder class-action filings.
- Export Restrictions and Severe Inventory Write-Down Risk: Heightened threat of expanded U.S. export bans on H200 shipments and regulatory crackdowns on Southeast Asian intermediary channels threaten to disrupt 10% to 30% of sales exposure, risking up to a $5 billion potential inventory write-down.
- Institutional Downgrades on Decelerating Data Center Visibility: Major Wall Street downgrades—including Baird cutting the stock to Neutral and reducing its price target from $500 to $200, alongside Morgan Stanley removing it from its Top Pick list—point to diminishing visibility into 2027 demand and an anticipated slowdown in hyperscaler AI capital expenditure growth.
- Escalating Financial Liabilities in Partner Guarantees: Mounting commitments under the AI Computing Partner program have escalated to roughly $165 billion—including over $100 billion in infrastructure guarantees for regional data center builds—exposing the company to structural counterparty credit risk if neocloud capital windows contract.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.