


Arista Networks Inc Stock (ANET) Moved Up by 5.31% on Nov 11: Facts Behind the Movement


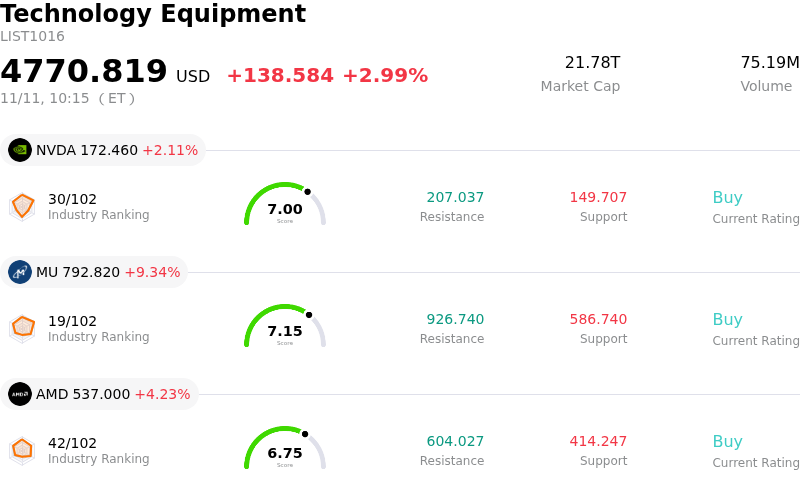
Arista Networks Inc (ANET) moved up by 5.31%. The Technology Equipment sector is up by 2.99%. The company outperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) up 1.97%; Micron Technology Inc (MU) up 9.24%; Advanced Micro Devices Inc (AMD) up 4.01%.
What is driving Arista Networks Inc (ANET)’s stock price up today?
Arista Networks witnessed a strong upward surge driven by robust institutional demand, underpinned by sustained operational momentum and accelerating capital spending across cloud networking and artificial intelligence infrastructure. Investors responded favorably to management's constructive demand outlook, which highlighted expanding deployments of Ethernet-based AI clusters among major hyperscale customers and enterprise clients.
A primary catalyst for the stock's outperformance is the broader capital expenditure cycle among cloud titans, notably Microsoft and Meta, who continue to prioritize AI data center buildouts. Arista remains a core beneficiary of the industry transition from proprietary interconnect architectures, such as InfiniBand, toward open Ultra Ethernet fabrics. Strong execution in high-bandwidth 800G switching platforms and early traction in next-generation 1.6T networking products have reinforced the company’s competitive moat, supporting favorable gross margin resilience and operating leverage.
Institutional appetite was also buoyed by a wave of positive Wall Street commentary and upward target price revisions. Following a period of broader semiconductor and hardware consolidation, market participants actively accumulated shares of high-quality AI infrastructure providers. Arista’s pristine balance sheet, characterized by substantial cash reserves and an absence of long-term debt, provides significant operational flexibility and downside protection, making it an attractive institutional vehicle in an otherwise volatile technology tape.
Looking ahead, while the mid-to-long-term growth narrative surrounding AI back-end fabrics remains intact, investors should monitor customer concentration risk, as hyperscaler spending patterns can produce lumpy deployment cycles. Additionally, competitive maneuvers from integrated silicon vendors and white-box switch manufacturers warrant close observation to evaluate whether Arista can sustain its premium valuation multiple over the coming quarters.
Technical Analysis of Arista Networks Inc (ANET)
Technically, Arista Networks Inc (ANET) shows a MACD (12,26,9) value of 4.625, indicating a neutral signal. The RSI at 55.738 suggests neutral condition and the Williams %R at 9.957 suggests overbought condition. Please monitor closely.
Media Coverage of Arista Networks Inc (ANET)
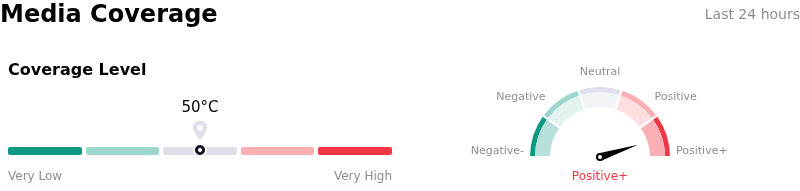
In terms of media coverage, Arista Networks Inc (ANET) shows a coverage score of 50, indicating a moderate level of media attention. The overall market sentiment index is currently in extremely bullish zone.
Fundamental Analysis of Arista Networks Inc (ANET)
Arista Networks Inc (ANET) is in the Technology Equipment industry. Its latest annual revenue is $9.01B, ranking 5 in the industry. The net profit is $3.51B, ranking 2 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $242.44, a high of $291.00, and a low of $140.00.
More details about Arista Networks Inc (ANET)
Company Specific Risks:
- Substantial Insider Liquidation: Recent SEC Form 4 filings revealed that key 10% owner Andreas Bechtolsheim offloaded $43.93 million worth of common stock (260,000 shares), compounding negative sentiment around executive profit-taking near all-time valuation peaks.
- Surging Purchase Commitments and Balance Sheet Exposure: Balance sheet disclosures highlight that supplier purchase commitments jumped sharply to $11.4 billion (up from $9.7 billion in Q2) while inventory climbed to $3.2 billion, escalating component liability and cash-flow risks if hyperscale deployment timing slows.
- Gross Margin Compression: Non-GAAP gross margin contracted year-over-year to 64.0% (down from 65.2%), with forward guidance projecting further compression toward 62% to 64% as competitive pricing pressure from Nvidia’s Spectrum-X and Cisco’s Silicon One intensifies in the AI networking fabric space.
- Heightened Hyperscaler Revenue Concentration: Disclosures indicate that at least three to four top customers will each generate over 10% of total revenue, exposing top-line growth to acute downside volatility if even one cloud titan throttles, delays, or reallocates AI infrastructure capital expenditures.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.