


Lam Research Corp Stock (LRCX) Moved Up by 4.71% on Nov 11: What Signal Does It Send?


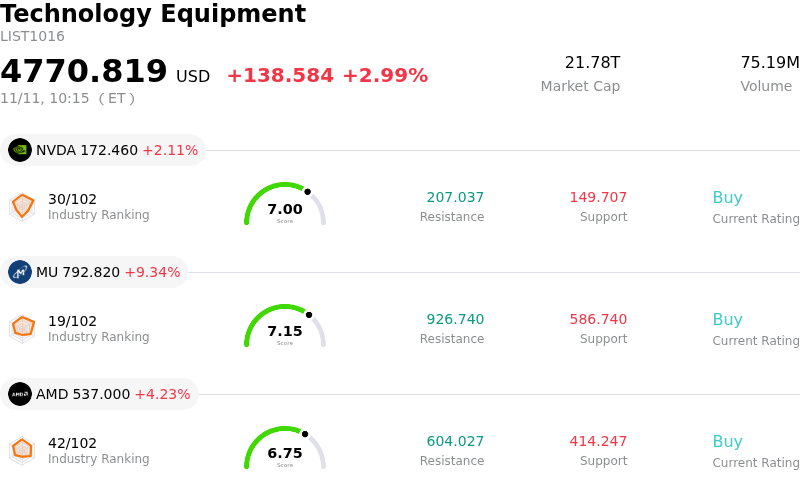
Lam Research Corp (LRCX) moved up by 4.71%. The Technology Equipment sector is up by 2.99%. The company outperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) up 1.97%; Micron Technology Inc (MU) up 9.24%; Advanced Micro Devices Inc (AMD) up 4.01%.
What is driving Lam Research Corp (LRCX)’s stock price up today?
Lam Research Corporation experienced notable upward momentum during the trading session, reflecting a confluence of supportive industry dynamics, robust capital expenditure expectations across the semiconductor supply chain, and favorable institutional sentiment. As a premier provider of wafer fabrication equipment specializing in etch and deposition processes, the company remains uniquely positioned to capture accelerating spending tied to artificial intelligence infrastructure and advanced memory transitions.
A primary catalyst fueling the positive movement is renewed optimism surrounding the recovery and structural expansion of memory equipment spending. Demand for high-bandwidth memory and high-density storage solutions has prompted leading memory manufacturers to accelerate investments in next-generation DRAM and advanced multi-layer 3D NAND architectures. Because vertical scaling in memory chips requires increasingly precise and complex etch and deposition capabilities, Lam Research stands as a direct beneficiary of rising process tool intensity. Market participants are increasingly pricing in an extended equipment spending cycle supported by hyperscaler capital expenditure expansion.
Sentiment has also been bolstered by positive sell-side commentary and institutional portfolio adjustments across the broader semiconductor capital equipment sector. Analysts have highlighted improving fab utilization rates, expanding equipment order backlogs, and solid margin resilience driven by the company's proprietary technological advantages, such as specialized cryogenic etching platforms. Furthermore, the recurring nature of Lam Research’s customer support business group continues to provide high-margin cash flows and operational insulation, dampening cyclical volatility and reinforcing institutional confidence.
Broader macro conditions and market risk appetite also provided tailwinds for semiconductor equipment leaders. Easing interest rate uncertainty and steady risk-on sentiment across growth sectors have encouraged capital rotation into high-quality tech names with clear secular demand drivers. While geopolitical trade regulations and localized supply chain developments remain monitorable risk factors, the prevailing market focus on accelerating AI hardware roadmaps and technology inflections has reinforced a favorable risk-reward profile for Lam Research over the near term.
Technical Analysis of Lam Research Corp (LRCX)
Technically, Lam Research Corp (LRCX) shows a MACD (12,26,9) value of 1.232, indicating a neutral signal. The RSI at 43.961 suggests neutral condition and the Williams %R at 36.262 suggests buy condition. Please monitor closely.
Media Coverage of Lam Research Corp (LRCX)
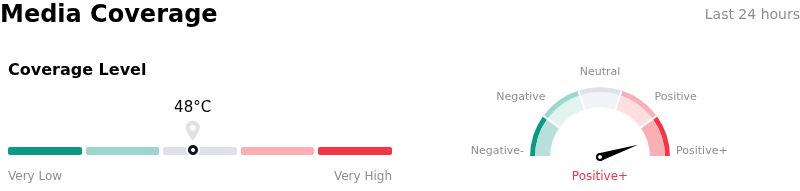
In terms of media coverage, Lam Research Corp (LRCX) shows a coverage score of 48, indicating a moderate level of media attention. The overall market sentiment index is currently in extremely bullish zone.
Fundamental Analysis of Lam Research Corp (LRCX)
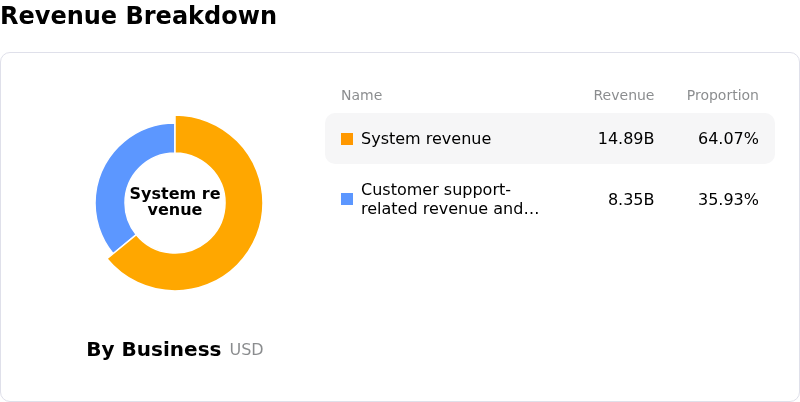
Lam Research Corp (LRCX) is in the Technology Equipment industry. Its latest annual revenue is $23.23B, ranking 12 in the industry. The net profit is $7.27B, ranking 8 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $358.02, a high of $500.00, and a low of $213.00.
More details about Lam Research Corp (LRCX)
Company Specific Risks:
- Supply Chain and Fab Capacity Bottlenecks: Critical component shortages and customer clean-room space constraints are actively capping equipment build and delivery schedules, forcing management to issue forward guidance below elevated institutional whisper numbers and delaying equipment conversion into revenue.
- Projected Revenue Contraction from China: Following an elevated contribution of roughly 35% of total revenue in recent quarters, Lam cautioned that Chinese revenue is facing a steep sequential contraction due to regulatory export restrictions and the normalization of regional wafer fabrication equipment spending.
- High Sensitivity to Memory Capex Cycles: Lam remains heavily weighted toward NAND and DRAM equipment spending relative to peers, leaving revenue and order backlogs exposed to sudden equipment order pushouts or budget reallocations among top memory customers.
- Multiples Compression from Wall Street Target Cuts: Cautious forward outlook commentary prompted multiple tier-one brokerages to trim price targets, creating intraday selling pressure and triggering valuation reassessments amid broader scrutiny over the pace of AI infrastructure monetization.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.