


Micron Technology Inc Stock (MU) Opened Up by 7.35% on Nov 11: Key Drivers Unveiled


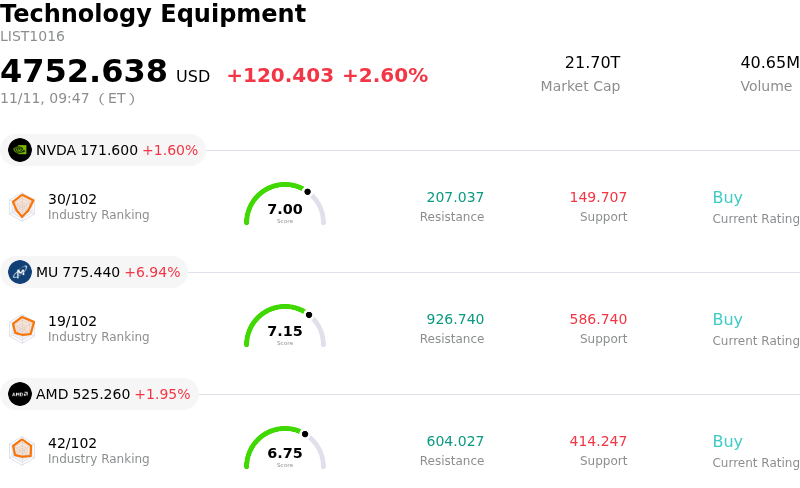
Micron Technology Inc (MU) opened up by 7.35%. The Technology Equipment sector is up by 2.60%. The company outperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) up 1.62%; Micron Technology Inc (MU) up 7.35%; Advanced Micro Devices Inc (AMD) up 2.28%.
What is driving Micron Technology Inc (MU)’s stock price up today?
Micron Technology experienced robust upward momentum during the trading session, underpinned by strengthening fundamentals across the broader memory ecosystem and renewed investor enthusiasm surrounding artificial intelligence hardware infrastructure. As global cloud service providers and enterprise hyperscalers continue to accelerate their investments in accelerated computing clusters, Micron remains a direct beneficiary of the structural demand pivot toward advanced memory solutions, most notably High Bandwidth Memory and high-capacity server DRAM modules.
A critical catalyst fueling the rally is the continued tightening of supply-demand dynamics in the DRAM market. The production ramp of next-generation HBM architectures consumes significantly more wafer capacity than traditional DDR5 memory, effectively cannibalizing industry wafer availability for standard commercial and client applications. This supply constraint has reinforced pricing leverage for memory producers, accelerating contract price improvements and boosting consensus expectations for near-term gross margin expansion. Investors are increasingly viewing the current cycle as distinct from historical boom-and-bust patterns, driven by higher-margin, customer-specific enterprise contracts that provide improved revenue visibility.
Institutional sentiment has also been reinforced by favorable commentary from Wall Street research desks, where several brokerages have recently lifted earnings per share projections and revised target prices upward. Analysts point to Micron’s disciplined capital expenditure strategy and strategic execution on leading-edge fabrication nodes as evidence of structural operational leverage. The company’s ability to secure long-term purchase commitments with leading graphics processing unit suppliers further insulates its order book, drawing sustained institutional inflows into large-cap semiconductor leaders.
While the medium-term outlook remains constructive, market participants must continue to monitor broader macroeconomic crosscurrents, particularly the pacing of end-market demand recovery in consumer personal computers and smartphones, which have historically exhibited cyclical softness relative to datacenter hardware. Additionally, execution risks surrounding the transition to next-generation HBM nodes and potential capacity additions from regional competitors remain noteworthy variables. Nonetheless, the prevailing market action reflects growing confidence in Micron’s expanded profitability trajectory and dominant positioning within the generative AI hardware supply chain.
Technical Analysis of Micron Technology Inc (MU)
Technically, Micron Technology Inc (MU) shows a MACD (12,26,9) value of -24.374, indicating a sell signal. The RSI at 41.372 suggests neutral condition and the Williams %R at 63.718 suggests sell condition. Please monitor closely.
Media Coverage of Micron Technology Inc (MU)
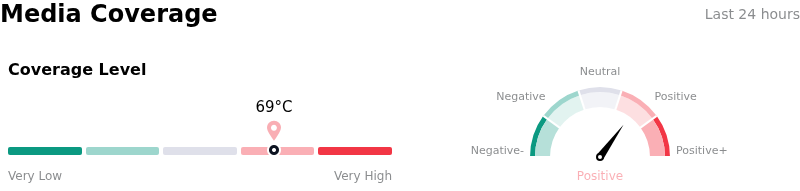
In terms of media coverage, Micron Technology Inc (MU) shows a coverage score of 69, indicating a high level of media attention. The overall market sentiment index is currently in bullish zone.
Fundamental Analysis of Micron Technology Inc (MU)
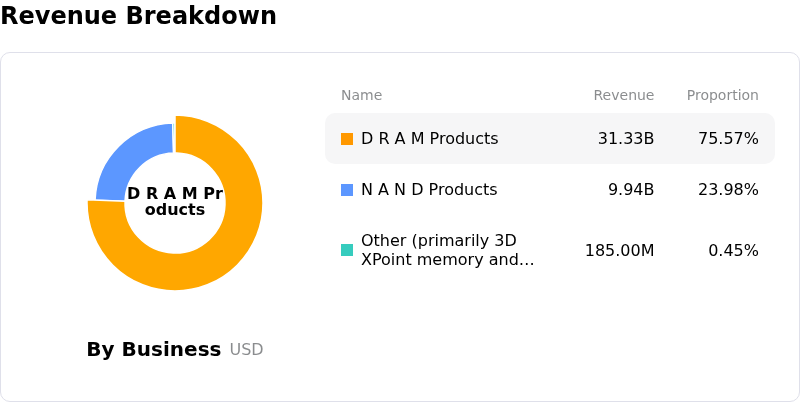
Micron Technology Inc (MU) is in the Technology Equipment industry. Its latest annual revenue is $133.19B, ranking 2 in the industry. The net profit is $84.97B, ranking 2 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $1538.93, a high of $3000.00, and a low of $361.00.
More details about Micron Technology Inc (MU)
Company Specific Risks:
- Taiwan Facility Construction Halt and Labor Disruption: Micron suspended construction on its $4.5 billion Taoyuan fabrication plant amid an escalating union dispute over profit-sharing demands, jeopardizing next-generation capacity expansion in a jurisdiction that accounts for roughly 60% of the company's total DRAM manufacturing base.
- Ramping Capacity and Market-Share Pressure from Competitors: Aggressive DRAM and high-bandwidth memory capacity expansions by key rivals—including Samsung, SK Hynix, and rapidly scaling Chinese manufacturer CXMT—threaten to diminish Micron's pricing power and compress gross margins across both commoditized and high-density memory segments.
- Decelerating Contract Pricing and Cyclical Peak Headwinds: Institutional analysts have voiced caution over peak-cycle dynamics, pointing to moderating quarter-over-quarter price appreciation in conventional DRAM and NAND flash contracts that leaves Micron acutely exposed to oversupply risks.
- Downside Vulnerability to Hyperscale CapEx Deferrals: Analyst warnings estimating that up to 30% of scheduled enterprise and cloud data center buildouts face timeline delays risk slowing the consumption rate for advanced server memory and premium HBM products, threatening forward revenue visibility.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.