


Arm Holdings PLC Stock (ARM) Moved Up by 3.79% on Nov 6: Key Drivers Unveiled


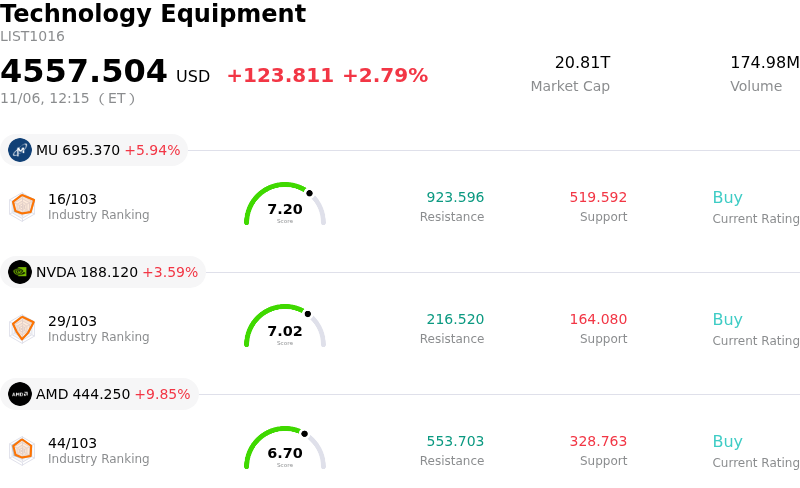
Arm Holdings PLC (ARM) moved up by 3.79%. The Technology Equipment sector is up by 2.79%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Micron Technology Inc (MU) up 5.98%; NVIDIA Corp (NVDA) up 3.57%; Advanced Micro Devices Inc (AMD) up 9.82%.
What is driving Arm Holdings PLC (ARM)’s stock price up today?
Arm Holdings experienced solid upward momentum as institutional investors digested the company's latest quarterly financial report and looked past initial concerns regarding forward guidance. The primary fundamental support stemmed from an earnings and revenue performance that topped Wall Street expectations, powered by substantial strength in intellectual property licensing. After absorbing initial volatility surrounding conservative near-term projections, market participants recalibrated their focus toward the company's accelerating monetization across artificial intelligence and cloud computing.
The core catalyst driving optimism is the rapid structural expansion of Arm architecture within enterprise data centers and generative AI infrastructure. Licensing revenue demonstrated robust growth as major technology customers expanded long-term commitments to access advanced design portfolios. Concurrently, data center royalties showed powerful momentum, reflecting rising server deployment share among top hyperscale cloud providers and deepened integration into high-performance platforms, including custom silicon initiatives from Amazon and Nvidia. Management commentary reinforcing strong commercial traction and multi-year purchase orders for proprietary advanced computing silicon provided investors with clearer medium-term revenue visibility, supporting expectations for sustained top-line acceleration.
The rebound was further amplified by favorable analyst assessments and institutional dip-buying following post-earnings selling pressure. Although softer smartphone royalty dynamics and a measured quarterly guidance range initially prompted caution, Wall Street quickly recognized that the secular shift toward higher-royalty architecture versions and expanding data center footprints outweighed cyclical mobile sector headwinds. Expanding operating margins and the durable secular tailwinds of AI compute demand reasserted confidence in Arm's premium valuation, driving broad-based accumulation throughout the trading session.
Technical Analysis of Arm Holdings PLC (ARM)
Technically, Arm Holdings PLC (ARM) shows a MACD (12,26,9) value of -8.955, indicating a sell signal. The RSI at 30.322 suggests neutral condition and the Williams %R at 86.783 suggests oversold condition. Please monitor closely.
Fundamental Analysis of Arm Holdings PLC (ARM)
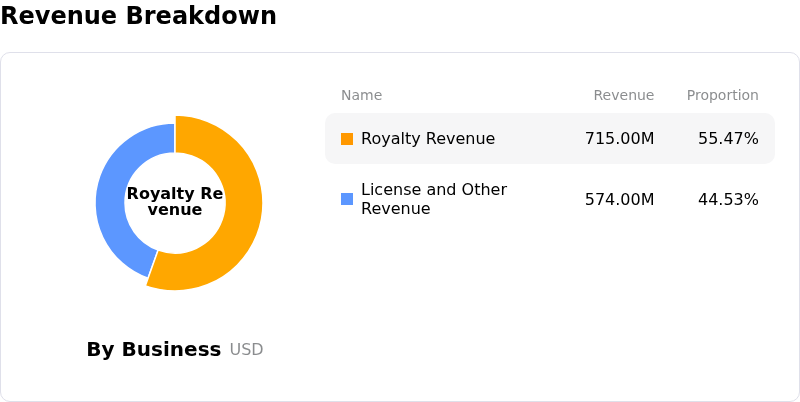
Arm Holdings PLC (ARM) is in the Technology Equipment industry. Its latest annual revenue is $4.92B, ranking 24 in the industry. The net profit is $904.00M, ranking 18 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $0.00, a high of $0.00, and a low of $0.00.
More details about Arm Holdings PLC (ARM)
Company Specific Risks:
- Royalty Revenue Deceleration and Mobile Market Drag: In its latest quarterly earnings release, royalty revenue rose only 8% year-over-year to $670 million—missing institutional consensus of approximately $721 million and marking its slowest growth in eight quarters—due to an unexpected 6.3% sequential decline driven by high memory costs and ongoing smartphone demand softness.
- Subdued Forward Guidance and Operating Margin Compression: Fiscal Q3 revenue guidance of $1.54 billion and adjusted EPS guidance of $0.56 only marginally matched Street consensus ($1.53 billion and $0.55), failing to satisfy elevated growth expectations while projected adjusted operating expenses surged to $825 million, triggering analyst price target cuts due to anticipated margin compression.
- Persistent Qualcomm Architectural Litigation Overhang: Institutional analysts flagged the unresolved high-stakes licensing and royalty dispute with key customer Qualcomm as an acute risk factor, as any potential suspension of royalty payments or adverse court ruling would materially impair a core pillar of Arm's recurring licensing and royalty cash flows.
- SoftBank Margin Loan Leverage and Multiple Contraction Vulnerability: The stock's elevated trading multiple leaves it acutely exposed to institutional de-risking, an effect magnified by majority stakeholder SoftBank securing $25 billion in margin loans against its Arm equity stake, which introduces structural collateral liquidation risks and heightened price sensitivity during sustained sector drawdowns.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles










Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.