


Dell Technologies Inc Stock (DELL) Moved Up by 5.42% on Nov 6: A Full Analysis


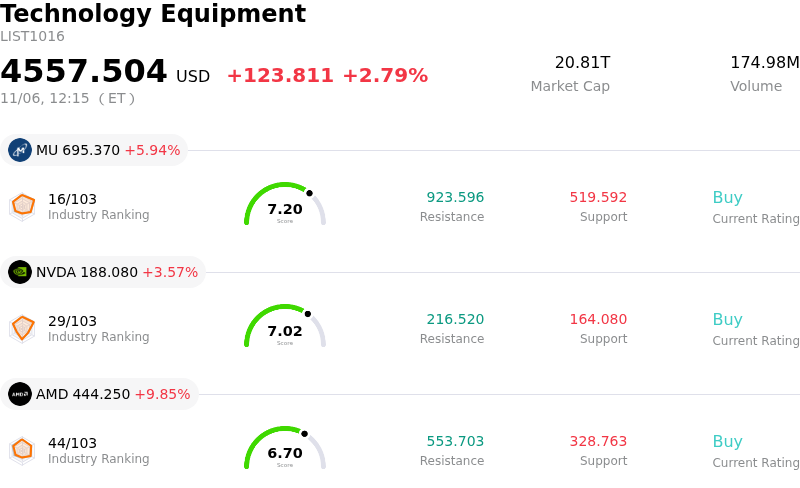
Dell Technologies Inc (DELL) moved up by 5.42%. The Technology Equipment sector is up by 2.79%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Micron Technology Inc (MU) up 5.98%; NVIDIA Corp (NVDA) up 3.57%; Advanced Micro Devices Inc (AMD) up 9.82%.
What is driving Dell Technologies Inc (DELL)’s stock price up today?
Dell Technologies experienced robust upward momentum during today’s trading session, driven primarily by accelerating enterprise demand for artificial intelligence hardware infrastructure and an increasingly constructive outlook for enterprise IT spending. Institutional sentiment around Dell continues to strengthen as enterprise customers scale their deployment of generative AI workloads, fueling higher demand for high-performance, liquid-cooled AI servers within the company’s Infrastructure Solutions Group.
A central catalyst behind the rally is the sustained expansion of Dell’s AI server order backlog and pipeline visibility. Strong enterprise adoption of next-generation server architectures, supported by robust component availability and deep partnerships with leading semiconductor vendors, has reassured investors regarding sustained top-line expansion in enterprise infrastructure. Market participants are increasingly viewing Dell not merely as a traditional hardware vendor, but as an indispensable end-to-end integrator capable of delivering complex data center solutions, storage systems, and specialized networking to enterprise and sovereign AI clients.
In parallel, sentiment has been bolstered by stabilizing fundamentals across the Client Solutions Group. The commercial PC refresh cycle is gaining traction as enterprises modernize aging device fleets to support local AI processing capabilities and transition away from legacy operating platforms. This commercial replacement cycle provides a resilient foundation of recurring enterprise cash flow, which complements the high-growth trajectory of the data center business and helps mitigate margin volatility.
Positive institutional positioning and favorable analyst commentary have also contributed to the advance. Wall Street research desks have continued to reiterate constructive views on Dell’s operational efficiency, highlighting working capital optimization and disciplined cost management that support robust free cash flow generation. This strong cash profile reinforces Dell’s commitment to shareholder returns via sustained share repurchases and consistent dividend growth.
Looking ahead, Dell’s investment thesis remains tethered to its ability to preserve margins within the high-density AI server segment while sustaining gross margin expansion across enterprise storage and commercial client devices. While general macroeconomic uncertainty and competitive pricing dynamics remain variables to monitor, the confluence of expanding data center modernization budgets and the broader hardware refresh cycle continues to provide strong tailwinds for the equity.
Technical Analysis of Dell Technologies Inc (DELL)
Technically, Dell Technologies Inc (DELL) shows a MACD (12,26,9) value of -30.844, indicating a sell signal. The RSI at 30.033 suggests neutral condition and the Williams %R at 89.999 suggests oversold condition. Please monitor closely.
Media Coverage of Dell Technologies Inc (DELL)
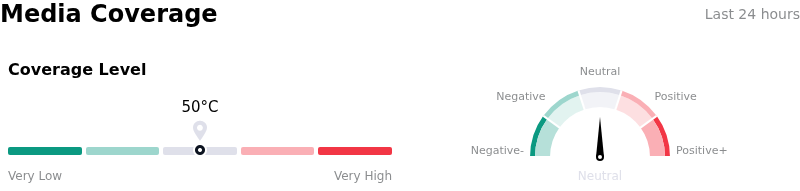
In terms of media coverage, Dell Technologies Inc (DELL) shows a coverage score of 50, indicating a moderate level of media attention. The overall market sentiment index is currently in neutral zone.
Fundamental Analysis of Dell Technologies Inc (DELL)
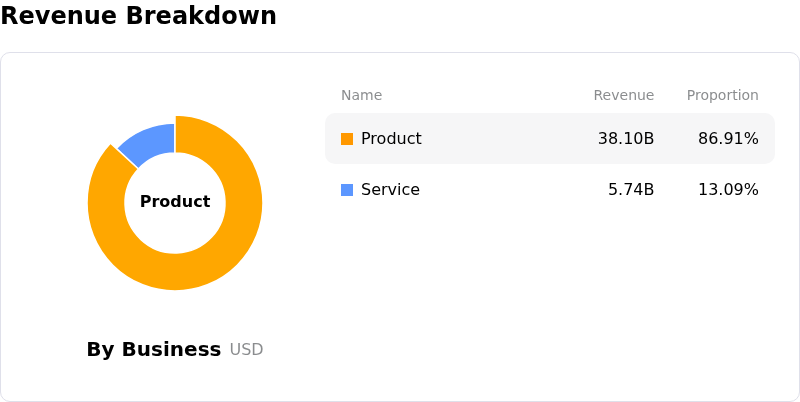
Dell Technologies Inc (DELL) is in the Technology Equipment industry. Its latest annual revenue is $113.54B, ranking 2 in the industry. The net profit is $5.94B, ranking 4 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $588.12, a high of $700.00, and a low of $499.80.
More details about Dell Technologies Inc (DELL)
Company Specific Risks:
- Infrastructure Solutions Margin Dilution: Rapid growth in AI-optimized server shipments is diluting blended operating margins within Dell's Infrastructure Solutions Group (ISG) toward mid-single digits compared to higher-margin legacy storage and enterprise servers, with component cost inflation and peer gross margin contractions compounding institutional fears of structural margin degradation.
- Data Center Permitting and Regulatory Headwinds: Recent political developments and proposed moratoriums on data center construction across key infrastructure corridors—most notably Texas, which accounts for over a quarter of planned domestic capacity—threaten to delay facility build-outs and impair the delivery cadence of Dell's $95 billion AI server backlog.
- Client Solutions Group Demand Contraction: Persisting headwinds in the personal computer market and cautionary shipment forecasts from core silicon suppliers have renewed pressure on Dell's Client Solutions Group (CSG), signaling delayed commercial hardware refresh cycles and extended unit volume weakness.
- Neocloud Customer Concentration and Credit Exposure: A substantial share of Dell's enterprise AI backlog is tied to tier-two specialized cloud providers ("neoclouds") undergoing debt market and financing strains, exposing Dell to potential delivery deferrals, extended receivables collection cycles, and working capital constraints.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles










Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.