


Taiwan Semiconductor Manufacturing Co Ltd Stock (TSM) Opened Up by 7.51% on Nov 6: Drivers Behind the Movement


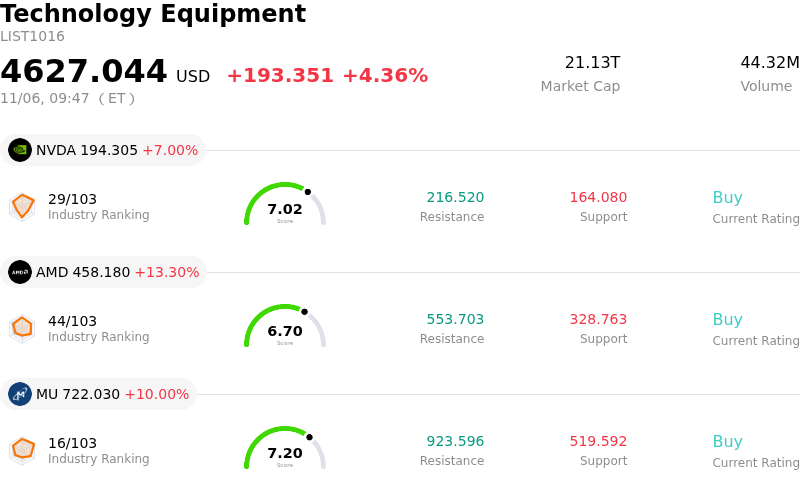
Taiwan Semiconductor Manufacturing Co Ltd (TSM) opened up by 7.51%. The Technology Equipment sector is up by 4.36%. The company outperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) up 6.71%; Advanced Micro Devices Inc (AMD) up 12.54%; Micron Technology Inc (MU) up 9.69%.
What is driving Taiwan Semiconductor Manufacturing Co Ltd (TSM)’s stock price up today?
Taiwan Semiconductor Manufacturing Company recorded substantial upward momentum today, primarily driven by accelerating demand across high-performance computing and artificial intelligence infrastructure. Industry updates and supply chain channel checks continue to indicate robust order commitments from premier hyperscaler and fabless design clients. This sustained appetite reinforces TSMC’s unparalleled pricing leverage across advanced leading-edge nodes, particularly its three-nanometer and upcoming two-nanometer platforms. As global tech giants maintain aggressive capital expenditure budgets directed toward generative AI workloads, TSMC remains the definitive foundational beneficiary of the expanding silicon cycle.
Market sentiment was further energized by accelerating progress in advanced packaging throughput, particularly within Chip-on-Wafer-on-Substrate capacity. Lingering supply bottlenecks that previously constrained the delivery of cutting-edge computing accelerators have steadily diminished as newly commissioned packaging facilities ramp up operations. Furthermore, consistent yield enhancements across premier production lines have reaffirmed institutional confidence in the company’s structural gross margin profile, effectively offsetting market concerns regarding elevated operational depreciation costs tied to its ongoing international fab expansions.
Institutional positioning and macroeconomic tailwinds also provided meaningful support during the session. Broad-based easing in global rate expectations and favorable risk appetite triggered an aggressive rotation back into foundational semiconductor leaders with defensible cash flows and visible multi-year growth runways. Analysts have steadily upgraded medium-term earnings forecasts, citing higher blended average selling prices and high wafer utilization rates. While long-term geopolitical crosscurrents remain a persistent structural consideration, TSMC’s irreplaceable manufacturing moat and pivotal role in enabling the global computing architecture continue to attract decisive institutional buying.
Technical Analysis of Taiwan Semiconductor Manufacturing Co Ltd (TSM)
Technically, Taiwan Semiconductor Manufacturing Co Ltd (TSM) shows a MACD (12,26,9) value of -12.014, indicating a sell signal. The RSI at 37.993 suggests neutral condition and the Williams %R at 67.812 suggests sell condition. Please monitor closely.
Fundamental Analysis of Taiwan Semiconductor Manufacturing Co Ltd (TSM)
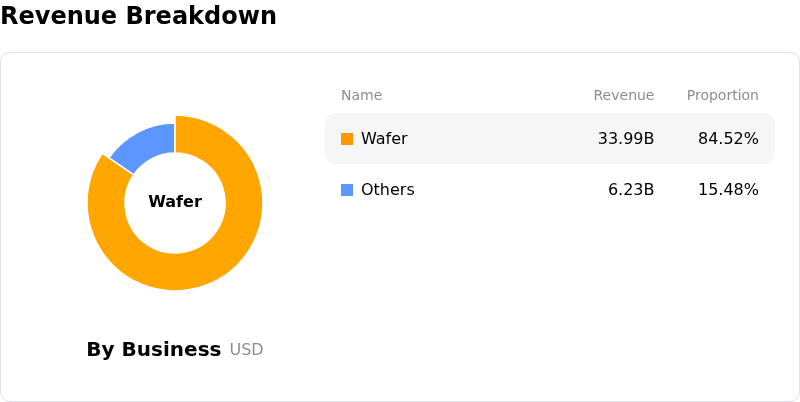
Taiwan Semiconductor Manufacturing Co Ltd (TSM) is in the Technology Equipment industry. Its latest annual revenue is $122.22B, ranking 3 in the industry. The net profit is $55.12B, ranking 3 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $574.04, a high of $715.86, and a low of $440.00.
More details about Taiwan Semiconductor Manufacturing Co Ltd (TSM)
Company Specific Risks:
- Downstream AI Infrastructure Permitting and Demand Uncertainty: Rising regulatory scrutiny and political headwinds targeting regional U.S. power grids and data-center construction pipelines threaten to delay hyperscaler project timelines, sparking institutional concern that decelerating facility rollouts will soften near-term order velocity for TSMC's leading-edge logic nodes and CoWoS advanced packaging capacity.
- Demanding Fourth-Quarter Sequential Revenue Hurdle: Heightened sensitivity surrounds upcoming monthly revenue disclosures as TSMC must meet an aggressive fourth-quarter guidance range of $52.3 billion to $54.3 billion (a ~14.1% sequential top-line step-up), leaving the stock highly vulnerable to multiple compression if monthly receipts show any signs of shipment deceleration.
- Regulatory Compliance and Export Diversion Liabilities: Intensifying cross-border trade restrictions and regulatory enforcement regarding advanced AI silicon transfers increase auditing overhead and legal exposure, heightening the risk of operational disruptions, fines, or lost revenue from constrained customer shipments in Greater China.
- Structural Margin Dilution from Overseas Manufacturing Expansion: Heavy capital expenditure commitments toward overseas fabrication facilities, particularly the Arizona expansion, face persistent operational cost premiums over domestic Taiwanese fabs, threatening structural gross margin dilution as higher foreign depreciation and utility expenses begin hitting the income statement.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.