


Intel Corp Stock (INTC) Moved Down by 6.30% on Nov 5: Key Drivers Unveiled


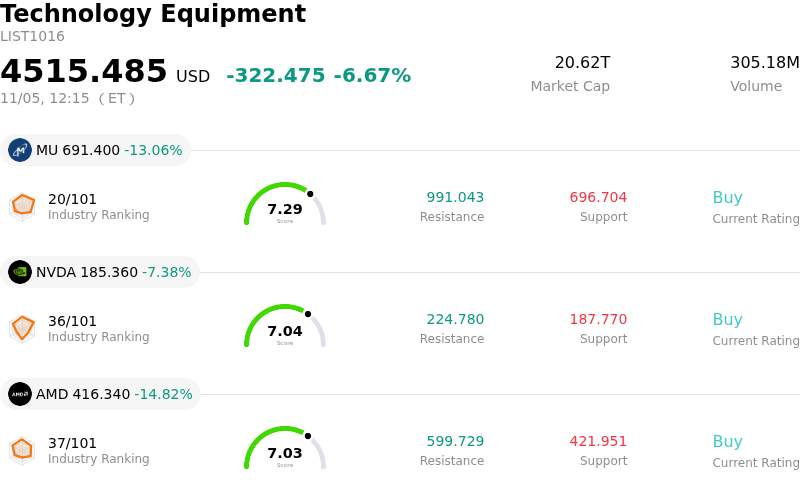
Intel Corp (INTC) moved down by 6.30%. The Technology Equipment sector is down by 6.67%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Micron Technology Inc (MU) down 13.06%; NVIDIA Corp (NVDA) down 7.36%; Advanced Micro Devices Inc (AMD) down 14.64%.
What is driving Intel Corp (INTC)’s stock price down today?
Intel faced continued downward pressure as institutional investors recalibrated expectations following the company's disappointing forward guidance and persistent operational headwinds. While recent top-line figures demonstrated sequential revenue progress, management projected fourth-quarter revenue well short of Wall Street consensus. The lowered outlook underscored a protracted cyclical slowdown in the core personal computer client market, which executive leadership warned will likely extend through the first half of next year. Compounding these top-line concerns, tight supplies of advanced substrate packaging alongside temporary operational disruptions at overseas fabrication facilities have restricted near-term product shipments, preventing the company from meeting immediate demand.
Competitive pressures across the data center and enterprise computing environments have further dampened sentiment. Intel continues to face market share erosion in traditional server central processing units from Advanced Micro Devices, as well as headwinds from custom ARM-based processors deployed by major cloud hyperscalers. While broader enterprise demand for computing infrastructure remains healthy, Intel's supply constraints have created an opening for rival architectures to capture high-margin enterprise orders. Concurrently, market participants remain skeptical regarding the scale and timing of Intel's monetization in specialized artificial intelligence acceleration, leading to concerns that gross margins will remain structurally constrained.
Execution risk surrounding the capital-intensive foundry turnaround also continues to weigh on the investment thesis. Investors are seeking greater visibility into the commercialization of advanced manufacturing nodes and the formal execution of binding agreements with external foundry customers. Although recent insider buying by senior leadership provided a brief sentiment cushion, several Wall Street research desks have systematically trimmed earnings projections and lowered target prices. With free cash flow constrained by high capital expenditures and near-term profitability under pressure, institutional portfolio rebalancing has driven the stock lower.
Technical Analysis of Intel Corp (INTC)
Technically, Intel Corp (INTC) shows a MACD (12,26,9) value of -7.676, indicating a sell signal. The RSI at 21.426 suggests sell condition and the Williams %R at 99.034 suggests oversold condition. Please monitor closely.
Media Coverage of Intel Corp (INTC)
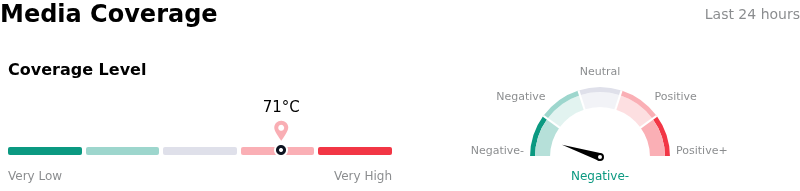
In terms of media coverage, Intel Corp (INTC) shows a coverage score of 71, indicating a high level of media attention. The overall market sentiment index is currently in extremely bearish zone.
Fundamental Analysis of Intel Corp (INTC)
Intel Corp (INTC) is in the Technology Equipment industry. Its latest annual revenue is $52.85B, ranking 6 in the industry. The net profit is $-267.00M, ranking 111 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Hold, with an average price target of $91.99, a high of $160.00, and a low of $63.00.
More details about Intel Corp (INTC)
Company Specific Risks:
- Severe Near-Term Gross Margin Compression: Intel's forward guidance projects a steep contraction in non-GAAP gross margin down to 38.0% in Q4 from 44.1% in Q3, pressured by ramping costs on new process nodes and an operational accident disrupting production at its Israel fabrication facility.
- Prolonged Demand Contraction in Client Computing: The core Client Computing Group faces accelerating weakness, with management projecting global PC shipments to decline 12% in 2026 and an additional 10% in 2027 as surging memory and component costs suppress OEM client processor procurement.
- Packaging Substrate and Server Supply Bottlenecks: Widespread shortages in advanced chip-packaging substrates and wafer supply are restricting Intel's server CPU deliveries, leaving the company unable to satisfy immediate demand and risking data center market share loss to competitors like Advanced Micro Devices.
- Disappointing Q4 Guidance and Widespread Analyst Downgrades: Q4 revenue guidance of $15.0 billion to $16.0 billion and EPS guidance of $0.25 missed Wall Street consensus ($17.1 billion and $0.43) significantly, triggering immediate price target cuts and rating downgrades from institutional brokerages including BofA Securities and Baird.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.