


Lam Research Corp Stock (LRCX) Moved Down by 4.14% on Nov 2: Key Drivers Unveiled


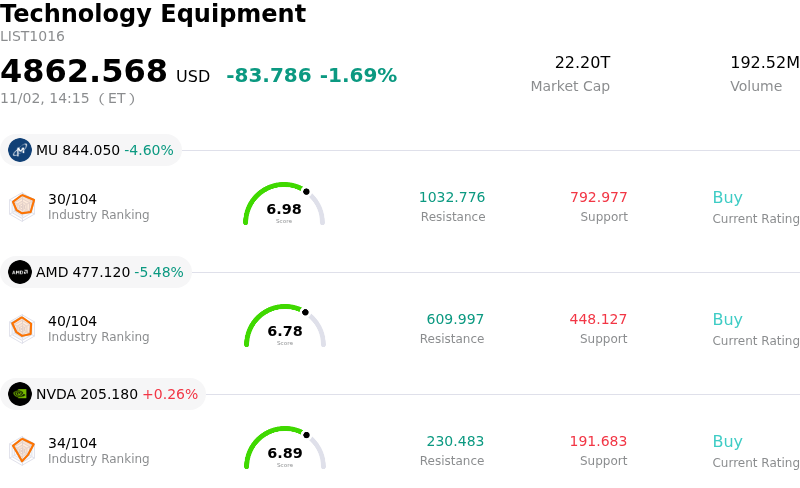
Lam Research Corp (LRCX) moved down by 4.14%. The Technology Equipment sector is down by 1.69%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Micron Technology Inc (MU) down 4.63%; Advanced Micro Devices Inc (AMD) down 5.57%; NVIDIA Corp (NVDA) up 0.24%.
What is driving Lam Research Corp (LRCX)’s stock price down today?
The downward momentum and heightened intraday volatility in Lam Research shares stem from a combination of supply chain friction, caution surrounding regional revenue deceleration, and profit-taking following a prolonged rally. Although the semiconductor equipment manufacturer delivered record financial results for its fiscal first quarter, management highlighted operational bottlenecks and supply constraints that cap tool delivery speed. Furthermore, guidance pointing toward moderating sales from China in subsequent quarters generated near-term caution among investors evaluating the sustainability of sequential revenue acceleration.
Market sentiment has also been tempered by executive insider activity and institutional portfolio adjustments. SEC filings indicating share dispositions by senior executives, including Chief Executive Officer Timothy Archer and board members, led some market participants to adopt a more conservative posture regarding short-term price appreciation. In addition, quarterly institutional filings revealed position trimming by select investment funds seeking to lock in gains after the stock's substantial multi-month advance, further amplifying intraday selling pressure.
From a valuation perspective, the stock has traded at an elevated premium compared to historical averages following strong multi-quarter momentum driven by the artificial intelligence hardware buildout. When high-valuation semiconductor equipment stocks encounter short-term delivery bottlenecks, intraday volatility tends to increase as momentum traders reduce risk. Nevertheless, institutional research indicates that core long-term drivers remain intact, supported by expanding wafer fabrication equipment spending, robust high-bandwidth memory demand, solid operating margins, and sustained capital returns.
Technical Analysis of Lam Research Corp (LRCX)
Technically, Lam Research Corp (LRCX) shows a MACD (12,26,9) value of -5.976, indicating a sell signal. The RSI at 31.149 suggests neutral condition and the Williams %R at 93.906 suggests oversold condition. Please monitor closely.
Media Coverage of Lam Research Corp (LRCX)
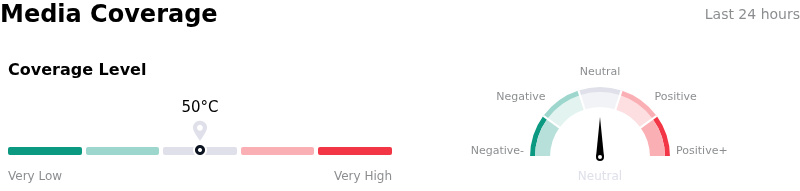
In terms of media coverage, Lam Research Corp (LRCX) shows a coverage score of 50, indicating a moderate level of media attention. The overall market sentiment index is currently in neutral zone.
Fundamental Analysis of Lam Research Corp (LRCX)
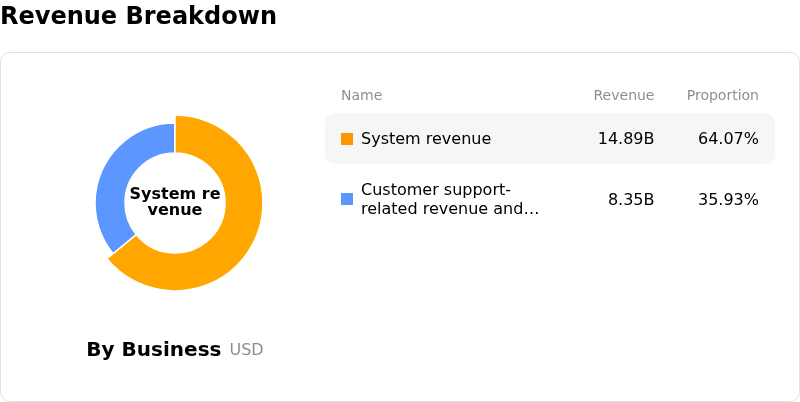
Lam Research Corp (LRCX) is in the Technology Equipment industry. Its latest annual revenue is $23.23B, ranking 12 in the industry. The net profit is $7.27B, ranking 7 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $359.02, a high of $500.00, and a low of $213.00.
More details about Lam Research Corp (LRCX)
Company Specific Risks:
- Supply Chain Bottlenecks Capping Near-Term Guidance: Management disclosed that ongoing supply chain constraints are directly capping December-quarter revenue guidance at $8.6 billion, forcing key equipment shipments into subsequent quarters and triggering aggressive price-target cuts by Wall Street analysts.
- Geopolitical Trade Vulnerability and Projected China Downturn: China accounts for roughly 35% of total revenue, exposing the company to immediate downside risks from potential U.S. export control tightenings and anticipated sharp pullbacks in regional wafer fabrication equipment spending.
- Heavy Executive Insider Share Dispositions: SEC filings reveal persistent insider selling with zero open-market purchases, highlighted by Chief Executive Officer Timothy Archer selling over $7 million in equity alongside additional director share dispositions, dampening institutional sentiment.
- Sequential Growth Deceleration and Valuation De-rating: Quarter-over-quarter revenue growth is decelerating from 22% down to approximately 4.5%, missing heightened buy-side expectations and leaving the stock vulnerable to steep valuation multiple contraction.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.