


Marathon Petroleum Corp Stock (MPC) Moved Down by 3.91% on Oct 29: Key Drivers Unveiled



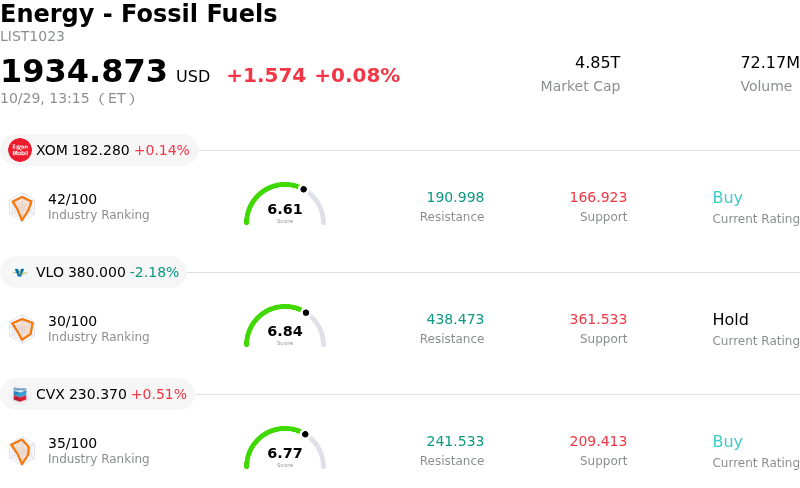
Marathon Petroleum Corp (MPC) moved down by 3.91%. The Energy - Fossil Fuels sector is up by 0.08%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Exxon Mobil Corp (XOM) up 0.15%; Valero Energy Corp (VLO) down 2.18%; Chevron Corp (CVX) up 0.51%.
What is driving Marathon Petroleum Corp (MPC)’s stock price down today?
Marathon Petroleum Corporation experienced downward pressure as broader downstream energy sector dynamics and refining margin concerns weighed on investor sentiment. Across the refining industry, market participants have grown increasingly cautious regarding a potential contraction in crack spreads and fuel margins following a period of elevated profitability. Profit-taking across major refining peers underscored a broader shift in capital allocation, as volatile crude oil prices and softening product demand expectations led institutional investors to re-evaluate near-term exposure to downstream equities ahead of third-quarter corporate earnings.
Company-specific operational factors also contributed to the cautious sentiment ahead of Marathon Petroleum's scheduled third-quarter financial release. Management previously guided to approximately $290 million in planned turnaround and refinery maintenance expenditures, primarily concentrated across Gulf Coast and Mid-Continent processing units. These elevated maintenance activities temporarily constrain secondary conversion unit availability, limit product upgrading capacity, and push per-barrel refining operating expenses higher. Although the company recently announced a 10 percent quarterly dividend increase, market attention remained focused on cost pressures and whether refining margin capture can sustain previous peak levels.
Investor sentiment remains sensitive following a substantial rally earlier in the year, which set a high valuation bar for upcoming operational results. With third-quarter earnings scheduled for early November, market participants appear to be de-risking positions to navigate potential headwinds from elevated turnaround costs, margin normalization, and forward guidance.
Technical Analysis of Marathon Petroleum Corp (MPC)
Technically, Marathon Petroleum Corp (MPC) shows a MACD (12,26,9) value of -14.936, indicating a neutral signal. The RSI at 42.873 suggests neutral condition and the Williams %R at 95.659 suggests oversold condition. Please monitor closely.
Fundamental Analysis of Marathon Petroleum Corp (MPC)
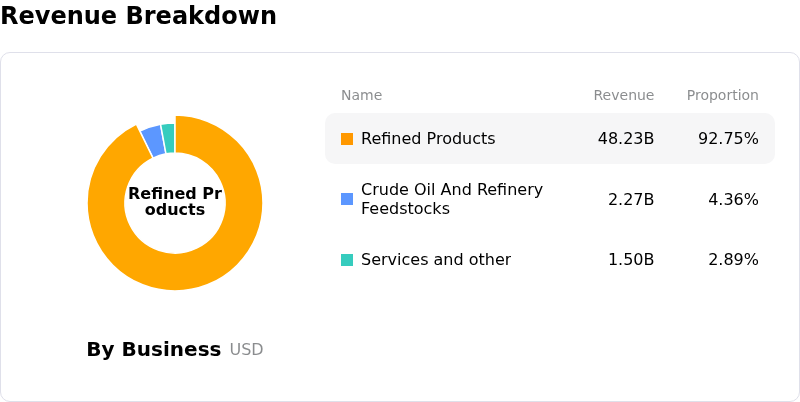
Marathon Petroleum Corp (MPC) is in the Energy - Fossil Fuels industry. Its latest annual revenue is $133.43B, ranking 6 in the industry. The net profit is $4.04B, ranking 13 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $425.11, a high of $560.00, and a low of $186.93.
More details about Marathon Petroleum Corp (MPC)
Company Specific Risks:
- Planned Refinery Maintenance and Turnaround Headwinds: Management guided to approximately $290 million in planned turnaround costs primarily affecting Gulf Coast and Mid-Continent facilities, which restricts refinery conversion throughput, pushes refining operating costs to $5.60 per barrel, and creates operational drag ahead of Q3 earnings.
- Heightened Valuation and Stretched Earnings Expectations: Following a year-to-date stock rally exceeding 170%, analysts caution that current share prices reflect unsustainably high mid-cycle refining margins, leaving the equity vulnerable to profit-taking and multiple contraction if upcoming Q3 results fail to beat elevated consensus expectations.
- Regulatory Risks Over Potential Fuel Export Restrictions: Federal policy discussions regarding potential bans or limits on U.S. diesel exports to cool domestic fuel inflation pose a direct risk to Marathon's foreign market access and threaten to compress domestic refining crack spreads.
- Operating Cost Pressure and Refining Margin Normalization: Escalating distribution costs guided at $1.65 billion and corporate expenses of $260 million, combined with the fading of one-time margin capture tailwinds like derivative unwinds, expose the company to margin compression as global refining capacity stabilizes.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.