


Oracle Corp Stock (ORCL) Moved Down by 5.18% on Oct 8: A Full Analysis



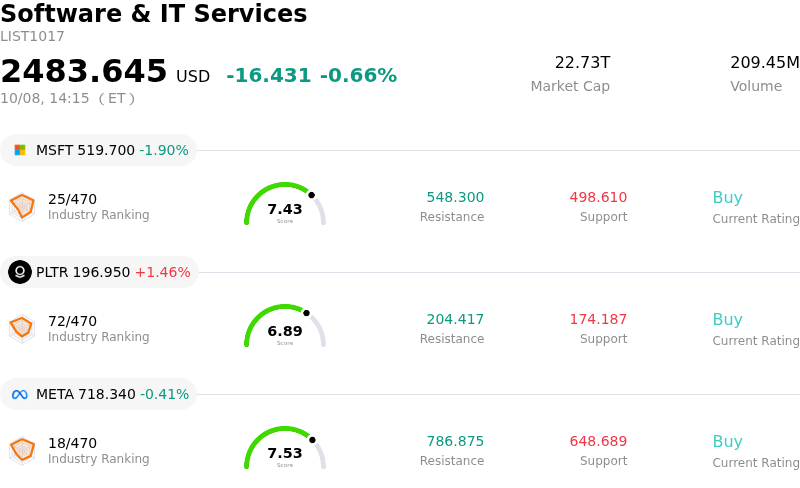
Oracle Corp (ORCL) moved down by 5.18%. The Software & IT Services sector is down by 0.66%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Microsoft Corp (MSFT) down 1.90%; Palantir Technologies Inc (PLTR) up 1.46%; Meta Platforms Inc (META) down 0.41%.
What is driving Oracle Corp (ORCL)’s stock price down today?
Oracle experienced significant downward price volatility driven primarily by emerging counterparty risks surrounding its key artificial intelligence partners. Reports indicated that annualized revenue figures for OpenAI, one of Oracle's prominent cloud infrastructure clients, fell substantially short of previously signaled targets. Because Oracle's aggressive enterprise valuation relies heavily on converting massive contracted cloud infrastructure backlogs into high-margin revenue, revenue discrepancies from major AI clients immediately triggered widespread selling pressure across the sector, hitting Oracle especially hard.
Compounding this sell-off are ongoing market anxieties regarding the company's capital deployment and debt burden. Oracle has committed to an unprecedented capital expenditure expansion to build out massive AI data center capacity, leading to negative free cash flow and substantial debt issuance. Recent reports highlighting extensive private debt financing plans and off-balance-sheet structures to fund expensive AI hardware have raised institutional concerns over leverage, high borrowing costs, and prospective credit rating pressures, overshadowing long-term backlog growth.
Macroeconomic conditions further exacerbated intraday downward momentum. A surge in ten-year Treasury yields to multi-decade highs created a broad risk-off environment for high-valuation, capital-intensive technology companies. Simultaneously, localized operational delays on major data center projects and fallout from security compliance costs in enterprise health segments have compounded near-term execution risks, prompting market participants to re-evaluate their short-term risk premium.
While long-term secular demand for enterprise cloud computing remains intact, Oracle's near-term share performance is increasingly sensitive to the financial health of its AI customer base and its balance sheet management. Investors are closely scrutinizing upcoming corporate events and financing disclosures to ensure that capital spending translates into sustainable cash generation in a higher-for-longer interest rate environment.
Technical Analysis of Oracle Corp (ORCL)
Technically, Oracle Corp (ORCL) shows a MACD (12,26,9) value of -0.351, indicating a sell signal. The RSI at 41.854 suggests neutral condition and the Williams %R at 80.064 suggests oversold condition. Please monitor closely.
Media Coverage of Oracle Corp (ORCL)
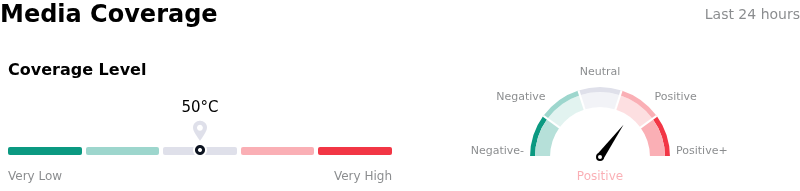
In terms of media coverage, Oracle Corp (ORCL) shows a coverage score of 50, indicating a moderate level of media attention. The overall market sentiment index is currently in bullish zone.
Fundamental Analysis of Oracle Corp (ORCL)
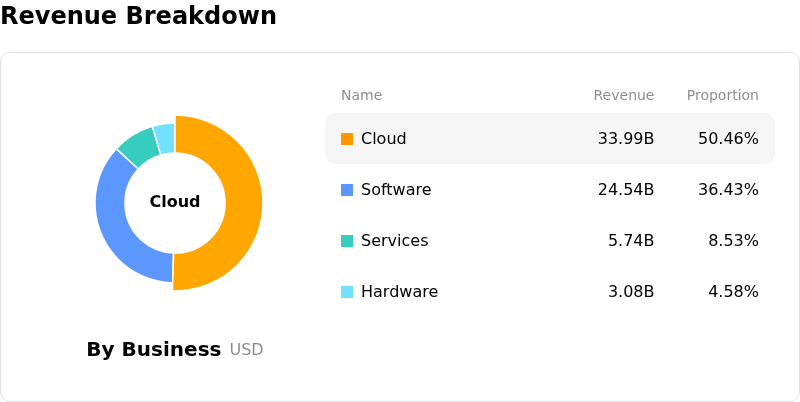
Oracle Corp (ORCL) is in the Software & IT Services industry. Its latest annual revenue is $67.36B, ranking 8 in the industry. The net profit is $16.98B, ranking 6 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $246.26, a high of $400.00, and a low of $110.00.
More details about Oracle Corp (ORCL)
Company Specific Risks:
- Extreme Capital Outlays and Dilution Risk: Recent analyst updates from Mizuho and DA Davidson highlight severe cash burn, reflected in negative $23.7 billion free cash flow driven by aggressive AI infrastructure spending. Oracle's plan to raise up to $50 billion through debt and equity offerings exposes shareholders to immediate equity dilution and increases debt servicing costs on an already heavily leveraged balance sheet.
- Major Data Center Development Delays: Construction bottlenecks and permitting hurdles at key AI compute hubs—specifically gas pipeline delays pushing full operation of the 2.45 GW Project Jupiter site in New Mexico into 2027 alongside force majeure notices issued to infrastructure partners—raise execution risks that could delay planned capacity delivery and backlog monetization.
- Near-Term Margin Compression: Institutional research flags structural pressure on operating profitability as Oracle's revenue mix shifts rapidly toward lower-margin AI cloud infrastructure (OCI) services, eroding overall gross margins relative to legacy high-margin software database products during this intensive buildout phase.
- Rising Utility and Power Cost Liabilities: To clear regional regulatory hurdles and secure power for its massive data centers, Oracle committed to absorbing roughly $300 million in Point Beach nuclear plant cost overruns and fully funding microgrid infrastructure in Wisconsin, creating unanticipated operational cost commitments.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.