


Eli Lilly and Co Stock (LLY) Moved Down by 3.09% on Oct 8: Facts Behind the Movement



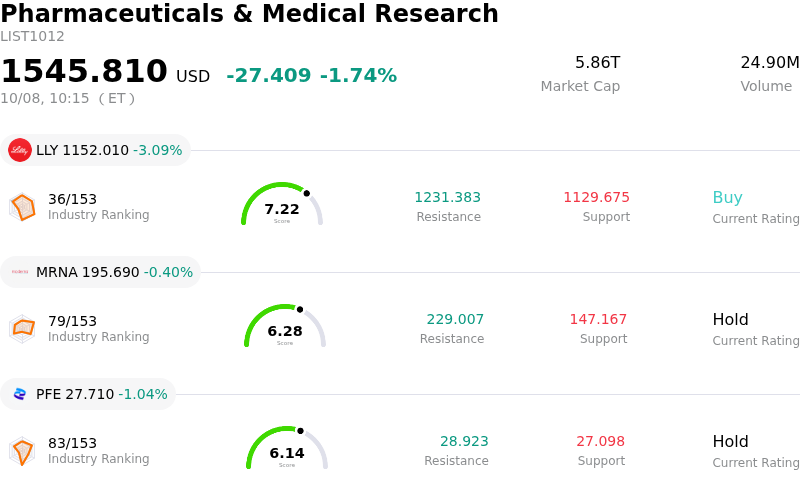
Eli Lilly and Co (LLY) moved down by 3.09%. The Pharmaceuticals & Medical Research sector is down by 1.74%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Eli Lilly and Co (LLY) down 3.09%; Moderna Inc (MRNA) down 0.28%; Pfizer Inc (PFE) down 1.04%.
What is driving Eli Lilly and Co (LLY)’s stock price down today?
Eli Lilly experienced a sharp pull-back following a previous-session rally, as short-term profit-taking and valuation sensitivity took center stage. After surging on positive analyst target revisions and upbeat clinical developments, the stock faced resistance near its high valuation multiples. With the company trading at elevated forward price-to-earnings multiples relative to the broader healthcare sector, market participants demonstrated heightened sensitivity to execution risk ahead of the upcoming third-quarter earnings report, prompting tactical rebalancing by momentum investors.
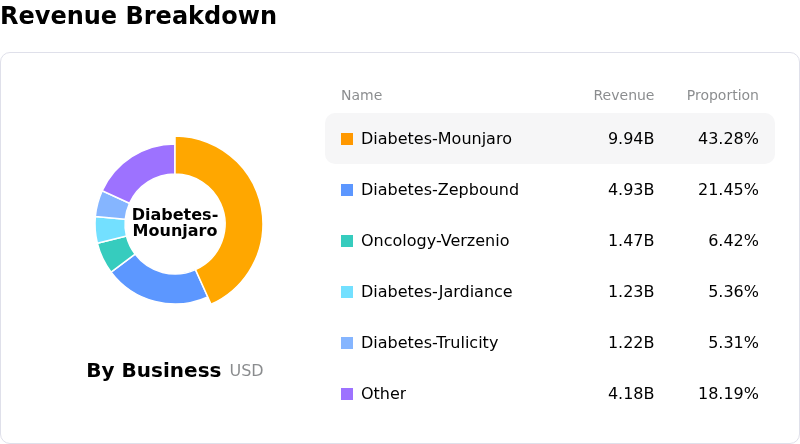
A key factor driving cautious sentiment revolves around realized pricing dynamics within the company's core cardiometabolic and obesity franchise. While prescription volumes for blockbuster GLP-1 treatments Mounjaro and Zepbound remain strong, expanding commercial and government insurance coverage has introduced net price erosion. As favorable first-half rebate and discount accounting adjustments dissipate in the second half of the year, investors are closely monitoring whether rapid volume growth can fully offset lower net realized pricing per patient.
Technical selling pressure was further amplified by institutional supply developments, including a prominent endowment's SEC disclosure to liquidate a sizable tranche of common shares. Combined with ongoing competitive moves from industry rivals in the weight-loss segment and regulatory scrutiny regarding drug pricing, these factors created short-term headwinds. Nonetheless, Wall Street maintains a constructive medium-term outlook, underpinned by pipeline advancements in next-generation therapies like retatrutide, recent oncology label expansions, and international growth momentum.
Technical Analysis of Eli Lilly and Co (LLY)
Technically, Eli Lilly and Co (LLY) shows a MACD (12,26,9) value of 1.857, indicating a neutral signal. The RSI at 46.469 suggests neutral condition and the Williams %R at 81.114 suggests oversold condition. Please monitor closely.
Media Coverage of Eli Lilly and Co (LLY)
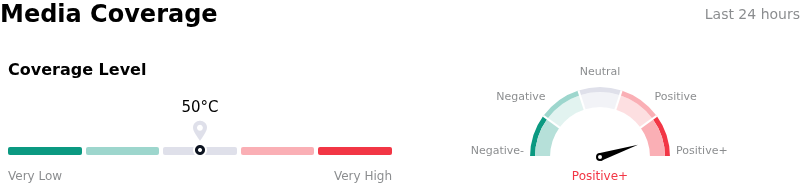
In terms of media coverage, Eli Lilly and Co (LLY) shows a coverage score of 50, indicating a moderate level of media attention. The overall market sentiment index is currently in extremely bullish zone.
Fundamental Analysis of Eli Lilly and Co (LLY)
Eli Lilly and Co (LLY) is in the Pharmaceuticals & Medical Research industry. Its latest annual revenue is $65.18B, ranking 4 in the industry. The net profit is $20.64B, ranking 2 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $1306.81, a high of $1600.00, and a low of $891.22.
More details about Eli Lilly and Co (LLY)
Company Specific Risks:
- Accelerating Net Price Erosion on Flagship GLP-1 Drugs: Eli Lilly faces margin compression risk as realized U.S. prices for core revenue drivers Zepbound and Mounjaro experience 9% to 15% year-over-year declines due to expanded insurance rebate concessions, making top-line growth highly dependent on unflagging prescription volume.
- High Discontinuation Rates in Next-Gen Obesity Candidates: Phase 2b trial data for the experimental EloraTZP combination drug revealed elevated patient treatment drop-out rates ranging from 10.8% to 27.0% due to gastrointestinal side effects, posing tolerability and clinical trial execution hurdles for Phase 3 development.
- Competitor Litigation and Marketing Restraints: Key competitor Novo Nordisk has initiated legal proceedings asking courts to order the withdrawal of Eli Lilly's comparative marketing campaigns for its obesity drugs, creating regulatory scrutiny and potential commercial disruption.
- High Valuation Multiple Exposure Ahead of Earnings: Carrying a forward P/E ratio near 38x to 40x and a price-to-sales ratio above 13x, institutional commentary notes that any revenue miss, margin narrowing, or conservative guidance update in the upcoming Q3 report could trigger sharp downside volatility.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.