


Accenture PLC Stock (ACN) Opened Up by 3.25% on Oct 8: What Investors Need To Know



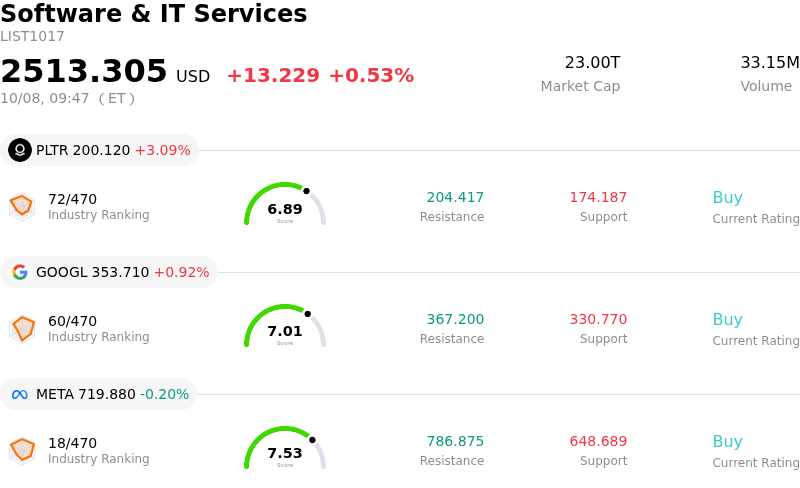
Accenture PLC (ACN) opened up by 3.25%. The Software & IT Services sector is up by 0.53%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Palantir Technologies Inc (PLTR) up 3.19%; Alphabet Inc Class A (GOOGL) up 0.82%; Meta Platforms Inc (META) up 0.10%.
What is driving Accenture PLC (ACN)’s stock price up today?
Accenture traded notably higher during the session, driven primarily by a major strategic partnership announcement alongside renewed bullish commentary from Wall Street analysts. The global IT services provider announced the launch of the Accenture Dell Business Group, expanding its long-standing collaboration with Dell Technologies. The dedicated unit aims to assist enterprise clients in deploying private artificial intelligence infrastructure, agentic AI workloads, and modernizing legacy IT systems. The announcement highlighted Accenture's plans to train several thousand specialized practitioners on Dell's enterprise hardware and software, positioning the firm to capture growing enterprise demand for secure, on-premises, and sovereign AI solutions across regulated sectors.
Institutional sentiment was further fortified by positive sell-side research coverage. Analysts at UBS reaffirmed a Buy rating on the stock with a street-high price target, citing rapid growth in emerging alliance revenues and robust booking trends. The firm emphasized that expanding technology alliance partnerships effectively mitigates broader market concerns regarding potential disruptions from AI automation on traditional IT consulting models. Market participants also began positioning ahead of Accenture's upcoming Investor Day, where management is expected to outline long-term growth vectors and margin expansion framework tied to enterprise AI adoption.
This positive movement builds upon broader momentum established after the company reported strong fourth-quarter financial results. That report showcased record full-year client bookings, revenue beating the upper end of management's guidance, and an encouraging top-line growth outlook for the upcoming fiscal year. Coupled with a recent dividend increase and ongoing share repurchase programs, the fundamental narrative surrounding Accenture continues to reflect operational resilience and strong competitive alignment within the enterprise digital transformation market.
Technical Analysis of Accenture PLC (ACN)
Technically, Accenture PLC (ACN) shows a MACD (12,26,9) value of 2.775, indicating a buy signal. The RSI at 60.609 suggests neutral condition and the Williams %R at 44.281 suggests buy condition. Please monitor closely.
Fundamental Analysis of Accenture PLC (ACN)
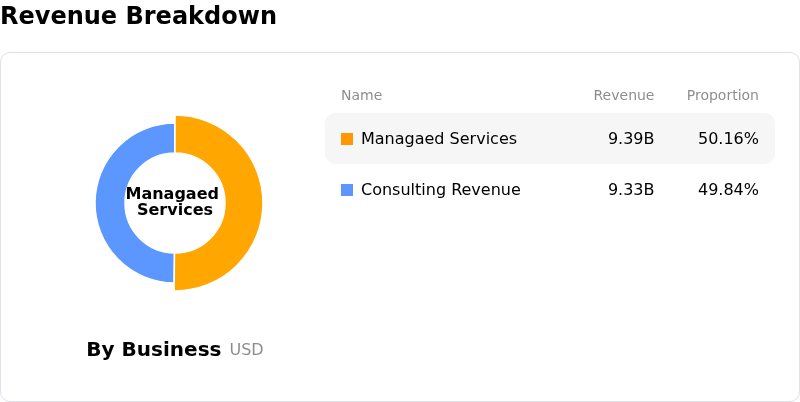
Accenture PLC (ACN) is in the Software & IT Services industry. Its latest annual revenue is $74.18B, ranking 6 in the industry. The net profit is $8.37B, ranking 13 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $229.65, a high of $329.00, and a low of $185.00.
More details about Accenture PLC (ACN)
Company Specific Risks:
- Weak Organic Growth and M&A Dependence: Fiscal 2027 guidance projects 3% to 6% local-currency revenue growth, but acquisitions are expected to contribute 2.0% to 2.5% of that total, signaling underlying organic growth stagnation near 0.5% to 3.5% and increasing M&A integration risk.
- Structural AI Disruption to Core Services: Institutional analysts highlight ongoing structural risks to systems integration and application development—which account for nearly half of Accenture's revenue—as generative AI automation commoditizes labor-intensive consulting hours and intensifies pricing pressure.
- Sluggish Discretionary Spending and Margin Headwinds: Ongoing enterprise client caution and deferrals of non-critical consulting projects, paired with elevated investments and heavy multi-year capital commitments in AI infrastructure, threaten to drag first-half fiscal 2027 operating margins below full-year targets.
- Reduced Share Repurchase Activity: Management's capital allocation outlook for fiscal 2027 indicates a pull-back in share buyback intensity relative to fiscal 2026's record repurchases, reducing buyback-driven EPS support and dampening capital return yields.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.