


Bank of Nova Scotia Stock (BNS) Moved Down by 3.11% on Oct 7: Drivers Behind the Movement



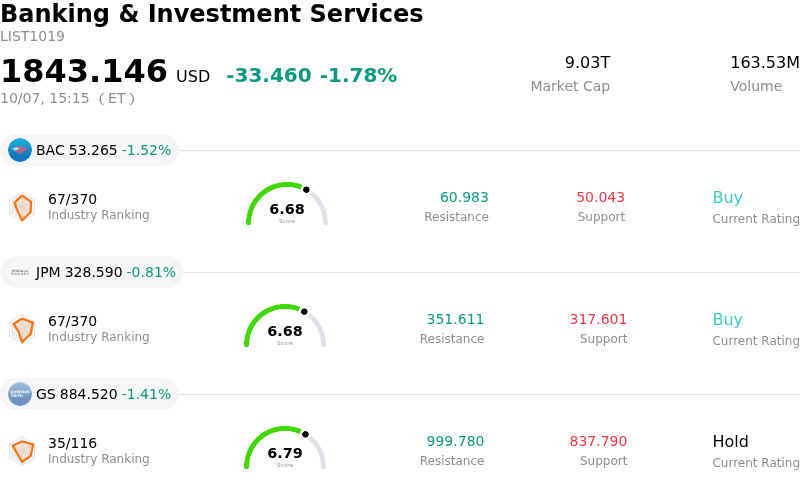
Bank of Nova Scotia (BNS) moved down by 3.11%. The Banking & Investment Services sector is down by 1.78%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Bank of America Corp (BAC) down 1.52%; JPMorgan Chase & Co (JPM) down 0.80%; Goldman Sachs Group Inc (GS) down 1.41%.
What is driving Bank of Nova Scotia (BNS)’s stock price down today?
The downward movement in Bank of Nova Scotia shares during the trading session reflects a combination of post-dividend price adjustments and profit-taking across the financial sector. The bank recently reached its ex-dividend date for its regular quarterly distribution, which routinely prompts a technical resetting of the share price as the dividend value is carved out of the equity valuation. In addition, following a strong multi-month run for Canadian banking equities, short-term market participants engaged in profit-taking, unwinding positions after a sustained period of outperformance relative to the broader financial index.
From a corporate perspective, fundamental drivers for the institution remain active and structurally supportive. Regulators recently approved a significant expansion of the bank's normal course issuer bid, permitting the repurchase and cancellation of up to forty million common shares. While this expanded buyback authorization underscores management's confidence in its capital generation and balance sheet strength, the market appears to have largely priced in the policy shift during prior sessions. Furthermore, after trading at premium valuation multiples compared to historical averages, the stock faced valuation friction, leading some institutional managers to rebalance holdings as forward earnings multiples stretched above long-term norms.
Looking ahead, institutional focus is likely to center on upcoming quarterly credit performance and the broader interest rate trajectory in North American markets. While the company maintains strong capital return mechanisms through buybacks and reliable income distributions, macro credit risks and lingering economic uncertainty continue to weigh on immediate upside momentum. Investors will be monitoring incoming economic disclosures and credit-loss provisioning trends to gauge whether operational performance can sustain current capital deployment strategies.
Technical Analysis of Bank of Nova Scotia (BNS)
Technically, Bank of Nova Scotia (BNS) shows a MACD (12,26,9) value of -1.110, indicating a neutral signal. The RSI at 37.917 suggests neutral condition and the Williams %R at 100.000 suggests oversold condition. Please monitor closely.
Fundamental Analysis of Bank of Nova Scotia (BNS)
Bank of Nova Scotia (BNS) is in the Banking & Investment Services industry. Its latest annual revenue is $26.44B, ranking 18 in the industry. The net profit is $5.20B, ranking 25 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Hold, with an average price target of $98.23, a high of $99.46, and a low of $97.00.
More details about Bank of Nova Scotia (BNS)
Company Specific Risks:
- Technical Breakdown and Dominant Selling Pressure: Recent trading sessions demonstrate persistent downside momentum as the stock broke below its 20-day and 50-day moving averages, driven by negative momentum indicators and technical selling pressure that outweigh recent capital deployment announcements.
- Elevated Provisions for Credit Losses: Financial disclosures revealed an increase in total provisions for credit losses (PCL) to $1.079 billion, driven by higher impaired loan formations across Canadian commercial and personal banking portfolios.
- Emerging Market Volatility and Underperforming ROE: Institutional analyst commentary highlights persistent headwinds across the bank's Latin American international footprint, where local currency weakness and slower regional growth continue to keep consolidated return on equity below Canadian peer averages.
- Credit Growth Lag and Capital Ratio Contraction: Core domestic loan growth continues to trail peer Canadian institutions, while the Common Equity Tier 1 (CET1) ratio contracted 20 basis points quarter-over-quarter due to higher risk-weighted assets and synthetic risk-transfer securitization recalls.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.