


Danaher Corp Stock (DHR) Moved Down by 3.29% on Oct 1: What Investors Need To Know



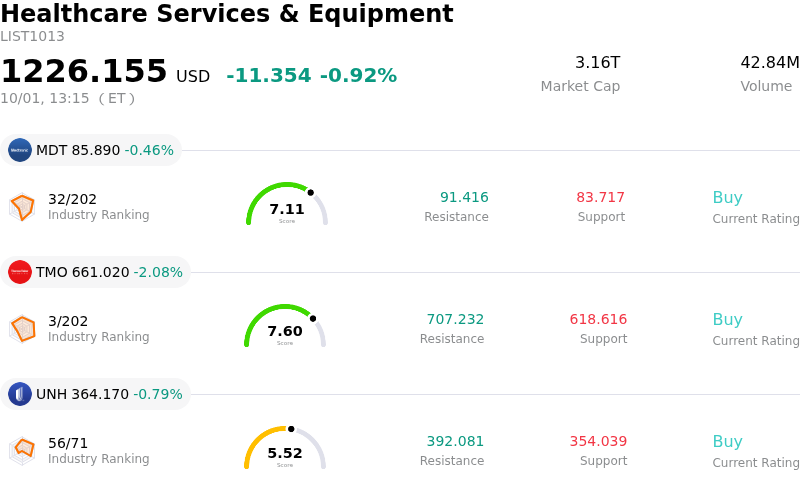
Danaher Corp (DHR) moved down by 3.29%. The Healthcare Services & Equipment sector is down by 0.92%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Medtronic PLC (MDT) down 0.46%; Thermo Fisher Scientific Inc (TMO) down 2.08%; Unitedhealth Group Inc (UNH) down 0.79%.
What is driving Danaher Corp (DHR)’s stock price down today?
Danaher Corporation experienced noticeable downward pressure as profit-taking swept through high-valuation life sciences and healthcare diagnostic stocks at the start of the fourth quarter. Following a strong multi-week rally heading into late September, the stock had rebounded near consensus target price levels, leaving valuation multiples elevated relative to broader market averages and life sciences equipment peers. Consequently, institutional investors opted to lock in recent gains, leaving the equity vulnerable to broader market rotation and sector-wide risk aversion.
The decline also reflects technical momentum shifts following the ex-dividend date for the company's regular quarterly dividend payout. As the dividend entitlement passed, short-term trading flows normalized. Additionally, broader sentiment across the life sciences tools and equipment sector remains cautious. Persistent market concerns regarding biopharmaceutical customer spending patterns, equipment shipment timing, and commercial pricing dynamics in key international regions continue to weigh on market sentiment, counterbalancing optimism surrounding long-term bioprocessing recovery.
Looking ahead, market participants are exercising heightened caution in advance of the upcoming third-quarter earnings release scheduled for later in October. Investors are closely scrutinizing whether bioprocessing equipment order growth can convert efficiently into revenue without further client project deferrals. While core fundamentals, balance sheet strength, and ongoing capital return programs provide long-term support, short-term price action is likely to remain sensitive to macroeconomic sentiment and order visibility heading into the earnings report.
Technical Analysis of Danaher Corp (DHR)
Technically, Danaher Corp (DHR) shows a MACD (12,26,9) value of 0.693, indicating a buy signal. The RSI at 50.395 suggests neutral condition and the Williams %R at 47.065 suggests neutral condition. Please monitor closely.
Fundamental Analysis of Danaher Corp (DHR)
Danaher Corp (DHR) is in the Healthcare Services & Equipment industry. Its latest annual revenue is $24.57B, ranking 7 in the industry. The net profit is $3.61B, ranking 4 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $230.16, a high of $310.00, and a low of $200.00.
More details about Danaher Corp (DHR)
Company Specific Risks:
- Executive Leadership Transition: The official takeover by Julie Sawyer Montgomery as President and CEO on October 1, 2026, introduces operational execution risk and executive transition friction during a critical operational turn.
- Bioprocessing Revenue Deferrals: Commercial drugmakers postponing over $100 million in bioprocessing equipment and chromatography resin orders into 2027 continues to constrain core revenue growth and core margin realization.
- Elevated Valuation Premium vs. Margin Compression: Trading at a premium relative valuation near 40x earnings, the stock remains vulnerable to downside re-rating given multi-year operating margin contraction and modest organic revenue trends.
- M&A Balance Sheet Leverage and China Headwinds: The integration of major acquisitions such as Masimo has increased net debt leverage, while ongoing policy changes and pricing pressures in China impose an estimated $75 million to $100 million revenue drag.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.